
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Teradyne (TER), Why Is It Back In The Spotlight?
Teradyne (TER) has been in focus after two closely timed announcements. The Bright Machines partnership targets AI infrastructure manufacturing, while the Titan HP burn-in upgrade addresses reliability demands in data center and automotive chips.
Teradyne’s recent AI focused announcements land after a powerful run in the shares, with the US$402.68 stock price sitting on a 30 day share price return of 4.95% but a 7 day share price return that declined 10.32%. This suggests momentum has cooled in the very short term, even as the 90 day share price return of 11.98%, year to date share price return of 94.01% and a 1 year total shareholder return of 205.47% keep longer term performance firmly in focus for investors weighing how much of the Titan HP and Bright Machines news is already reflected in the valuation.
Scan other AI hardware and automation opportunities with our curated list of 92 AI infrastructure stocks.
After a move like Teradyne’s, with triple digit 1 year returns and fresh AI headlines in the mix, the real tension is simple: Is meaningful upside still in front of you, or has most of it already passed?
Most Popular Narrative: 10% Undervalued
Against Teradyne’s last close of $402.68, the most followed narrative points to a fair value of $446.47. This frames today’s AI-fueled excitement as only partly reflected in the price.
Teradyne continues to tie more than 60% of its revenue to AI-focused data center demand, with record Q2 2026 revenue of about US$1.33b and guidance for a stronger second half of 2026, which indicates ongoing AI-related test and automation orders that can support future revenue and earnings.
See why 114 investors see Teradyne as 10% undervalued.
Result: Fair Value of $446.47 (UNDERVALUED)
Still, this AI heavy Teradyne story can crack if hyperscaler and data center spending slows, or if higher R&D and sales costs squeeze margins for longer than expected.
Find out about the key risks to this Teradyne narrative.
Another View: Teradyne On Rich Multiples
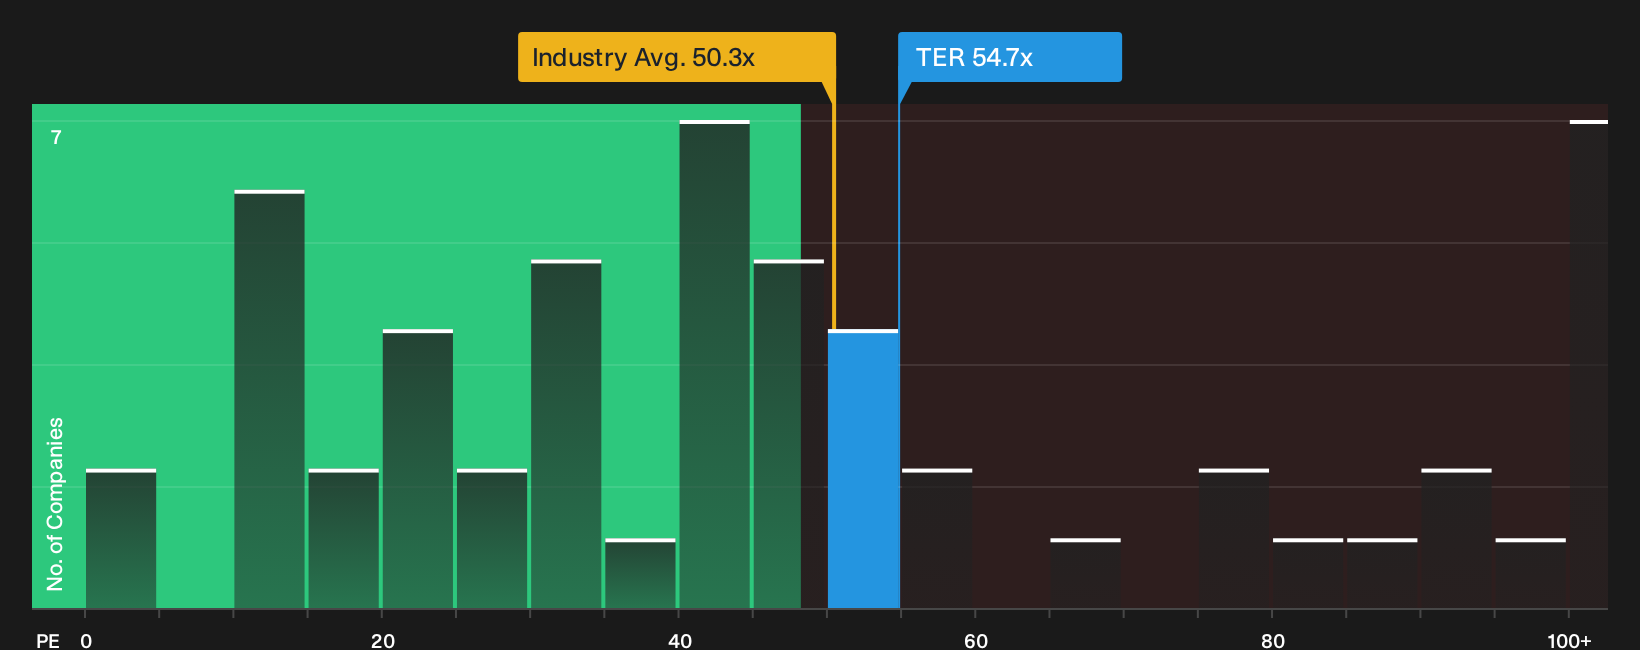
The fair value narrative presents Teradyne as about 10% undervalued, yet the market is already paying a P/E of 54.7x. That is higher than the estimated fair ratio of 42x and above the US Semiconductor industry average of 50.3x, which suggests there may be less margin for error if expectations soften.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in the Teradyne story so far, with both concern and optimism in play, mean the next move relies on how you interpret the data yourself. Take a closer look at the balance between upside and downside through 2 key rewards and 2 important warning signs.
Looking for more Teradyne sized ideas?
If you stop with Teradyne, you risk missing other setups that fit your style, so put a few more potential candidates on your radar today.
- Target value first and see which quality companies still trade at a discount through 28 high quality undervalued stocks.
- Prioritise resilience by scanning a 31 resilient stocks with low risk scores that filters for businesses with steadier risk profiles.
- Hunt for future leaders hiding in plain sight by running the 20 high quality undiscovered gems before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com