
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Zeta Global Holdings (ZETA) Fairly Valued As AthenaOS Fuels Its AI Push?
Zeta Global Holdings (ZETA) triggered fresh attention after unveiling AthenaOS, an enterprise intelligence operating system, alongside the Athena Inference Model built with Fireworks and NVIDIA technology to deepen its AI driven analytics offering.
Those product launches and AI alliances come on top of an acquisition push around Digital Audience and Senso, and the market has responded. Zeta Global Holdings has recorded a 53.98% 90 day share price return and a 79.84% 1 year total shareholder return, which some observers view as momentum building as investors reassess its AI driven profile.
Spot 92 AI infrastructure stocks that, like Zeta Global Holdings, are leaning hard into AI infrastructure and enterprise intelligence as this theme gains more investor attention.After a 90 day climb of 53.98% and a 1 year total return of 79.84%, Zeta Global Holdings now sits at a different starting line. Does the current balance of risk and reward still favor new buyers, or not?
Most Popular Narrative: 2% Overvalued
On the widely followed narrative, Zeta Global Holdings has a fair value estimate of $32.43, which sits slightly below the last close at $33.09. That modest 2% gap is small, so the key question is whether the growth story behind that number holds up.
The analysts have a consensus price target of $32.43 for Zeta Global Holdings based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $2.6 billion, earnings will come to $270.6 million, and it would be trading on a PE ratio of 43.8x, assuming you use a discount rate of 8.7%.
See why 152 investors see Zeta Global Holdings as 2% overvalued.
Result: Fair Value of $32.43 (OVERVALUED)
Still, the narrative could be knocked off course if privacy rules tighten in ways that blunt Zeta Global Holdings' data advantage or if larger software rivals crowd its AI marketing niche.
Find out about the key risks to this Zeta Global Holdings narrative.
Another View: SWS DCF Model Flags Upside
Where the analyst narrative pegs Zeta Global Holdings as about 2% overvalued around $32.43, the Simply Wall St DCF model points in a different direction. On that cash flow view, ZETA at $33.09 trades roughly 35% below an estimated value of $51.03. This raises a blunt question for investors: is the discount a real opportunity, or just a sign that the market is less convinced by those cash flow assumptions than the model is?
For anyone weighing that gap, it helps to see how the SWS DCF model turns long term forecasts into a single number, step by step, rather than treating $51.03 as a black box output. Look into how the SWS DCF model arrives at its fair value.
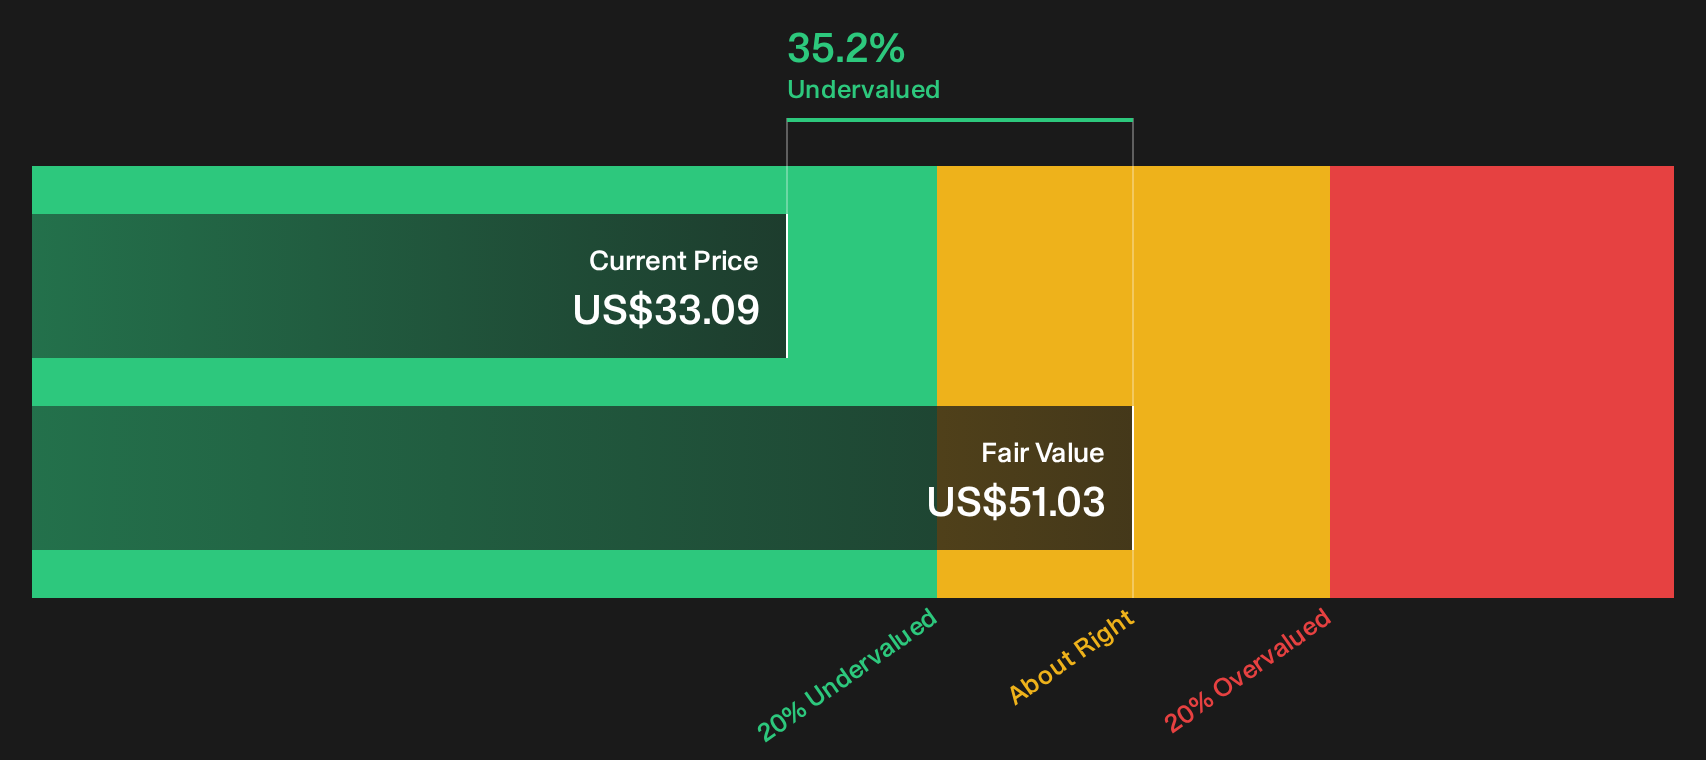
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Zeta Global Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals so far leave you on the fence, that is the perfect moment to lean into the data and form your own take. To see which bright spots are driving some of the optimism around Zeta Global Holdings, start with the 3 key rewards.
Looking for more Zeta Global Holdings style investment ideas?
If you only stop at Zeta Global Holdings, you risk missing other opportunities that fit your goals. Let the screener surface candidates you might never spot yourself.
- Target resilience by scanning companies with strong finances using our list of solid balance sheet and fundamentals (25 results) and compare what you find against your current holdings.
- Hunt for potential mispricing by reviewing our 28 high quality undervalued stocks, then line up those candidates against Zeta Global Holdings to see how they stack up.
- Strengthen your income plan by checking the 8 dividend fortresses so you do not miss companies that combine yield with staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com