
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
A Once-in-a-Decade Opportunity: 2 Magnificent Dividend Stocks Down 34% to 52% I'm Buying Right Now
Key Points
Both stocks are home to niche-leading businesses.
However, each has run into some cyclicality in sales.
But the future remains bright over the long haul.
Though the S&P 500 remains near an all-time high, many steady-Eddie dividend stocks have not gone along for the ride. In fact, many of these top-tier dividend growth stocks have sold off sharply as the market shifted its focus to high-flying AI, semiconductor, and space stocks.
This market rotation leaves me eager to continue buying my favorite dividend payers at a discounted price, and I have identified two that look like once-in-a-decade opportunities right now. Down between 34% and 52%, here's the case for each stock and why I'll be buying each soon.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: Getty Images.
1. Zoetis: Down 52% from its 52-week high
Hand-up accountability: I have been wrong about leading animal and pet care behemoth Zoetis (NYSE: ZTS) over the last few years. The next chapter of the company's growth story (next-gen osteoarthritis medicines for dogs and cats) has stalled for now. This disappointment -- paired with continued declines in U.S. veterinary visits -- has weighed heavily upon the one premium-valued blue chip dividend stock.
Briefly trading at 70 times free cash flow (FCF) during its peak in 2023, Zoetis now trades at only 13 times FCF.
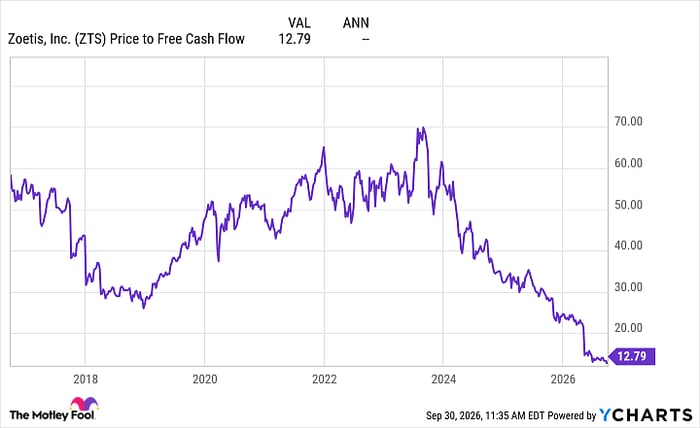
ZTS Price to Free Cash Flow data by YCharts
While there is no sugarcoating the company's recent results, where organic sales dipped 1% and earnings per share only rose 4% last quarter, this once-in-a-decade valuation implies that Zoetis will never grow again -- and I think that's a bit too negative.
The global animal healthcare market is still expected to grow by 5% annually through 2035, and Zoetis remains a leader in the space despite its recent slowdown. Outside of 2020 -- and likely 2026 -- Zoetis has grown sales faster than the broader animal healthcare industry every year since 2013, so this 5% growth could prove conservative.
This notion could prove especially true, since management expects to have 12 blockbusters (treatments with $100 million in annual sales) in its pipeline through 2030. Zoetis is home to 75 years of R&D experience in this niche, so I'm more than happy to receive a growing, well-funded dividend that currently yields 3% while I wait for newer treatments to be approved and to scale.
Lastly, I'm not the only one who thinks Zoetis stock is cheap. After lowering the company's share count by 1.8% annually over the last decade, management has swooped in and retired 8% of Zoetis' outstanding shares in the past year alone, hopefully capitalizing on the stock's deeply discounted price should it eventually rebound, as I expect over the long term.
2. Badger Meter: Down 34% from its 52-week high
I've slowly built a starter position in smart water and advanced metering infrastructure (AMI) provider Badger Meter (NYSE: BMI) over the last couple of years, but the stock's recent dip has me ready to make it a full position. The serial acquirer's sales growth turned negative in its two most recent quarters after growing by double digits in 15 of the 17 previous quarters, and Badger Meter's stock was roughly halved over 18 months.
This sell-off leaves it trading near a decade-long low of 29 times earnings.
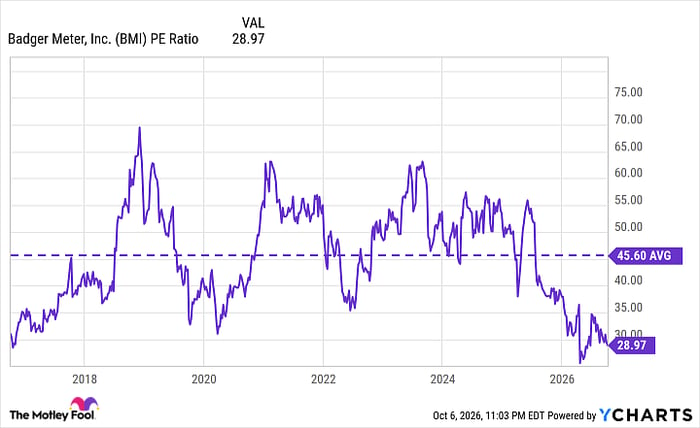
BMI PE Ratio data by YCharts
Better yet for investors, Badger Meter typically generates robust free cash flow (FCF), leaving it trading at an even more alluring 24 times FCF. Simply put, the company's valuation finally makes sense after trading at an average of nearly 50 times earnings over the last decade.
Certainly, declining sales for two straight quarters are eye-catching, but I think it should prove temporary. After growing sales by 24% in 2024 and 11% in 2025, this year's slowdown isn't catastrophic, given that the prior two years' growth was pulled forward more than usual. Furthermore, management explained that the sales figures are lumpy right now because four major projects just ended, while nine new ones are just now getting launched, causing the current cyclicality.
However, over the long haul, Badger Meter continues to shift more of its operations to SaaS sales as it helps water utilities modernize their outdated infrastructure. With 60% of U.S. water meter connections still using outdated meter-reading technologies, the company has immense room for continued growth as it replaces aging water equipment.
Whether it's simple water utility updates, adhering to water quality mandates, managing groundwater, addressing water overuse (a hot debate with data centers right now), monitoring droughts, or providing 24/7 communications to prevent longer-lasting water leaks, Badger Meter will likely only build upon its leadership position over the next decade.
Best yet, Badger Meter has grown its dividend payments by 15% annually over the past decade and will pay a 1.3% yield as investors wait for a turnaround in sales growth.
Josh Kohn-Lindquist has positions in Badger Meter and Zoetis. The Motley Fool has positions in and recommends Zoetis. The Motley Fool has a disclosure policy.