
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Goldman Sachs Thinks You Should Buy the Palantir Stock Dip
Palantir Technologies (PLTR) is strengthening its position in data analytics and artificial intelligence (AI) as businesses increasingly embrace enterprise AI. That momentum has caught Wall Street’s attention, with Goldman Sachs now seeing fresh upside potential in the rapidly growing company.
On Thursday, Oct. 8, Palantir’s shares climbed 2.4% after Goldman’s research team, led by Gabriela Borges, upgraded the stock from “Neutral” to “Buy” and set a 12-month price target of $230. Borges highlighted the company’s impressive scale, noting $6.2 billion in revenue over the last 12 months, $8 billion in annual recurring revenue (ARR), and annual revenue growth of 100%.
Looking ahead, Goldman expects Palantir to enter another phase of outperformance into 2027. Borges also sees its total addressable market expanding significantly, driven by sovereign AI, bespoke applications, and the company’s new verticalization strategy, which could open additional avenues for growth.
Palantir’s forward-deployed engineering (FDE) model offers another potential advantage. Built around close feedback between field teams and product developers, the approach has become sufficiently refined to support automation through AI FDEs.
Although Microsoft (MSFT), Salesforce (CRM), and Snowflake (SNOW) are also expanding their field teams, Goldman believes Palantir has a head start in developing AI agents to scale these operations, strengthening its competitive position.
About Palantir Stock
Headquartered in Aventura, Florida, Palantir Technologies develops software platforms that help governments, intelligence agencies, and businesses integrate complex data, analyze it, and use the resulting insights to make decisions.
Its technology serves a wide range of applications, spanning defense operations, intelligence, enterprise data management, software deployment, and AI. The broad reach has helped Palantir build a market cap of nearly $477.7 billion.
PLTR stock has gained 11% over the last 52 weeks and climbed 16% in 2026. More recently, the rally has accelerated, with shares advancing 60% over the past three months, underscoring the strength of investor interest in the company.
On the valuation front, PLTR stock is currently trading at 122.72 times forward adjusted earnings and 58.15 times sales. Both valuation multiples sit well above industry averages, reflecting high growth expectations.
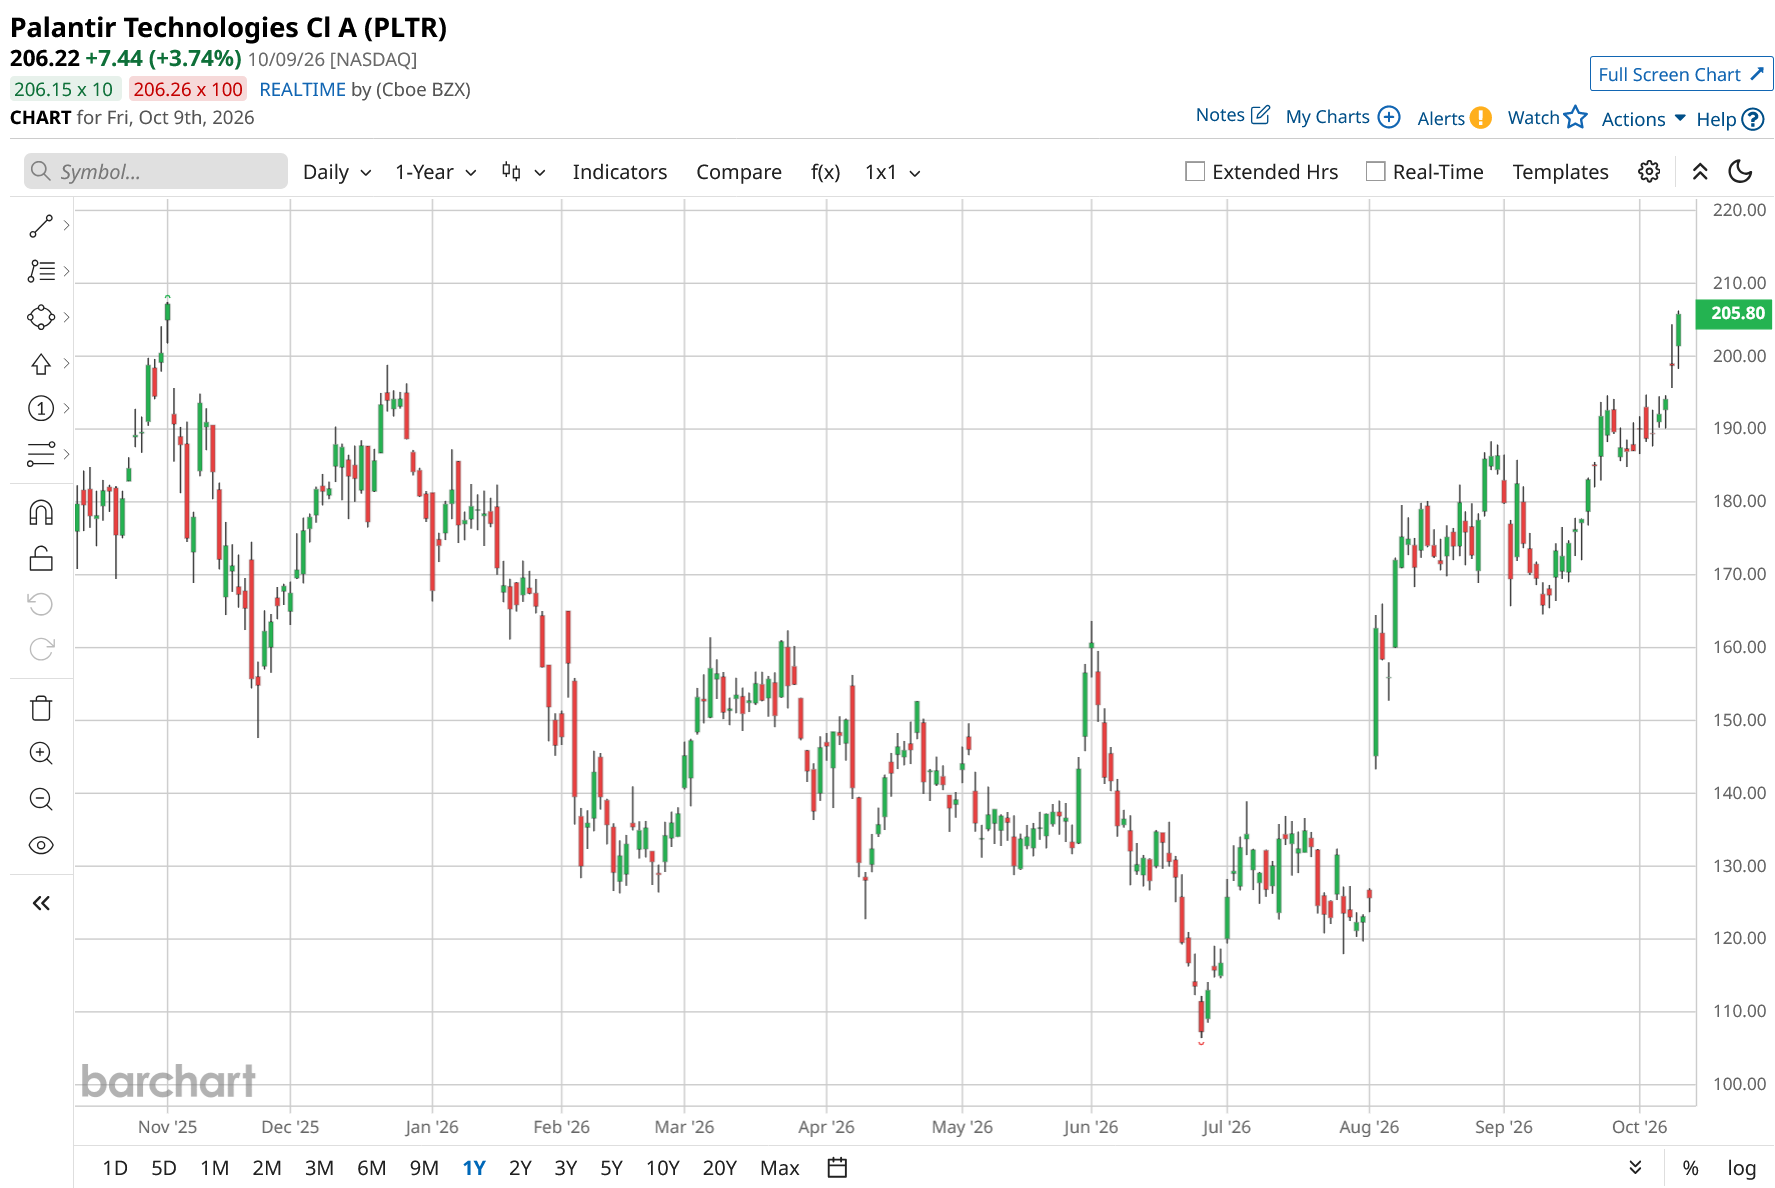
Palantir Surpasses Q2 Earnings
Palantir reported its Q2 FY2026 results on Aug. 3, benefiting from accelerating commercial adoption of AI that lifted revenue, strengthened profitability, and prompted a significant upward revision to its full-year outlook. The market responded immediately, with shares surging 29.5% in the following trading session.
Revenue jumped 92.8% year-over-year (YoY) to $1.94 billion, marking Palantir’s strongest reported revenue growth rate to date. The figure also comfortably exceeded market expectations and surpassed analyst estimates of $1.81 billion.
The U.S. business led the expansion, with revenue rising 115% YoY to $1.57 billion. Within that total, U.S. commercial revenue soared 149% to $764 million, highlighting the increasing traction of Palantir’s Artificial Intelligence Platform (AIP) among businesses seeking to incorporate AI into everyday operations.
U.S. government revenue increased 90% from the prior year’s period, demonstrating continued strength in Palantir’s public-sector operations. Meanwhile, U.S. commercial total contract value bookings reached $2.13 billion, up 153% YoY.
Profitability also delivered a strong showing. Net income attributable to common stockholders reached $1.1 billion, rising 225% from the year-ago value. Adjusted EPS came in at $0.41, comfortably ahead of Wall Street’s forecast of $0.35. Moreover, adjusted free cash flow climbed 115% YoY to $1.22 billion, representing a robust 63% margin.
Management has responded by raising its FY2026 revenue guidance to $8.15 billion–$8.16 billion, implying YoY growth of 82%. The company also lifted its U.S. commercial revenue guidance to above $3.424 billion, representing a growth rate of at least 134%.
Furthermore, adjusted income from operations is projected at $4.89 billion–$4.90 billion, while adjusted free cash flow guidance stands at $4.5 billion–$4.7 billion.
On the other hand, analysts project Q3 FY2026 EPS to increase 88.9% YoY to $0.34. For full-year FY2026, expectations call for EPS to rise 103.2% YoY to $1.28, followed by another 43.8% increase to $1.84 in FY2027.
What Do Analysts Expect for PLTR Stock?
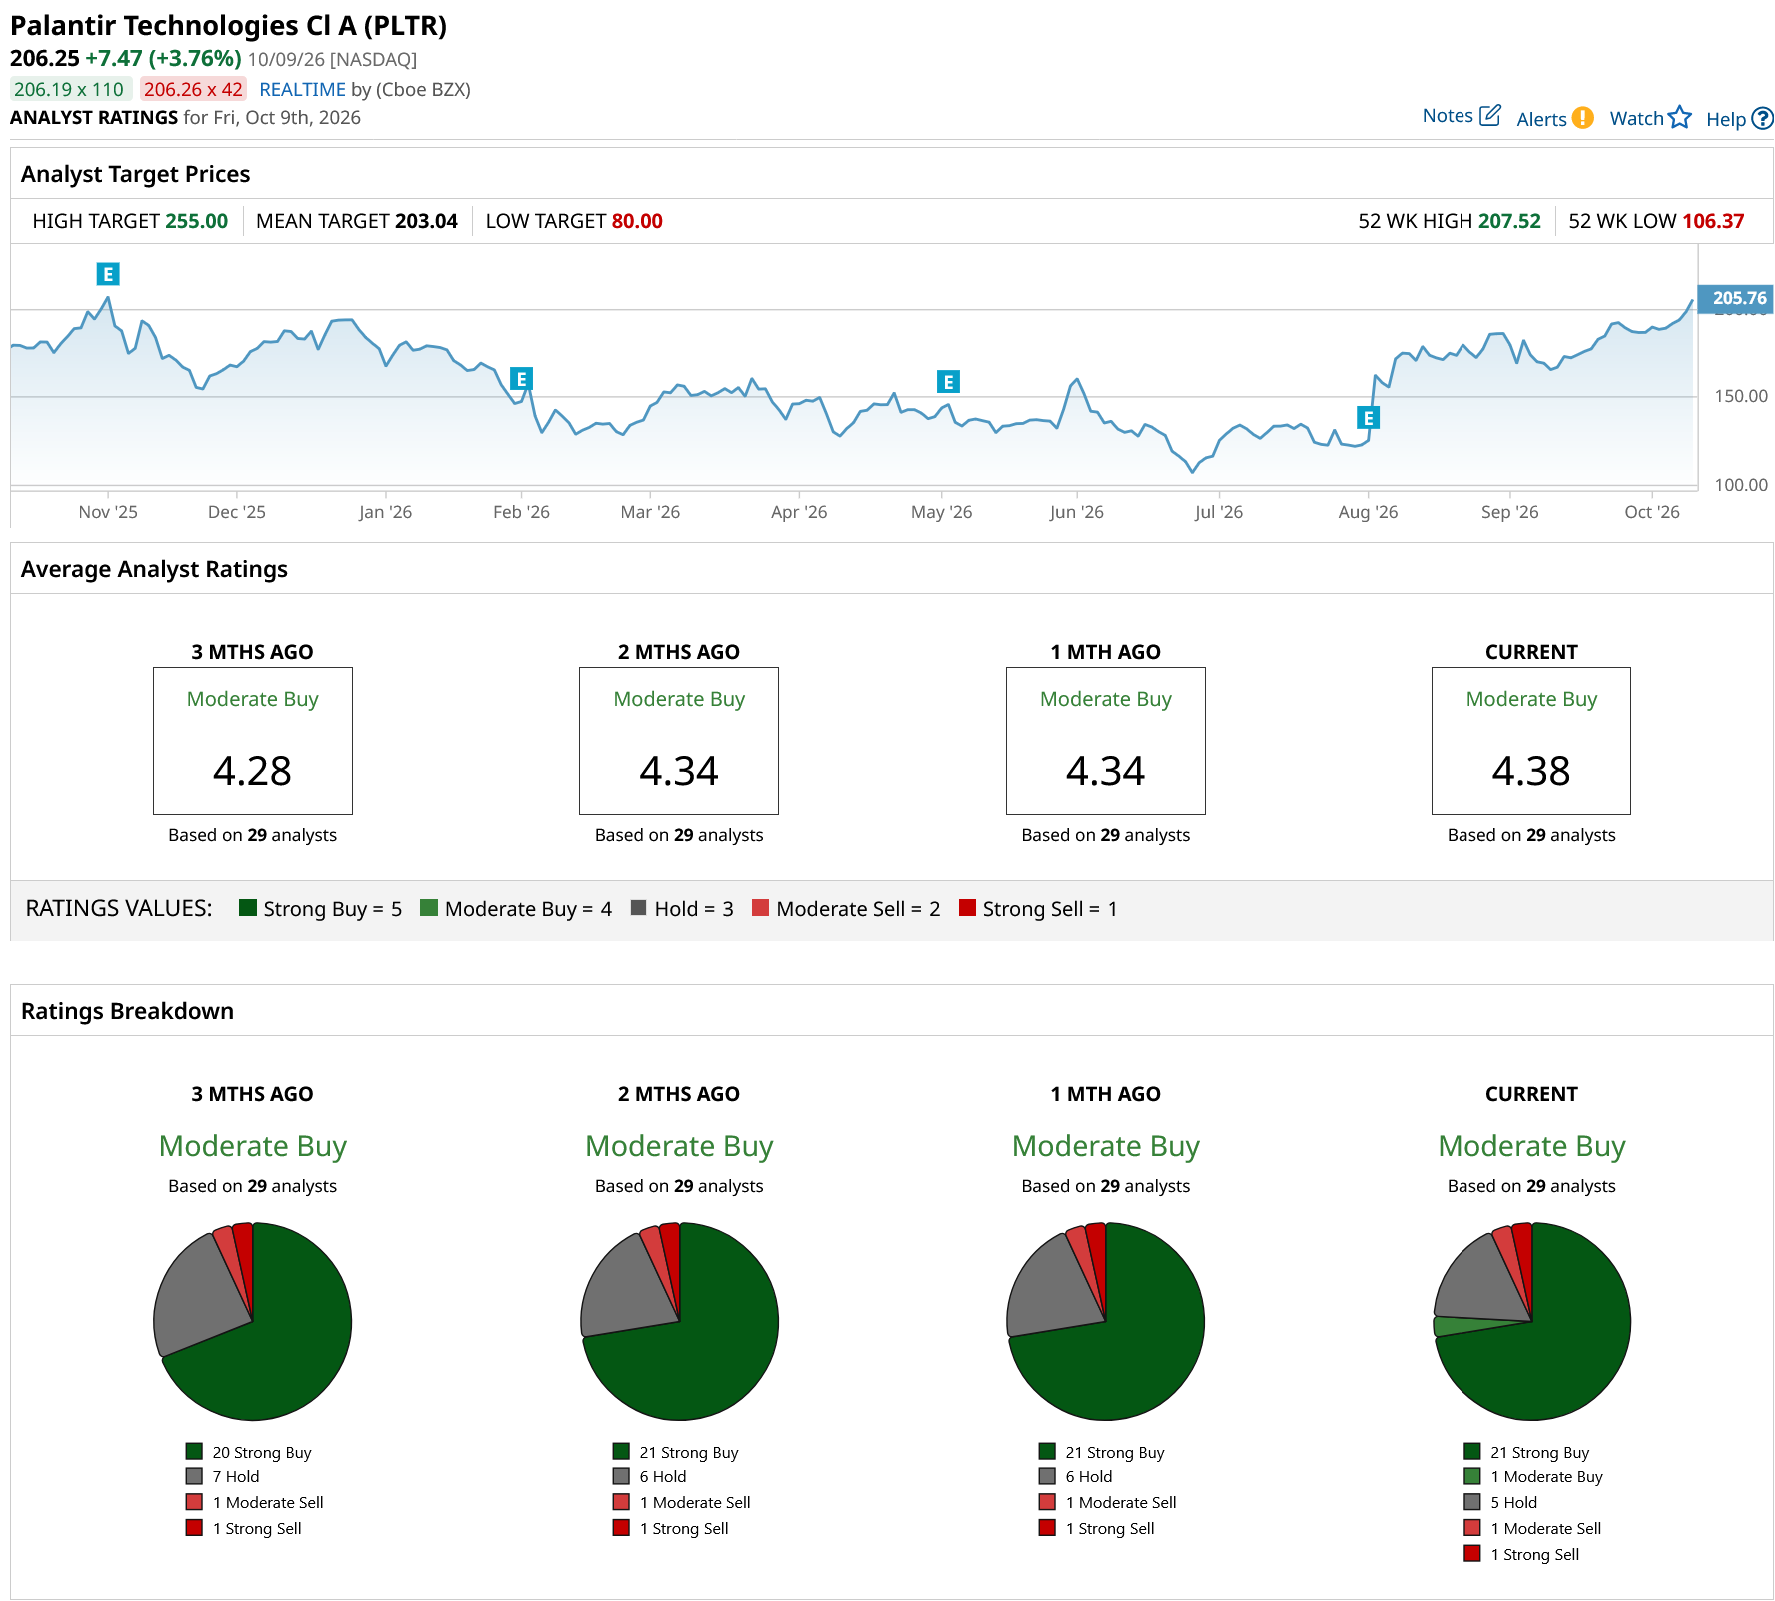
Wall Street’s overall rating on PLTR is “Moderate Buy,” reflecting a broadly positive outlook alongside some reservations about the stock. Of the 29 analysts covering the company, 21 recommend a “Strong Buy,” one assigns a “Moderate Buy,” five recommend “Hold,” one gives a “Moderate Sell,” and one recommends a “Strong Sell.”
Price targets tell a similarly optimistic story. The average price target of $203.04, which the stock is already trading just slightly above. Meanwhile, the Street-high target of $255 points to a gain of 26% from current levels.
On the date of publication, Aanchal Sugandh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.