
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AMETEK (AME), Why Is Attention Building Again?
Fresh attention on AMETEK (AME) follows renewed commentary around its consistent earnings surprises, positive Zacks Rank, and long-term revenue and free cash flow trends that together are shaping how investors frame the stock today.
Short-term trading in AMETEK has cooled a little, with the 1-day share price return down 0.44% and the 7-day share price return down 0.63%. However, the 30-day and year-to-date share price returns of 4.11% and 18.35% point to momentum that has been building rather than fading.
Scan beyond AMETEK and evaluate other industrials showing strong price and earnings momentum with our curated list of 27 high quality undervalued stocks.
The recent gain in AMETEK appears tied to solid revenue and earnings execution, not just a mood swing in the market. Does the current price still fairly reflect that performance, or has it already stretched beyond it?
Most Popular Narrative: 11% Undervalued
Analysts following AMETEK see a fair value of about $278 per share. This is above the last close of $247.52 and supports a narrative focused on secular demand in AI, defense, aerospace and energy infrastructure.
Growing exposure to AI driven semiconductor and data center infrastructure, supported by strong orders and design wins in optics, metrology, embedded computing and power simulation, is expected to support multi-year revenue growth and earnings from these higher value instrumentation and electronics platforms.
See why 17 investors see AMETEK as 11% undervalued.
Result: Fair Value of $278.33 (UNDERVALUED)
Still, this upbeat AMETEK story depends on two swing factors: market appetite for a premium P/E multiple and successful integration of acquisitions like Indicor.
Find out about the key risks to this AMETEK narrative.
Another View: AMETEK Through The P/E Lens
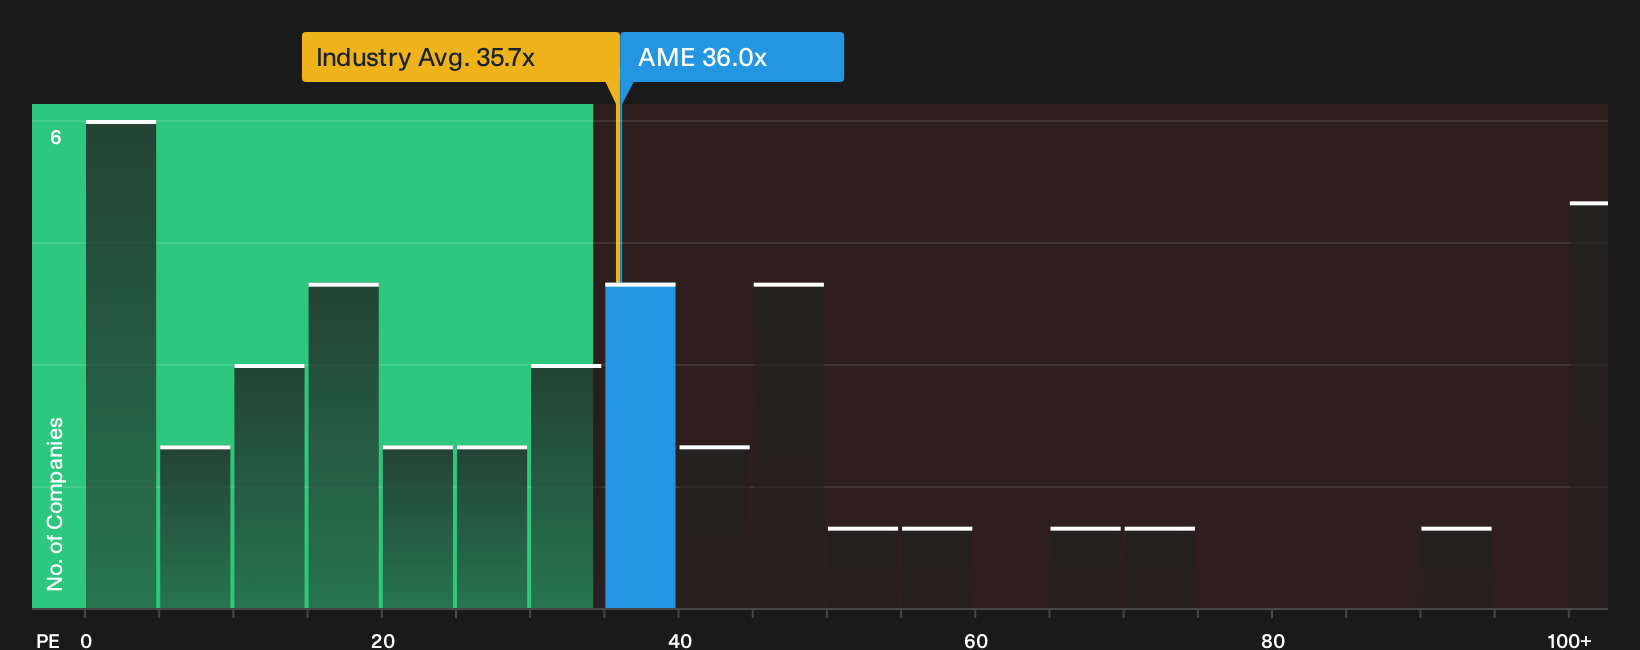
The analyst fair value of $278.33 paints AMETEK as 11.1% undervalued, yet the current P/E of 36x tells a tougher story. That multiple sits above the estimated fair ratio of 26.2x and slightly ahead of the US Electrical industry on 35.7x, although below peers at 39.2x. In plain terms, you are paying a premium that could compress if sentiment cools. How comfortable are you with that valuation risk?
To stress test your view on the price you are paying for AMETEK today against the earnings profile analysts expect, take a closer look at the detailed valuation breakdown in our numbers focused review, See what the numbers say about this price — find out in our valuation breakdown.
For a visual check on how AMETEK stacks up against its sector on earnings multiples, see
Next Steps
Feeling optimistic after looking at AMETEK, or a bit cautious about the premium multiple and execution risk? Move fast, review the underlying drivers, and pressure test the upside story yourself by digging into the 2 key rewards.
Looking for more investment ideas beyond AMETEK?
If AMETEK has sharpened your focus, do not stop here. Broaden your watchlist with a few targeted screens that surface very different types of opportunities.
- Target dependable income and focus on businesses built to support ongoing payouts through the 8 dividend fortresses.
- Hunt for mispriced quality and use the 27 high quality undervalued stocks to spot stocks where fundamentals and valuation appear out of sync.
- Prioritize resilience and filter for companies with stronger financial footing using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com