
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Broader Midwest Dental Distribution Change Dentsply Sirona Stock Narrative
- DENTSPLY SIRONA announced in early October 2026 that Midwest Dental Equipment & Supply will begin distributing its digital technology portfolio across the United States, expanding a relationship that had previously centered on consumables.
- This broader Midwest Dental agreement, the seventh dealer enhancement in North America during 2026, reflects a concerted push to widen access to DENTSPLY SIRONA’s connected digital dentistry solutions through established sales and service channels.
- This development raises the question of how DENTSPLY SIRONA's investment narrative aligns with deeper Midwest Dental distribution for its connected digital technology portfolio.
DENTSPLY SIRONA Investment Narrative Recap
To own DENTSPLY SIRONA, you need to believe the connected technology strategy can eventually offset weak recent sales trends, management turnover and earlier missteps that led to goodwill impairments and sizeable losses. The Midwest Dental expansion fits that thesis by pushing DS Core and imaging tools through more local reps and technicians where dentists already buy.
The key near term swing factor is whether digital dentistry platforms and field support translate into steadier order patterns in elective categories that management has described as soft. The biggest risk remains persistent top line pressure, cost inflation from tariffs and execution issues around a relatively new leadership team.
The recent Wellspect Surity Medicare coverage announcement sits in the background here. It shows another part of the group working on access and reimbursement, this time for urinary management devices rather than dental equipment. For an investor, it reflects DENTSPLY SIRONA attempting to widen usage of its broader healthcare portfolio.
That matters because catalysts are not only about chairside scanners and mills. Progress in Wellspect could support cash generation and help offset volatility in higher margin but more discretionary implant and CAD/CAM categories. The risk is that complexity across four segments and multiple product families makes consistent execution tougher, particularly with newer management and board turnover.
DENTSPLY SIRONA's current earnings are a loss of $628.0 million, with analysts expecting earnings of $189.7 million by 2029 on forecast revenue of $3.8 billion. This implies fairly flat annual revenue trends and an earnings swing of about $818 million from today's loss to that 2029 consensus figure.
Uncover why DENTSPLY SIRONA's fair value indicates a 54% potential upside to its current price, which could narrow quickly.
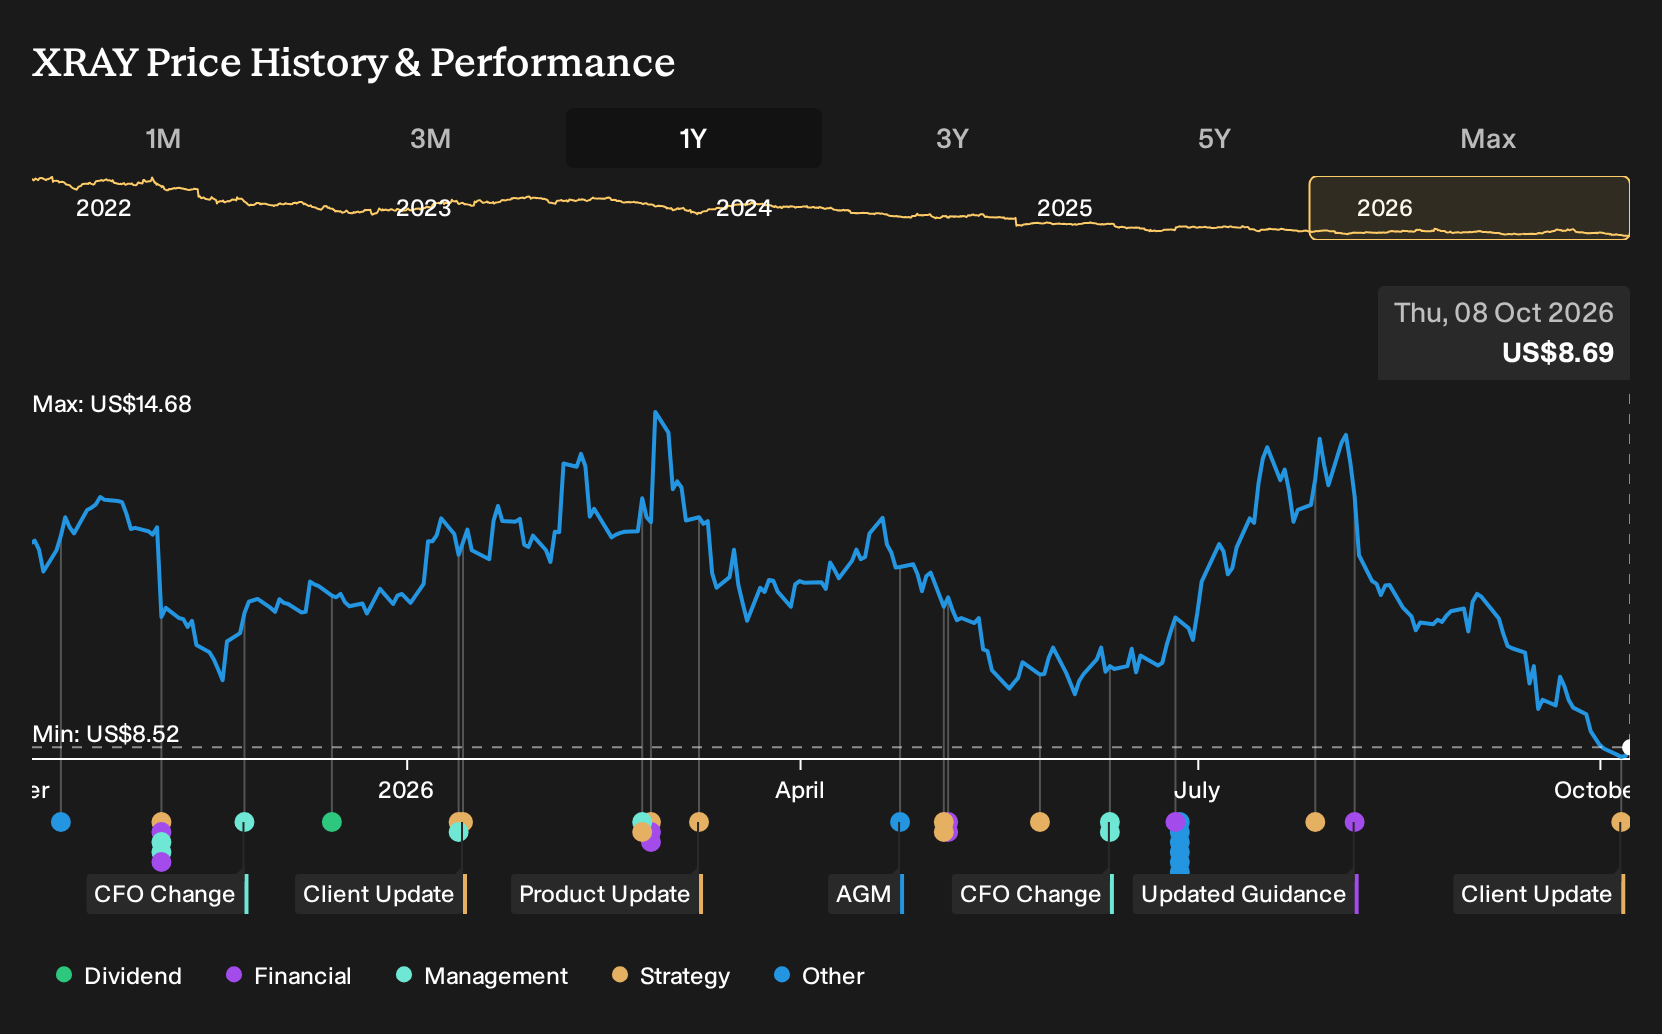
Exploring Other Perspectives
One alternate angle on DENTSPLY SIRONA focuses on AI and digital adoption. The most optimistic analysts, before this Midwest Dental news, were estimating revenue of about $3.9b and earnings of roughly $373.4 million by 2029. This can be interpreted as a view that broader distribution could reshape these forecasts if execution accelerates.
Explore 2 other DENTSPLY SIRONA fair value estimates, including one that suggests potential upside of up to 424% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your DENTSPLY SIRONA research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for DENTSPLY SIRONA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DENTSPLY SIRONA's overall financial health at a glance.
Looking for more investment ideas beyond DENTSPLY SIRONA?
If the DENTSPLY SIRONA story has sparked fresh questions about where to put new capital to work, it can help to line it up against a wider watchlist of opportunities that share some of the same qualities you care about, whether that is quality, balance sheet strength or steadier risk profiles.
- For investors who want low volatility and fewer negative surprises, start with a focused group of 31 resilient stocks with low risk scores that may offer a calmer ride through different market conditions.
- If you care most about financial resilience and funding flexibility, compare DENTSPLY SIRONA with a curated list of solid balance sheet and fundamentals (25 results) to see how its leverage and liquidity stack up.
- Those hunting for mispriced quality can broaden their watchlist using a targeted 27 high quality undervalued stocks that filters for fundamentals first and valuation second.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com