
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Industry Tailwinds Will Impact Global Partners Stock Investors
- Sector commentary in early October 2026 highlighted Global Partners as a key beneficiary of the oil and gas refining and marketing MLP industry, citing its integrated network of retail sites and terminals and its focus on acquisitions and market expansion as important supports for its underlying operations.
- The same industry review pointed to the role of diversified business models, fee-based contracts, and long-term growth projects in supporting cash-flow stability for Global Partners, which matters for how investors think about the durability of its fuel distribution and retail earnings base.
- We will now examine how the investment narrative for Global Partners could be influenced by this industry tailwind related to its integrated terminal and retail network.
Scan beyond Global Partners and spot other fuel distributors and energy marketers that may benefit from similar industry support by reviewing the hand picked list of solid balance sheet and fundamentals (25 results) today.
Global Partners Investment Narrative Recap
To own Global Partners, you need to be comfortable with a fuel heavy model that leans on an integrated terminal and gas station footprint, plus fee based and long term contracts that can smooth cash generation even when volumes or margins wobble. The recent Zacks industry view mostly reinforces that backdrop and does not materially alter the near term picture.
The key short term swing factor is how effectively Global Partners keeps throughput and retail volumes flowing through that network while managing interest costs and debt, given earnings forecasts that imply some pressure. The biggest risk remains long term exposure to fossil fuel demand and the possibility that large physical assets see weaker utilization over time.
With no fresh company specific announcements tied directly to this Zacks industry call, the most relevant context is the earlier focus on Global Partners expanding its terminal network through acquisitions and trimming weaker retail locations. Those moves aim to concentrate activity in markets where the integrated model and fee based arrangements can support steadier throughput.
For you as a shareholder, the operational question is whether that ongoing portfolio reshaping and prior refinancing work can keep revenue growth, which analysts currently project at 19.7% a year, translating into acceptable earnings and coverage of interest costs. Execution on acquisitions, divestments and cost control sits right next to fossil fuel volume risk on the watch list.
Global Partners' current analyst narrative points to revenues of $42.5b and earnings of $168.5m by 2029, based on 30.1% yearly revenue growth and an earnings increase of about $45.9m from $122.6m today.
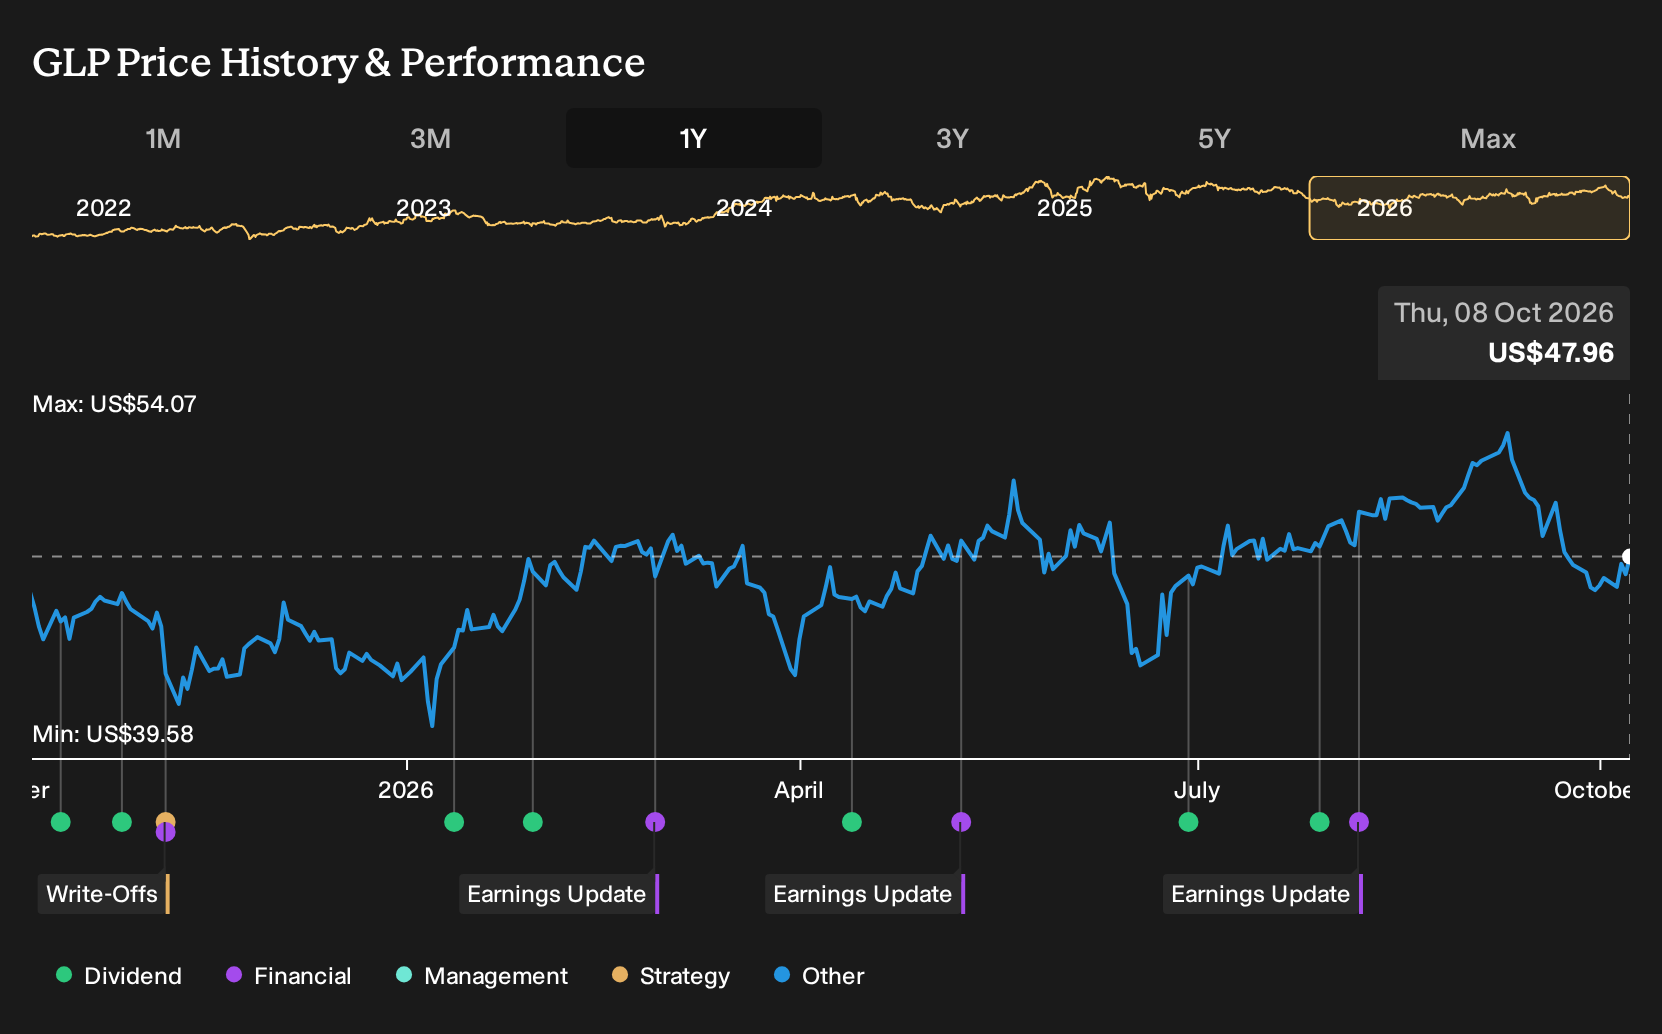
Uncover how Global Partners' fair value indicates a 5% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$45.5 to about US$109 per unit, which is a wide gap for Global Partners. That split view sits beside long term risks from energy transition and regulation, while recent terminal acquisitions could still shape how future cash flows justify any chosen entry point. Explore those differing opinions.
Explore another Global Partners fair value estimate, including one that indicates the potential for as much as 5% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Global Partners research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Global Partners. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Global Partners' overall financial health at a glance.
Looking For More Investment Ideas Beyond Global Partners?
Once you have a view on Global Partners, it can help to cross check that thesis against other opportunities that share some of the same strengths or offer a different mix of risk and reward. The Simply Wall St Screener lets you filter for traits that matter to you, whether that is balance sheet resilience, income potential, or overlooked businesses with solid fundamentals.
- If capital preservation sits high on your list, you can narrow your focus to companies with resilient finances and robust fundamentals through the 31 resilient stocks with low risk scores.
- If you care about income stability, you can compare Global Partners with a broader group of high yielding payers by reviewing the 8 dividend fortresses.
- If you want to search for underappreciated opportunities, you can cast a wider net across quality businesses that are not on every radar yet using the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com