
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Williams Companies (WMB) Met Q2 Estimates, Is It Still Below Fair Value?
Williams Companies (WMB) recently reported Q2 FY26 results that matched earnings expectations, putting fresh attention on how this large US natural gas infrastructure operator earns its money and manages its pipeline network.
Recent trading has been choppy for Williams Companies. The share price is up 1.23% over one day and 4.51% over the past week, yet down 4.60% over 30 days and 3.57% over 90 days. At the same time, the year-to-date share price return of 18.88% and 1-year total shareholder return of 18.13% indicate momentum that has cooled in the short term but remains solid over a longer window.
Scan the midstream space by comparing Williams Companies with a hand-picked 43 power grid technology and infrastructure stocks that could benefit from the same demand for reliable energy infrastructure.
That combination of a cooled near-term chart and strong multi-year gains raises a practical question for Williams Companies investors: Is most of the rerating already in the rearview mirror, or does the current valuation still leave room ahead?
Most Popular Narrative: 15% Undervalued
Williams Companies last closed at $72.34, compared with a widely followed fair value estimate of $85.61 that applies a 7.24% discount rate. That gap rests on a story built around Haynesville gas, Gulf Coast LNG routes, and a growing power platform sitting on long-term contracts.
The Power Innovation platform, backed by a US$5.34b equity funding commitment from partners, is supporting a series of behind the meter projects such as Socrates and Neo that carry multi year contracts, which can add incremental contracted earnings and improve overall returns on invested capital.
The commercialization of Neo, a 682 MW behind the meter power project with a 12.5 year contract and an expected build multiple of about 5x, together with continued phases of Socrates, provides Williams Companies with a growing base of long duration power cash flows that can support EBITDA growth beyond the traditional pipeline business.
See why 28 investors see Williams Companies as 15% undervalued.
Result: Fair Value of $85.61 (UNDERVALUED)
Still, the Williams Companies story can be knocked off course if permitting setbacks slow key pipelines, or if higher leverage around 4.1x constrains future funding.
Find out about the key risks to this Williams Companies narrative.
Another Take On Williams Companies Valuation
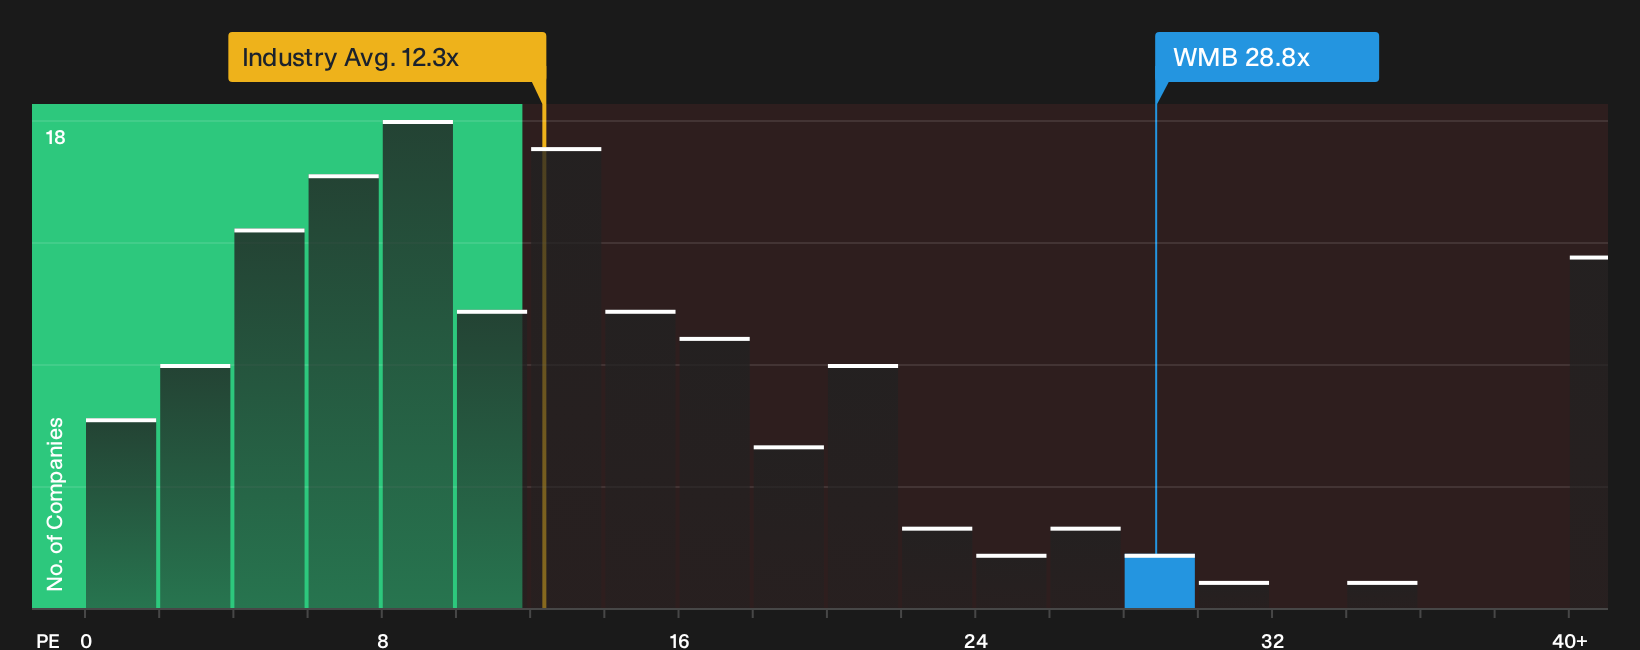
The first narrative argues Williams Companies looks about 15% undervalued. A simple P/E check tells a different story. The stock trades around 28.8x earnings, compared with 12.3x for the wider US Oil and Gas group and a fair ratio estimate of 23.7x for Williams Companies. That richer multiple can mean investors are already paying up for the story, which raises the question of how much safety margin is really left.
To see how that P/E gap has been framed into a full valuation view, including what the fair ratio could move toward over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Williams Companies valuation and sentiment are one thing, but your judgment is what matters, and it is worth forming it now by weighing both sides of the story and digging into the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond Williams Companies?
Do not stop with Williams Companies. Fresh opportunities keep surfacing, and the investors who scan widely now often spot compelling setups before they get crowded.
- Target steady compounding by reviewing companies that combine resilient business models with 31 resilient stocks with low risk scores built to handle tougher conditions.
- Go after value by checking out a curated pool of quality businesses trading below their estimated worth through the 27 high quality undervalued stocks.
- Focus on resilience and financial strength by using a list of solid balance sheet and fundamentals (25 results) that many investors overlook until confidence has already returned.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com