
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CarGurus (CARG) Launches VINMax On A Narrative That Says It Looks Undervalued
CarGurus (CARG) just rolled out VINMax, an AI-driven tool that uses real-time shopper demand data to automatically promote specific vehicle listings on and off its marketplace, aiming to improve dealer marketing efficiency.
CarGurus shares trade at US$29.24 after a 1-day share price return of 1.63%, yet the stock is still down 22.34% on a year-to-date share price basis, with a 1-year total shareholder return that declined 13.97% but a 3-year total shareholder return that increased 65.67%. This suggests recent weakness contrasts with stronger multi year momentum as investors weigh products like VINMax against shifting sentiment.
Compare how CarGurus’ AI-led approach stacks up against other platforms by scanning a curated group of 35 profitable AI stocks that aren't just burning cash.
So is CarGurus, after a sharp year to date pullback and a fresh AI product in VINMax, better approached as an early entry today or as a patience test while you wait for a cheaper valuation window next?
Most Popular Narrative: 30% Undervalued
CarGurus is framed as undervalued in the most followed narrative, with a fair value of $41.50 against the recent $29.24 close. This view puts a lot of weight on how efficiently software like VINMax and the broader marketplace can convert usage into long term earnings power.
Sharpened focus on high-margin technology and scalable offerings, combined with winding down volatile operations, is driving improved profitability, operational efficiency, and marketplace differentiation. Strategic wind-down of low-margin, volatile wholesale transaction operations (CarOffer), with renewed focus on proprietary technology, analytics, and sourcing intelligence, is expected to improve overall net margins and sharpen operational focus on high-performing, scalable business lines.
See why 17 investors see CarGurus as 30% undervalued.
Result: Fair Value of $41.50 (UNDERVALUED)
Still, the CarGurus narrative can unravel if rising digital rivals pressure dealer budgets, or if regulatory shifts around data and marketing push costs higher.
Find out about the key risks to this CarGurus narrative.
Another View on CarGurus Valuation
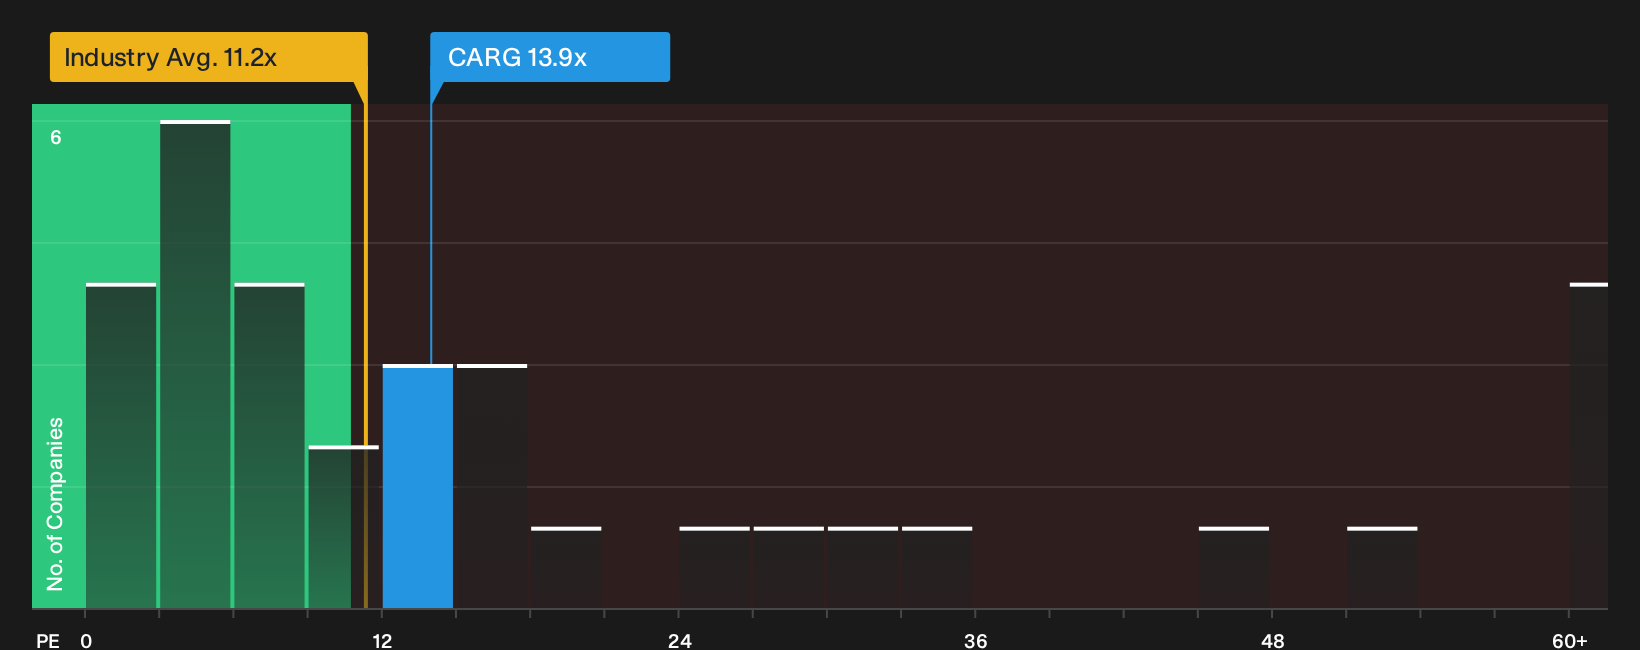
On earnings multiples, CarGurus looks less clear cut. The stock trades on a P/E of 13.9x, above the US Interactive Media and Services average of 10.8x, yet below an estimated fair ratio of 20.1x. That gap points to both upside potential and the risk that expectations are already generous. Which side do you think is mispriced here?
For a closer look at how this pricing compares with peers and where the fair ratio might influence the valuation over time, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on CarGurus can be confusing, so move quickly and pull apart the numbers, sentiment and valuation drivers for yourself with 3 key rewards and 2 important warning signs.
Looking for more CarGurus-sized investment ideas?
If CarGurus has sharpened your focus on valuation and quality, do not stop here. Broader research gives you more control and helps you stay prepared for the next move.
- Target potential mispricings by scanning a focused set of 27 high quality undervalued stocks that pair solid fundamentals with discounted market expectations.
- Prioritise resilience and sleep-at-night holdings by reviewing a curated 31 resilient stocks with low risk scores that aims to limit downside while still offering meaningful upside potential.
- Spot future leaders before the crowd by working through a 20 high quality undiscovered gems that highlights strong financial profiles the wider market may be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com