
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Promising Growth Companies With Insider Ownership Up To 21%
Over the last 7 days, the United States market has risen by 1.2%, contributing to a 13% increase over the past year, with earnings projected to grow by 18% annually in the coming years. In this environment, identifying growth companies with significant insider ownership can be promising as it often indicates strong confidence from those closest to the business in its future potential.
Top 10 Growth Companies With High Insider Ownership In The United States
| Name | Insider Ownership | Earnings Growth |
| Upstart Holdings (UPST) | 14.0% | 68.4% |
| Standard Nuclear (STDN) | 18.8% | 64.2% |
| Sable Offshore (SOC) | 11.2% | 76% |
| Precigen (PGEN) | 11.7% | 54% |
| Nu Holdings (NU) | 22.8% | 22.3% |
| Karman Holdings (KRMN) | 13.6% | 56.4% |
| Himax Technologies (HIMX) | 29.1% | 70.2% |
| Figure Technology Solutions (FIGR) | 21.4% | 32.4% |
| Dave (DAVE) | 16.6% | 24.1% |
| Almonty Industries (ALM) | 10.8% | 57.0% |
We'll examine a selection from our screener results.
Atour Lifestyle Holdings (ATAT)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Atour Lifestyle Holdings Limited, with a market cap of approximately $4.39 billion, develops lifestyle brands in the People's Republic of China through its subsidiaries.
Operations: Atour Lifestyle Holdings Limited generates revenue primarily through its Atour Group segment, which reported CN¥11.72 billion.
Insider Ownership: 18.6%
Atour Lifestyle Holdings demonstrates strong growth potential, with earnings forecasted to increase at 17.8% annually, surpassing the US market average. Despite trading at 55.6% below its estimated fair value, recent revenue guidance indicates a robust 30% year-over-year increase for fiscal 2026. The company reported significant revenue and net income growth for the first half of 2026 compared to the previous year, highlighting its capacity for continued expansion amidst high insider ownership levels.
- Navigate through the intricacies of Atour Lifestyle Holdings with our comprehensive analyst estimates report here.
- Upon reviewing our latest valuation report, Atour Lifestyle Holdings' share price might be too pessimistic.
Ethos Technologies (LIFE)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Ethos Technologies Inc. operates as a third-party administrator for insurance policies in the United States with a market cap of $2.23 billion.
Operations: The company's revenue is primarily derived from its insurance broker services, totaling $586.53 million.
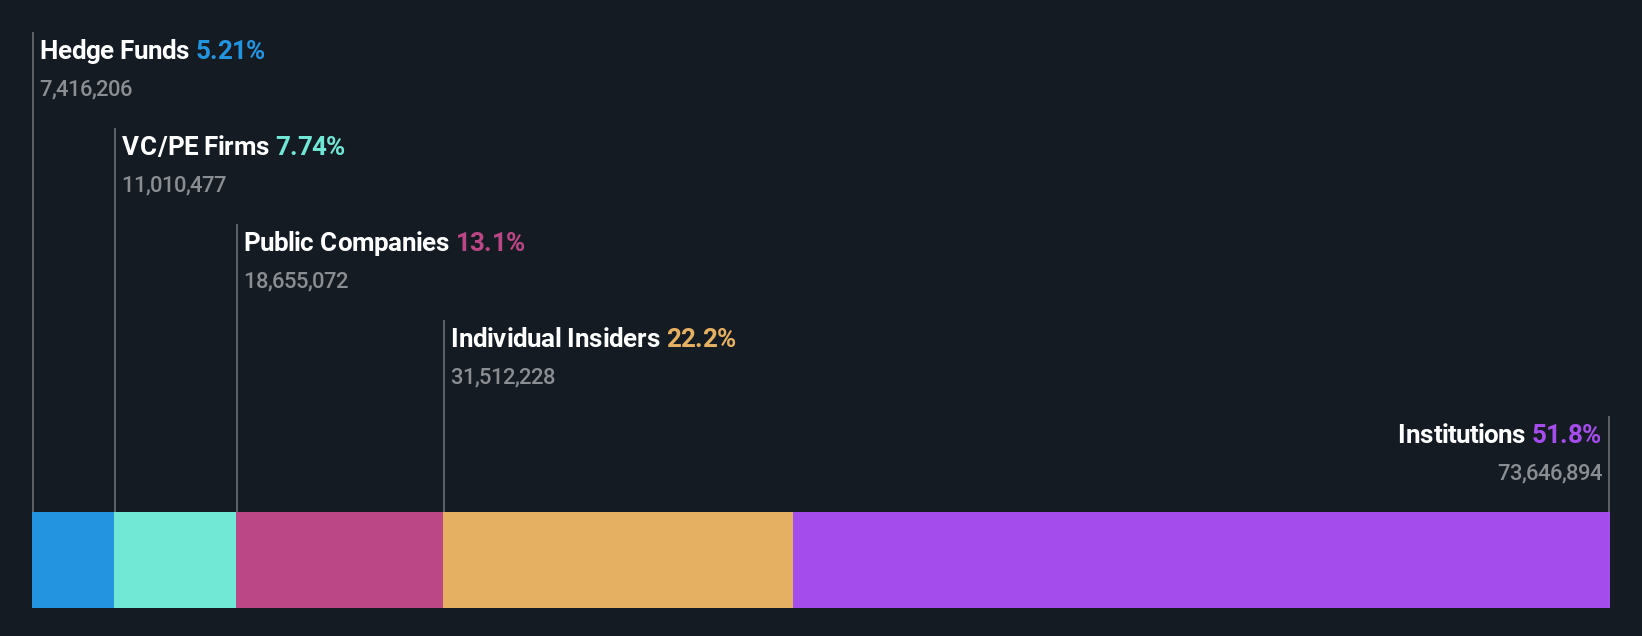
Insider Ownership: 21.6%
Ethos Technologies shows potential for growth, with revenue increasing by 83.2% over the past year and forecasts indicating a 25.6% annual growth rate, outpacing the US market average. Despite volatile share prices and significant insider selling recently, the company plans to repurchase up to US$100 million of its stock, reflecting confidence in future prospects. However, profitability remains a challenge as it reported a net loss for the first half of 2026 despite substantial revenue gains.
- Delve into the full analysis future growth report here for a deeper understanding of Ethos Technologies.
- Insights from our recent valuation report point to the potential overvaluation of Ethos Technologies shares in the market.

MasTec (MTZ)
Simply Wall St Growth Rating: ★★★★★☆
Overview: MasTec, Inc. is an infrastructure engineering and construction company offering services in engineering, building, installation, maintenance, and upgrades for communications, energy, utility, and other infrastructure sectors mainly in the United States and Canada with a market cap of approximately $17.71 billion.
Operations: The company's revenue segments include Communications at $3.51 billion, Power Delivery at $4.52 billion, Pipeline Infrastructure at $2.57 billion, and Clean Energy and Infrastructure at $5.60 billion.
Insider Ownership: 20.7%
MasTec's earnings are forecast to grow significantly at 26.52% annually, surpassing the US market average. The company's recent addition to the FTSE All-World Index highlights its expanding influence. Despite high debt levels, MasTec trades below estimated fair value, indicating potential for appreciation. Recent financial results show strong growth with a 23% revenue increase year-over-year and improved net income. However, no substantial insider trading activity has been reported in the past three months.
- Click to explore a detailed breakdown of our findings in MasTec's earnings growth report.
- Our valuation report here indicates MasTec may be undervalued.

Key Takeaways
- Discover the full array of 186 Fast Growing US Companies With High Insider Ownership right here.
- Searching for a Fresh Perspective? We've found 7 US stocks that are forecast to pay a dividend yeild of over 6% next year. See the full list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com