
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Deere (DE) Could Be 5% Undervalued As Probe And Yamaha Deal Reframe Value
Deere (DE) is back in focus after U.S. regulators opened a broad inquiry into agricultural equipment practices, a move that coincides with the company’s new Side by Side vehicle collaboration with Yamaha Motor.
Recent headlines have been a tug of war for sentiment around Deere, with the regulatory probe weighing on the share price in the short term, while the new Yamaha partnership adds a fresh growth angle to the story. The stock is down over the past month, yet the roughly 40% year to date share price return and 1 year total shareholder return of about 45% signal that longer term momentum has been strong despite this latest bout of scrutiny.
Spot similar agriculture and equipment stories under pressure and with potential breakout by scanning the 27 high quality undervalued stocks that filters for quality businesses with strong fundamentals.After a sharp run and a fresh pullback on the regulator news, Deere now sits at a crossroads. Is most of the share price gain already baked in, or does the valuation still leave meaningful room?
Most Popular Narrative: 5% Undervalued
On Simply Wall St’s most followed narrative, Deere’s fair value of $688.44 sits modestly above the latest $652.58 close, which keeps the focus on how its core businesses and new projects earn their way into that gap.
Continued growth in Deere’s Construction & Forestry segment, with 2026 net sales guided to be up about 20% and order books largely full into fiscal 2027, supports the idea of a second earnings engine alongside agriculture and points to a broader revenue mix and more stable consolidated earnings as infrastructure, data center and energy related demand flows through future periods.
See why 119 investors see Deere as 5% undervalued.
Result: Fair Value of $688.44 (UNDERVALUED)
Still, Deere’s narrative can be knocked off course if elevated tariff costs continue to squeeze margins, or if large agriculture demand stays cyclically weak for longer.
Find out about the key risks to this Deere narrative.
Another View: What Deere’s P/E Is Telling You
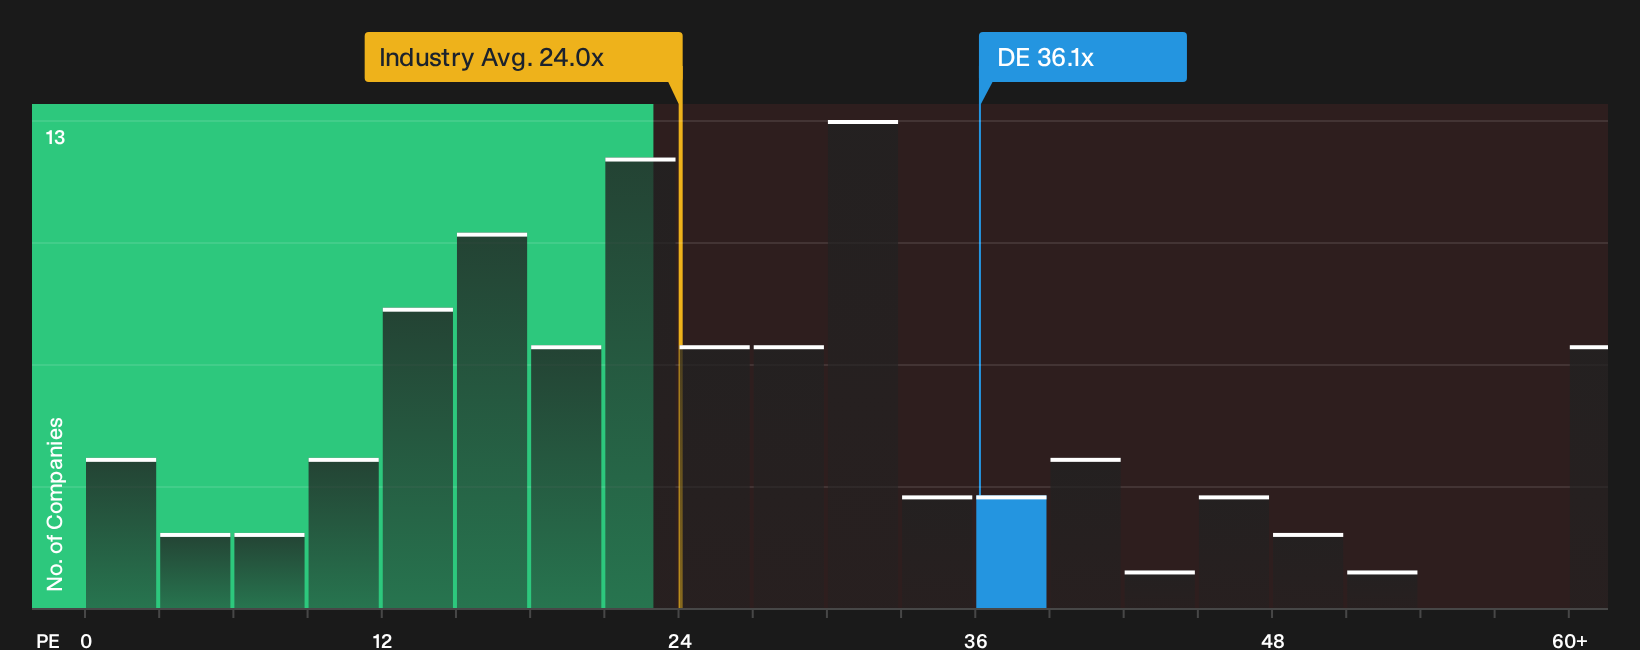
On price ratios, Deere looks less forgiving. The shares trade on a P/E of 36.1x, which is richer than both the US Machinery industry at 24x and the peer average of 30.1x, and only slightly below a fair ratio of 37.5x that the market could move toward over time.
That mix of a discounted cash flow signal pointing to value and a relatively heavy earnings multiple raises a practical question for investors. Is this a case of paying up early for future earnings quality, or is it better to look for similar exposure where the P/E gap to industry and peers is narrower? See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about how the Deere story reads so far, with both pressure points and bright spots in play. Move quickly, review the same figures, and weigh up the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Deere?
If Deere has sharpened your focus, do not stop here. Fresh ideas often come from comparing leaders with overlooked peers that share similar quality traits.
- Target resilient compounding potential by scanning a 31 resilient stocks with low risk scores that filters for businesses with sturdier risk profiles.
- Hunt for mispriced quality and benchmark Deere against a 27 high quality undervalued stocks that highlights companies with solid fundamentals trading below estimated worth.
- Spot promising up-and-comers before they gain wider attention by reviewing a 20 high quality undiscovered gems built around strong balance sheets and consistent financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com