
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Rising Broadband Competition Altering The Investment Case For Comcast Stock (CMCSA)?
- Recent announcements highlight Comcast working with Harmonic on Recon fiber monitoring, deploying fiber sensing for real time threat detection, and expanding broadband coverage through public private build outs in Florida and Pennsylvania.
- These projects show Comcast relying on network intelligence, edge compute and partnerships to manage service quality and support broadband and streaming demand, even as competitive pressure on its cable footprint intensifies.
- We will now look at how Comcast's investment narrative may be shaped by this focus on network intelligence and fiber monitoring.
Scan Comcast's push into smarter broadband and streaming, then size up other infrastructure driven opportunities with the hand picked 91 AI infrastructure stocks.
Comcast Investment Narrative Recap
To own Comcast, you need to believe its connectivity, streaming and parks portfolio can keep generating solid cash flows even as broadband competition squeezes pricing and subscriber trends. The key short term swing factor is whether broadband and wireless bundles plus Peacock engagement can offset pressure from fiber, fixed wireless and weaker Experiences demand.
The biggest risk right now is further erosion in broadband economics, which would weigh on revenue, EBITDA and returns on Comcast's large network base. The recent fiber monitoring and sensing news looks helpful for service quality and uptime, but on its own does not materially change that core risk reward equation yet.
The Harmonic Recon collaboration is the most relevant recent announcement for you to watch. Comcast is putting its XMFR fiber monitoring technology into a commercial platform that continuously checks line performance and pinpoints faults, using Harmonic's cOS SensAI to validate fixes and detect issues more proactively.
If execution goes to plan, this type of network intelligence could support key catalysts such as DOCSIS 4.0 upgrades, converged broadband and mobile bundles, and more reliable Peacock streaming, especially during big sports peaks. It may also help Comcast manage rising cyber and physical infrastructure risks. However, competition from low cost fiber and fixed wireless remains a separate structural challenge.
Comcast's narrative projects US$120.6b revenue and US$11.4b earnings by 2029. This implies a 1.2% yearly revenue decline and an earnings increase of about US$0.2b from US$11.2b today.
Uncover why Comcast's fair value indicates a 36% potential upside to its current price that could close sooner than you expect.
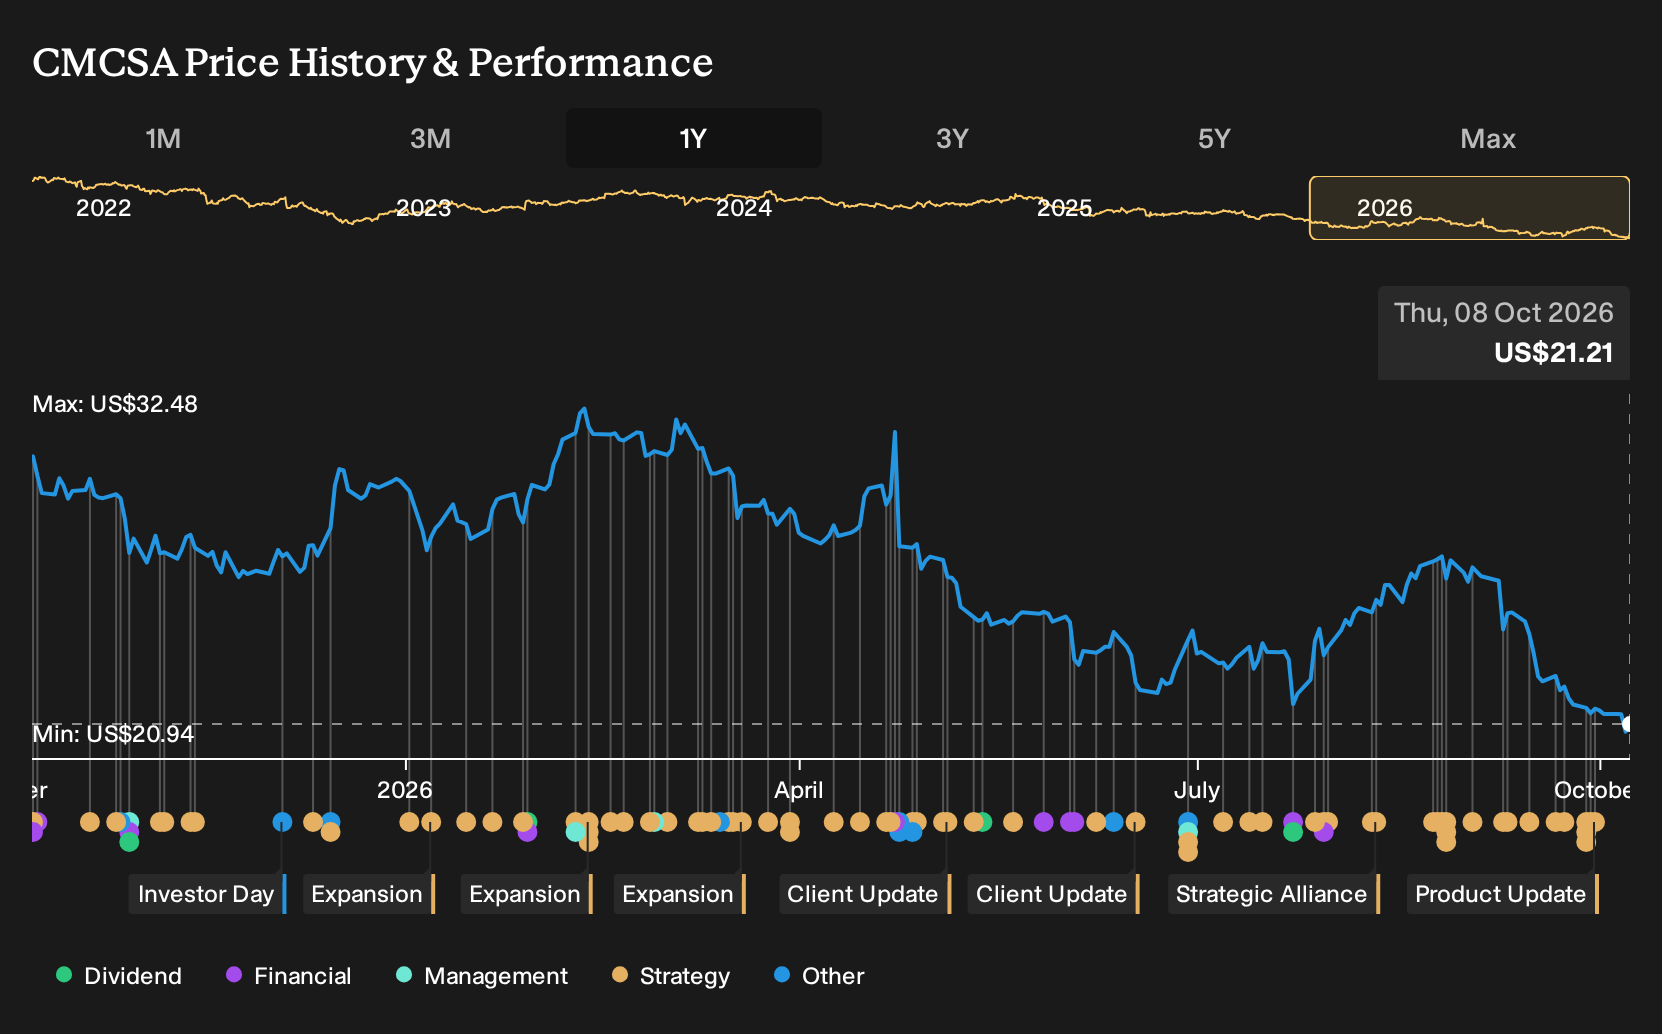
Exploring Other Perspectives
The bearish narrative views Comcast’s rural and small market build outs as the key swing factor. The lowest ranked analysts were penciling in revenue of about US$116.7b and earnings of US$9.8b by 2029, with shrinking margins, before this fiber intelligence news. That outlook is far more cautious. Use it as a reminder to compare several narratives for yourself.
Explore 5 other Comcast fair value estimates, including one that suggests up to 15% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Comcast research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Comcast. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Comcast's overall financial health at a glance.
Looking for more investment ideas beyond Comcast?
Once you have a view on Comcast, it helps to compare it with other businesses that match different risk and return profiles using the Simply Wall St Screener.
- If you want a margin of safety, start with financially strong candidates that keep debt and funding risk in check through the list of solid balance sheet and fundamentals (25 results).
- For those more focused on potential mispricing, scan companies where quality and valuation line up using the 27 high quality undervalued stocks.
- Income focused investors who care about steady payouts can shortlist higher yielding options via the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com