
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
European Stocks Estimated To Be Trading Below Fair Value In October 2026
As European markets navigate volatility driven by elevated oil prices and rising bond yields, investors are increasingly focused on inflation pressures and their impact on monetary policy. In this environment, identifying stocks that are trading below their fair value can offer opportunities for those looking to capitalize on potential market inefficiencies.
Top 10 Undervalued Stocks Based On Cash Flows In Europe
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| PORR (WBAG:POS) | €31.25 | €60.51 | 48.4% |
| Orthex Oyj (HLSE:ORTHEX) | €4.50 | €8.90 | 49.4% |
| MBB (XTRA:MBB) | €168.20 | €311.07 | 45.9% |
| Koninklijke BAM Groep (ENXTAM:BAMNB) | €11.67 | €22.73 | 48.7% |
| ING Groep (ENXTAM:INGA) | €29.425 | €58.51 | 49.7% |
| Infotel (ENXTPA:INF) | €37.20 | €68.20 | 45.5% |
| Huuuge (WSE:HUG) | PLN23.40 | PLN45.71 | 48.8% |
| Grupa Pracuj (WSE:GPP) | PLN55.50 | PLN108.64 | 48.9% |
| DWS Group GmbH KGaA (XTRA:DWS) | €66.00 | €127.68 | 48.3% |
| Apator (WSE:APT) | PLN25.60 | PLN49.19 | 48% |
We'll examine a selection from our screener results.
FLSmidth (CPSE:FLS)
Overview: FLSmidth & Co. A/S offers flowsheet technology and service solutions for the mining industry across various global regions, with a market cap of DKK29.10 billion.
Operations: The company generates revenue from three main segments: Product (DKK3.06 billion), Service (DKK8.65 billion), and Pumps, Cyclones & Valves (PC&V) (DKK3.05 billion).
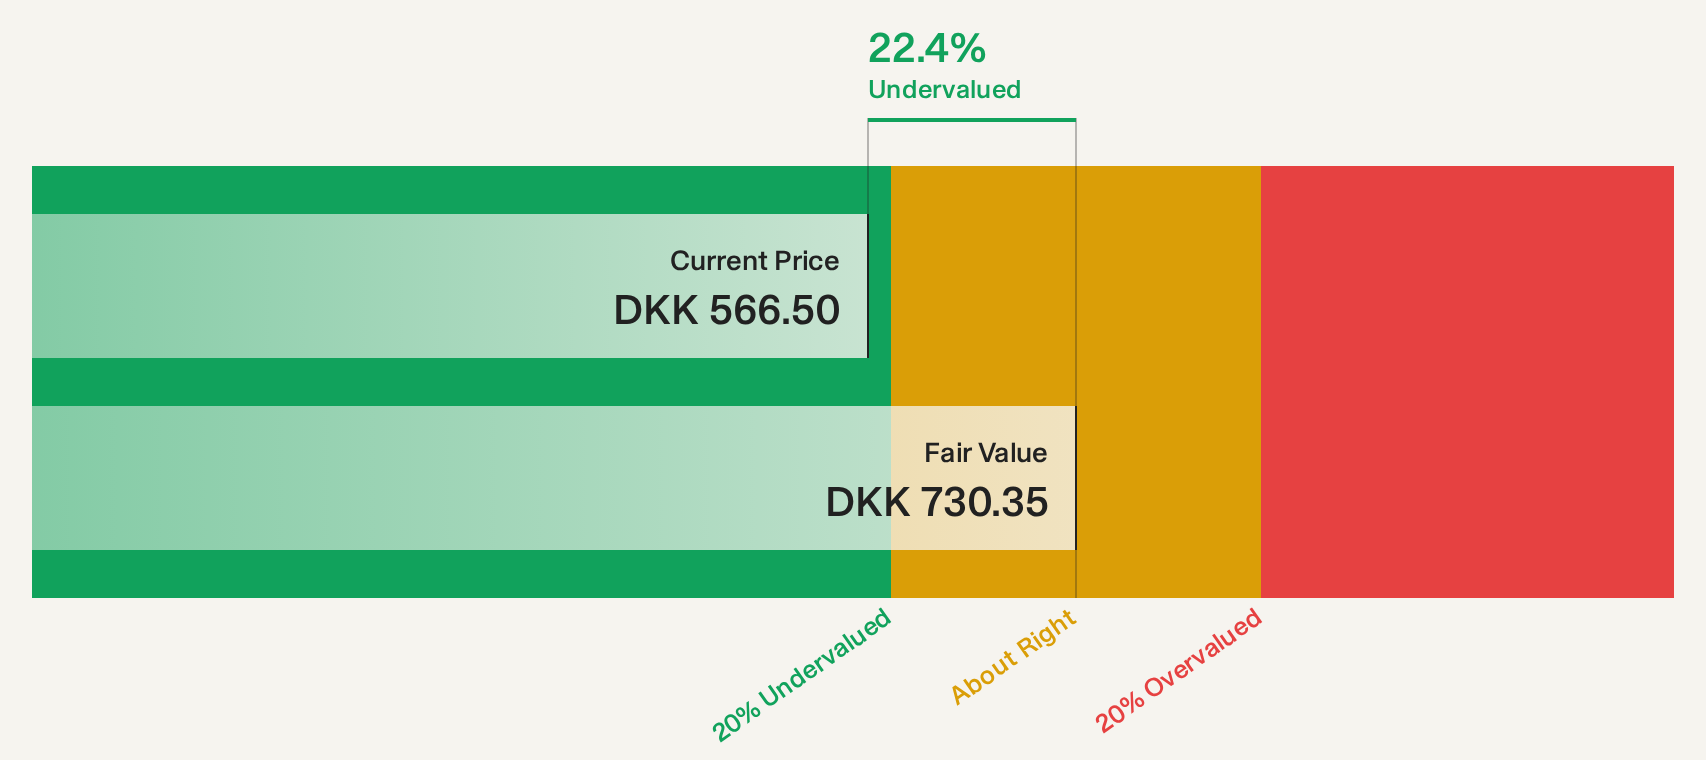
Estimated Discount To Fair Value: 25%
FLSmidth is trading at 25% below its estimated fair value and is undervalued based on discounted cash flow, with a current price of DKK546.5 compared to a future cash flow estimate of DKK728.6. Despite earnings forecasted to grow at 5.08% annually, slower than the Danish market's 6.8%, revenue growth outpaces the market at 7.1%. Recent strategic expansions, including a new business line and lifecycle agreements in India, aim to bolster long-term growth and operational efficiency.
- According our earnings growth report, there's an indication that FLSmidth might be ready to expand.
- Dive into the specifics of FLSmidth here with our thorough financial health report.
Ackermans & Van Haaren (ENXTBR:ACKB)
Overview: Ackermans & Van Haaren NV operates in marine engineering and contracting, private banking, real estate, energy and resources, and growth capital sectors globally with a market cap of €8.45 billion.
Operations: The company's revenue is primarily derived from marine engineering and contracting (€5.34 billion), private banking (€422.26 million), real estate (€99.96 million), and growth capital businesses (€100.47 million).
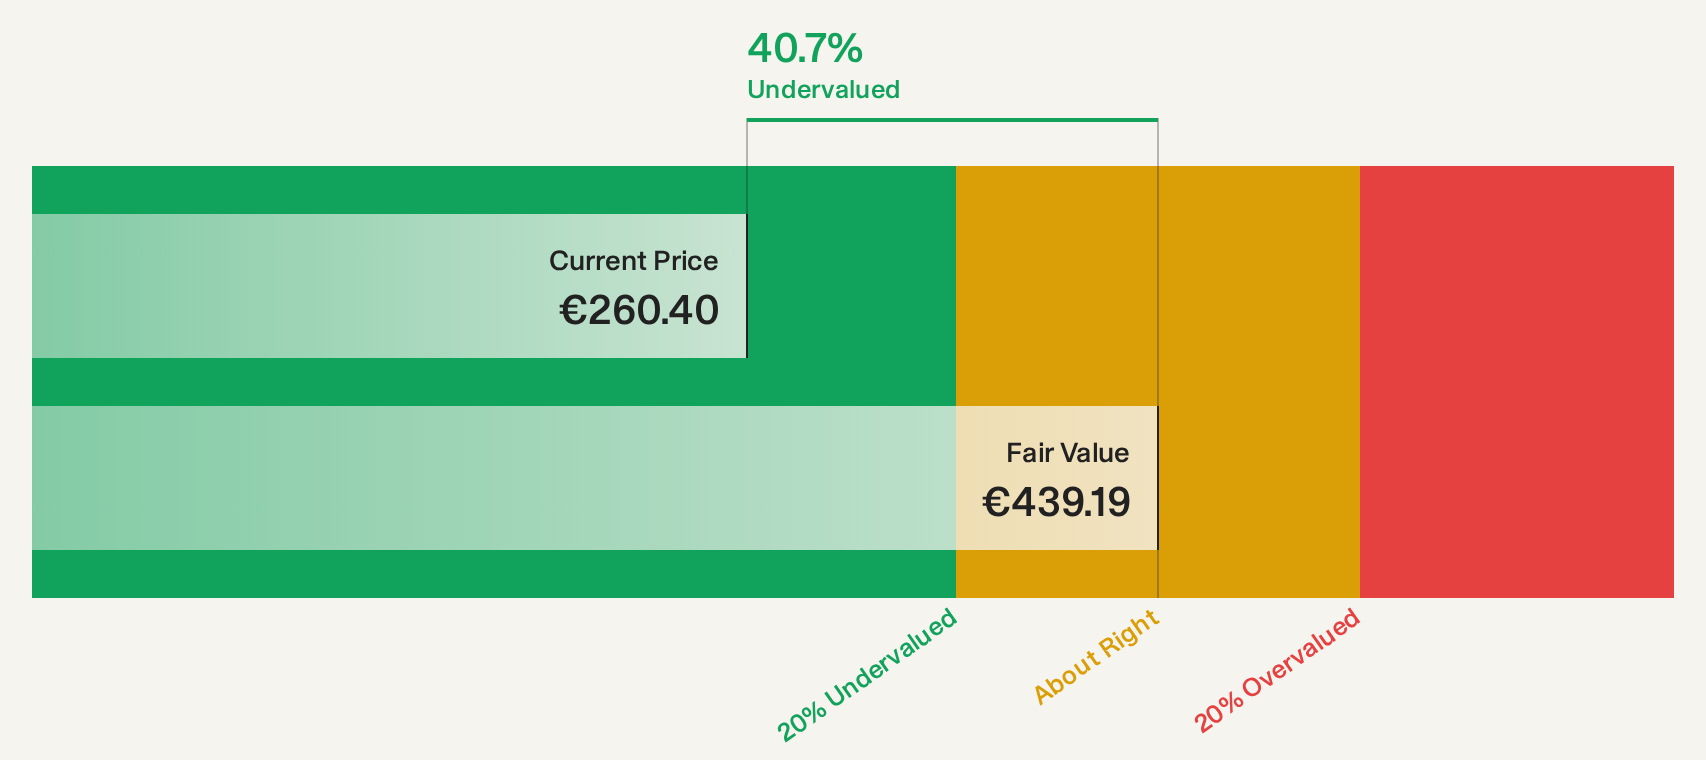
Estimated Discount To Fair Value: 40.9%
Ackermans & Van Haaren is trading at €258.6, significantly below its estimated future cash flow value of €437.9, indicating substantial undervaluation based on discounted cash flow analysis. Despite a robust 23.7% profit growth over the past year and expected net profit increase for 2026, earnings and revenue growth forecasts remain modest compared to the Belgian market averages. Analysts agree on a potential price rise of 22.1%, but return on equity is forecasted to be low at 8.5%.
- Our comprehensive growth report raises the possibility that Ackermans & Van Haaren is poised for substantial financial growth.
- Click to explore a detailed breakdown of our findings in Ackermans & Van Haaren's balance sheet health report.
Kalmar Oyj (HLSE:KALMAR)
Overview: Kalmar Oyj specializes in providing heavy material handling equipment and services across various regions including the Americas, Europe, Asia, the Middle East, and Africa, with a market capitalization of €2.36 billion.
Operations: Kalmar Oyj's revenue is primarily derived from two segments: €618.60 million from services and €1.20 billion from equipment sales.
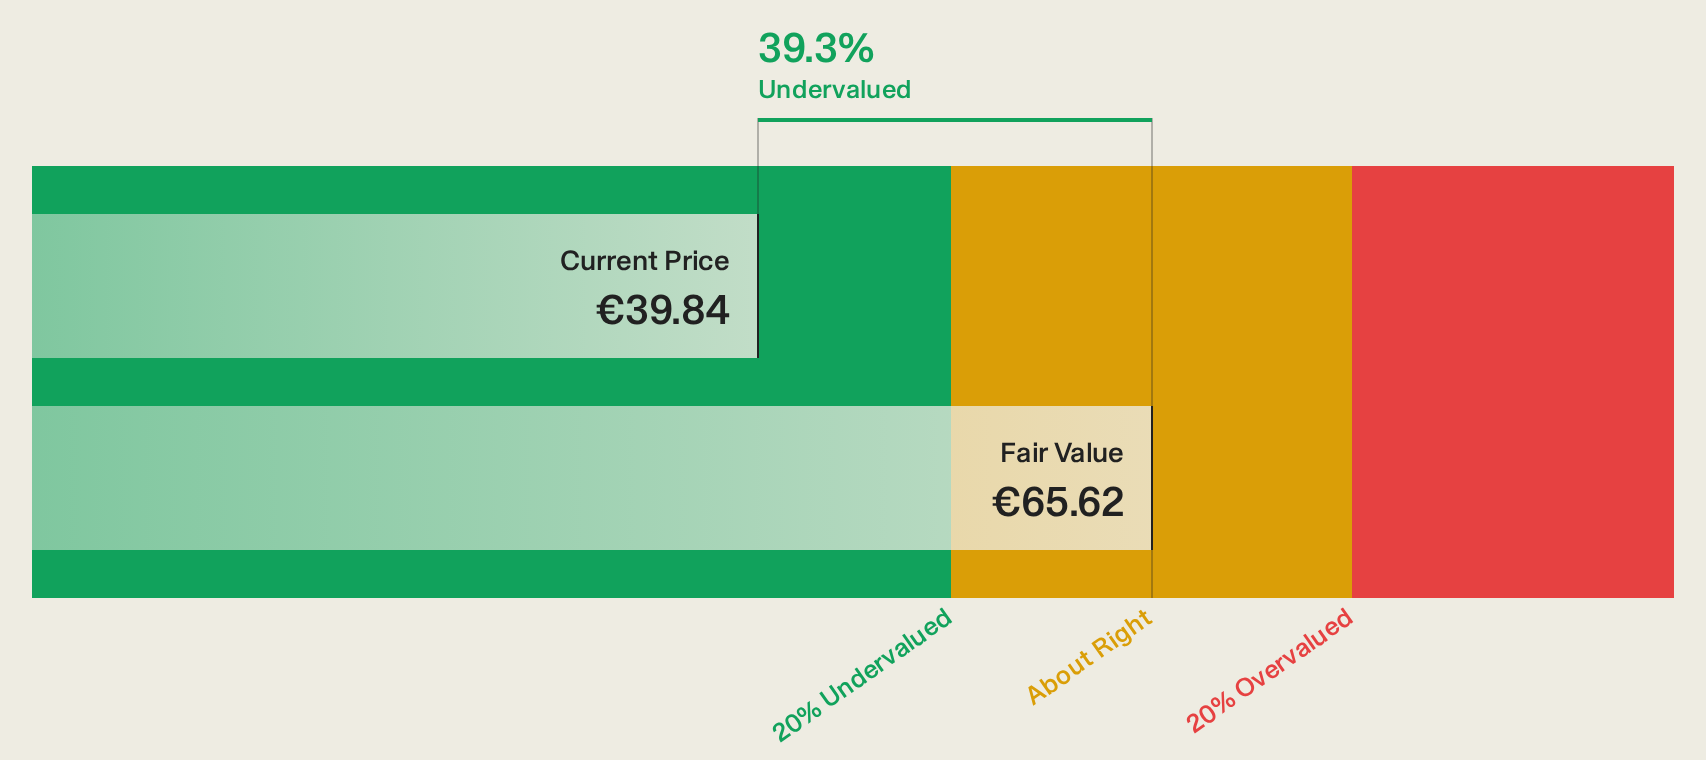
Estimated Discount To Fair Value: 42.2%
Kalmar Oyj is trading at €36.96, significantly below its estimated future cash flow value of €63.89, highlighting substantial undervaluation. Despite a 27% profit growth last year, its forecasted earnings and revenue growth rates of 9.18% and 4.5% per annum are slower than Finnish market averages. Recent strategic moves include a reorganization to enhance efficiency and new service contracts in Sweden and Spain, supporting its long-term cash flow potential amidst moderate growth expectations.
- The growth report we've compiled suggests that Kalmar Oyj's future prospects could be on the up.
- Unlock comprehensive insights into our analysis of Kalmar Oyj stock in this financial health report.
Summing It All Up
- Click through to start exploring the rest of the 58 Undervalued European Stocks Based On Cash Flows now.
- Invested in any of these stocks? Simplify your portfolio management with Simply Wall St and stay ahead with our alerts for any critical updates on your stocks.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com