
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Japanese Financial Stocks Built For Higher JGB Yields
Japan is quietly rewiring its public finances, with spending reviews, subsidy cuts and multi decade high JGB yields all pulling money in new directions. That shift can punish companies hooked on easy support, yet it can also reward businesses built to live with higher long term rates and tighter budgets. This article walks through three Japanese banks and insurers from our screener that are closely tied to this policy reset.
The three Japanese financial stocks highlighted below are only a first pass. The full screen surfaced 18 more banks and insurers with equally compelling narratives that are not unpacked in this article. To identify and analyze the higher conviction ideas that match your own risk and income goals, head straight into the Japanese Banks and Insurers (Beneficiaries of Rising JGB Yields and Fiscal Discipline) screener.
Tokio Marine Holdings (TSE:8766)
Overview: Tokio Marine Holdings is a global insurer that sells non-life and life insurance and related financial services, anchored by large bond investments.
Operations: Tokio Marine generates most revenue from Overseas Insurance Business at ¥5,408.0b, Domestic Property and Casualty Insurance at ¥3,162.7b, plus smaller domestic life and solutions units.
Market Cap: ¥14,765.8b
Tokio Marine Holdings sits squarely in the insurance side of this screener, where a large bond portfolio can turn firmer long term JGB yields into steadier investment income and support for its Japan and overseas insurance franchises.
"The Re-New initiative in their Japan P&C business aims to achieve sustainable profit growth by increasing premiums and enhancing insurance solution offerings, potentially improving underwriting profits and net margins."
What really matters now is how one quiet shift in its capital playbook ultimately feeds through to those margins investors watch so closely.
Those capital shifts sit at the center of the story, and the full narrative for Tokio Marine Holdings shows how Tokio Marine Holdings could turn them into accelerating underwriting power and re-rated income resilience.

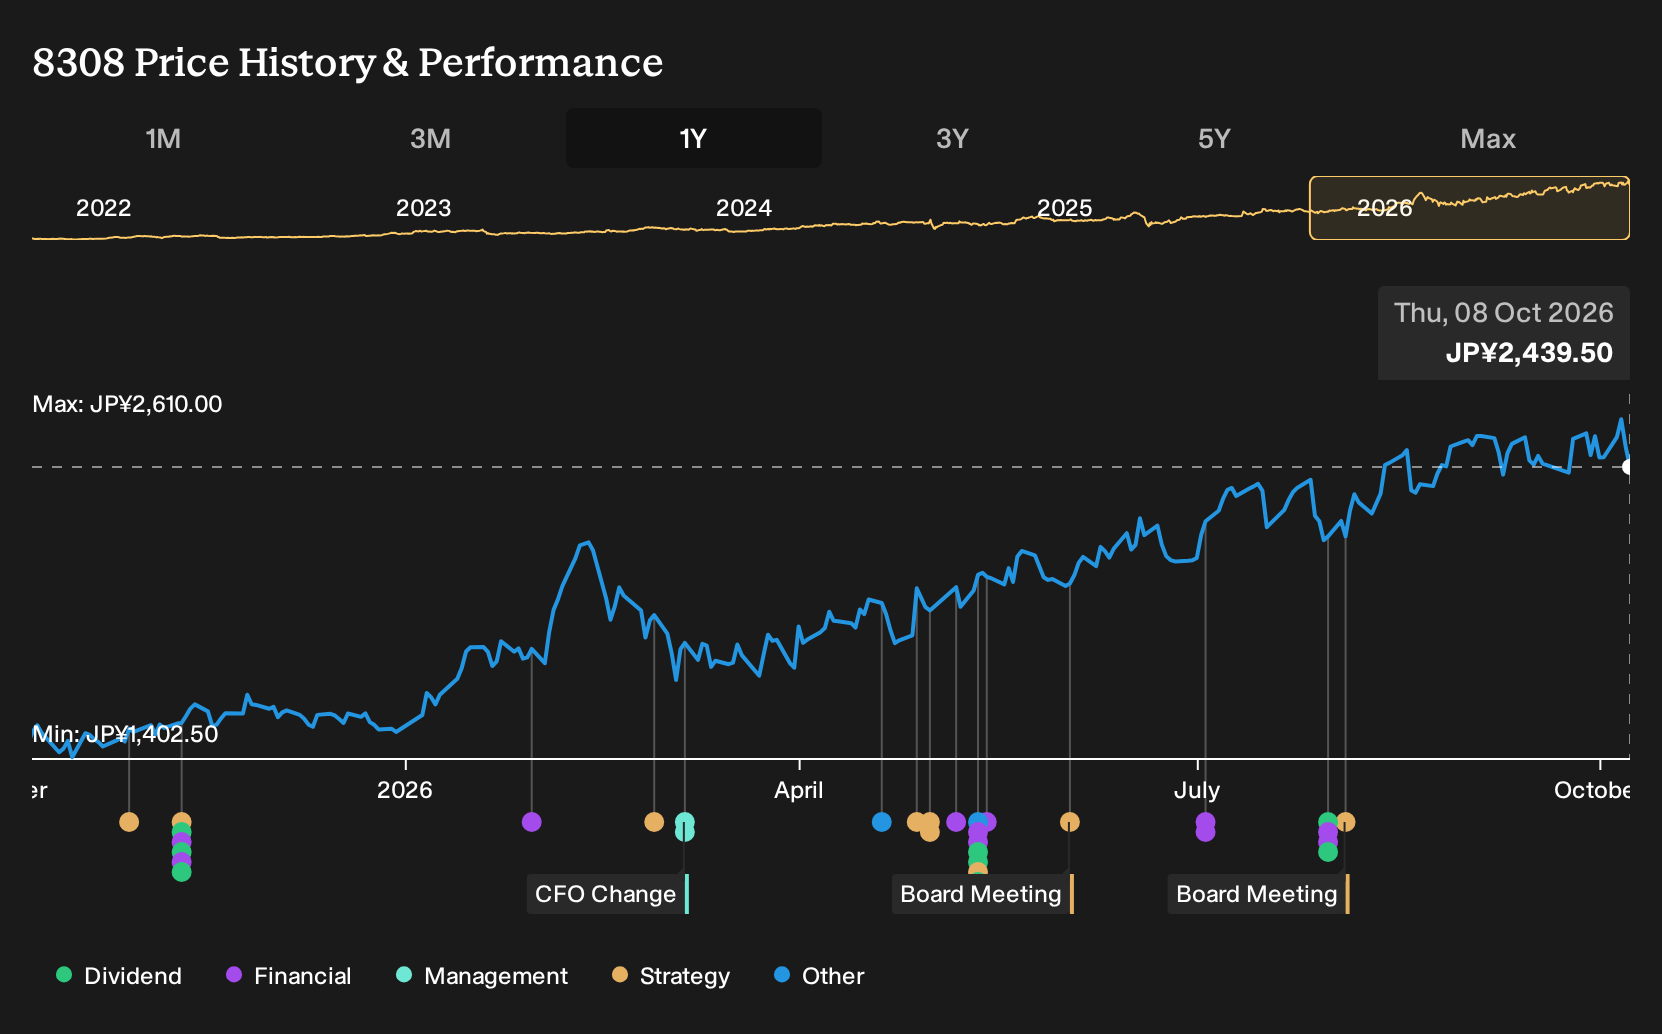
Resona Holdings (TSE:8308)
Overview: Resona Holdings is a Tokyo headquartered retail and commercial bank that leans heavily on Japan’s interest rate curve for its core earnings.
Operations: Resona generates ¥452,392 million from Personal Banking and ¥511,483 million from Corporate Banking, with revenue of ¥1,165,667 million almost entirely from Japan.
Market Cap: ¥5,473.7b
Resona Holdings matters for this screener because its balance sheet is built to translate a steeper, higher JGB curve into interest income that supports capital returns and steady lending to households and small businesses.
"Expansion of net interest income through volume growth and interest rate hikes is expected to continue, positively impacting revenue and earnings growth."
What investors will watch most closely is how one quiet shift in the way Resona Holdings manages costs and capital shapes those future margins.
Those shifts in cost discipline and capital use are exactly what the full narrative for Resona Holdings unpacks in full, revealing where Resona Holdings could be quietly accelerating or stalling.
JAPAN POST BANK (TSE:7182)
Overview: JAPAN POST BANK is a large Japan-based retail and institutional bank that channels domestic deposits into loans and investment products.
Operations: JAPAN POST BANK generates ¥1,945.5b from Banking Services, almost entirely from Japan, tying its earnings closely to domestic interest rates.
Market Cap: ¥11.6t
JAPAN POST BANK is where the screener’s theme becomes real for everyday savers, because its huge pool of domestic deposits is invested directly into JGBs and rate-sensitive assets.
"The shift to positive yen interest rates and expectations for further Bank of Japan policy rate hikes are seen as creating a more supportive environment for reinvestment returns on domestic fixed income. This can help sustain the bank's profit expansion phase and influence net margins."
What ultimately matters for JAPAN POST BANK is how one quiet change in portfolio mix shapes the durability of those margins investors care about.
To see how that portfolio tilt could accelerate or stall, read the full narrative for JAPAN POST BANK for JAPAN POST BANK and look for any points where policy, reinvestment and deposit behaviour may be decoupling.

Curious About Bigger Market Alternatives
Fresh ideas move fast. By the time a breakout trend hits headlines, early momentum can be flying or already caught. Scan under the radar for now and get in early.
- Spot cash flow strength before it is widely talked about by running the 14 high quality undervalued stocks alongside companies with solid balance sheets and grounded fundamentals.
- Track where AI momentum meets real profits instead of hype by filtering companies through the curated 35 profitable AI stocks that aren't just burning cash list.
- Position for the next leg of electrification by reviewing producers in the focused 16 top copper producer stocks and see which operators keep volumes and projects on track.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com