
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Denali Therapeutics (DNLI) Dropped, So What Is Drawing Attention Now?
Denali Therapeutics (DNLI) drew investor attention after its shares closed at $18.67, giving the biopharma business a market value near $3.1 billion and reflecting a history of mixed long-term returns.
Recent trading has been choppy for Denali Therapeutics, with the share price down 2.56% on the day and falling 27.30% over the past 90 days, yet still showing a 14.75% year to date share price return and a 15.46% total shareholder return over one year. This indicates that longer term holders have experienced gains even as short term momentum has cooled.
Compare Denali Therapeutics with a hand picked group of resilient biopharma names by screening for 31 resilient stocks with low risk scores that may better match your risk tolerance.
Denali Therapeutics now trades at a steep discount to the average analyst target near $36, even as the firm’s own intrinsic value estimate is close to the market price. Is investor caution still warranted at this level?
Most Popular Narrative: 47% Undervalued
On the most followed narrative, Denali Therapeutics screens as materially undervalued, with a fair value estimate of $35.44 against the recent $18.67 close. This comparison puts the current share price at a steep discount to what that framework implies.
The enzyme transport vehicle franchise targets multiple lysosomal storage disorders where biologics are already an accepted treatment class. Denali Therapeutics expects each program to represent several hundred million dollars or more in potential annual market opportunity, which can influence long term revenue diversification and earnings resilience.
See why 1 investors see Denali Therapeutics as 47% undervalued.
Result: Fair Value of $35.44 (UNDERVALUED)
Still, the fair value story for Denali Therapeutics can quickly break if AVLAYAH uptake stalls or if costly Alzheimer’s trials fail to produce supportive data.
Find out about the key risks to this Denali Therapeutics narrative.
Another View on Denali Therapeutics Valuation
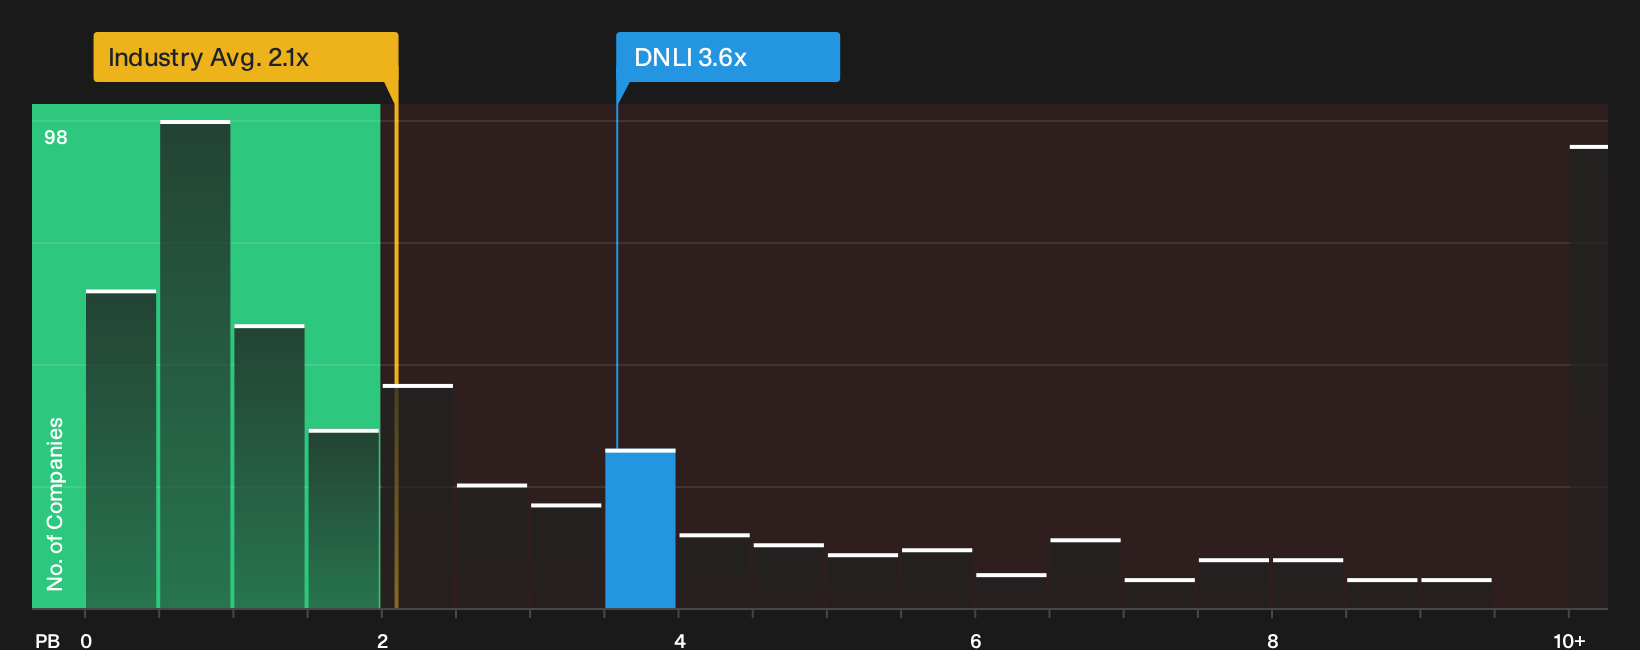
The earlier narrative leans on long term earnings forecasts and analyst targets to argue Denali Therapeutics looks undervalued. A different lens comes from a simple balance sheet based check. On P/B, DNLI trades at 3.6x versus 2.1x for the wider US Biotechs group and 3.6x against a 4.8x peer average, which points to a richer tag than the sector but cheaper than closer comparables. Does that mix of premium and discount fit with the risk you see in an unprofitable pipeline story?
For a closer look at how this kind of ratio based view stacks up against more detailed valuation work, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
The mixed tone around Denali Therapeutics only matters if it shapes your own decision, so move quickly, review the data, and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Denali Therapeutics?
If you only focus on Denali Therapeutics, you could miss other compelling setups. Put a shortlist together, pressure test it, and act while the data is fresh.
- Target potential mispricing by scanning the 27 high quality undervalued stocks that combine solid fundamentals with prices that lag underlying business quality.
- Build a sturdier core portfolio by focusing on a list of solid balance sheet and fundamentals (25 results) so your capital leans on companies with stronger financial footing.
- Get ahead of the crowd by reviewing 20 high quality undiscovered gems before attention and liquidity catch up to their fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com