
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Healthcare Realty Trust Stock's 2.0 Progress Means For Shareholders
- Healthcare Realty Trust reported that Phase I of its 2.0 plan is complete, with new operating systems, a rebuilt management team, and a balance sheet that management describes as stronger. Phase II is now focused on leasing and health system relationships.
- The update highlights that execution is shifting from internal fixes to tenant-facing actions. This shift puts leasing performance and hospital-partner ties at the center of Healthcare Realty Trust’s next phase of operational progress.
- We will now look at how Healthcare Realty Trust’s investment narrative could be affected by the faster progress on its 2.0 plan.
Healthcare Realty Trust Investment Narrative Recap
To own Healthcare Realty Trust, you need to buy into a fairly simple idea. Management has done the internal repair work and now needs to turn a large US$11.1b medical office footprint into steadier occupancy, healthier rent spreads, and more predictable cash flow. The near term swing factor is leasing momentum in the lease up portfolio, supported by tighter health system partnerships.
The biggest operational risk is that those better leasing outcomes arrive more slowly than hoped. Underinvestment in some properties and past strain with hospital partners could hold back net operating income, just as higher leverage and a not fully covered dividend leave less room for error if capital markets remain demanding.
The clearest link between the recent update and the existing catalyst map is the 2.0 plan goal of roughly US$50m of incremental NOI from US$300m of projects in the lease up portfolio. Finishing Phase I and moving cleanly into Phase II gives that plan more operational scaffolding. The rebuilt operating team and new systems are important in this context.
Execution now sits in plain view. Leasing results, redevelopment pacing, rental rate outcomes, and the cadence of asset level capex will indicate whether Healthcare Realty Trust is converting its medical office scale into that embedded upside. Any hiccups, including project delays, weaker rent terms, or slower occupancy gains, would feed directly into the main risk investors are already monitoring.
Healthcare Realty Trust's current analyst narrative links a projected US$1.2b of revenue and US$221.9m of earnings by 2029 to a 1.2% yearly increase in revenue and an earnings swing of about US$425.7m from a loss of US$203.8m today.
Uncover why Healthcare Realty Trust's fair value indicates a 23% potential upside to its current price that could narrow quickly.
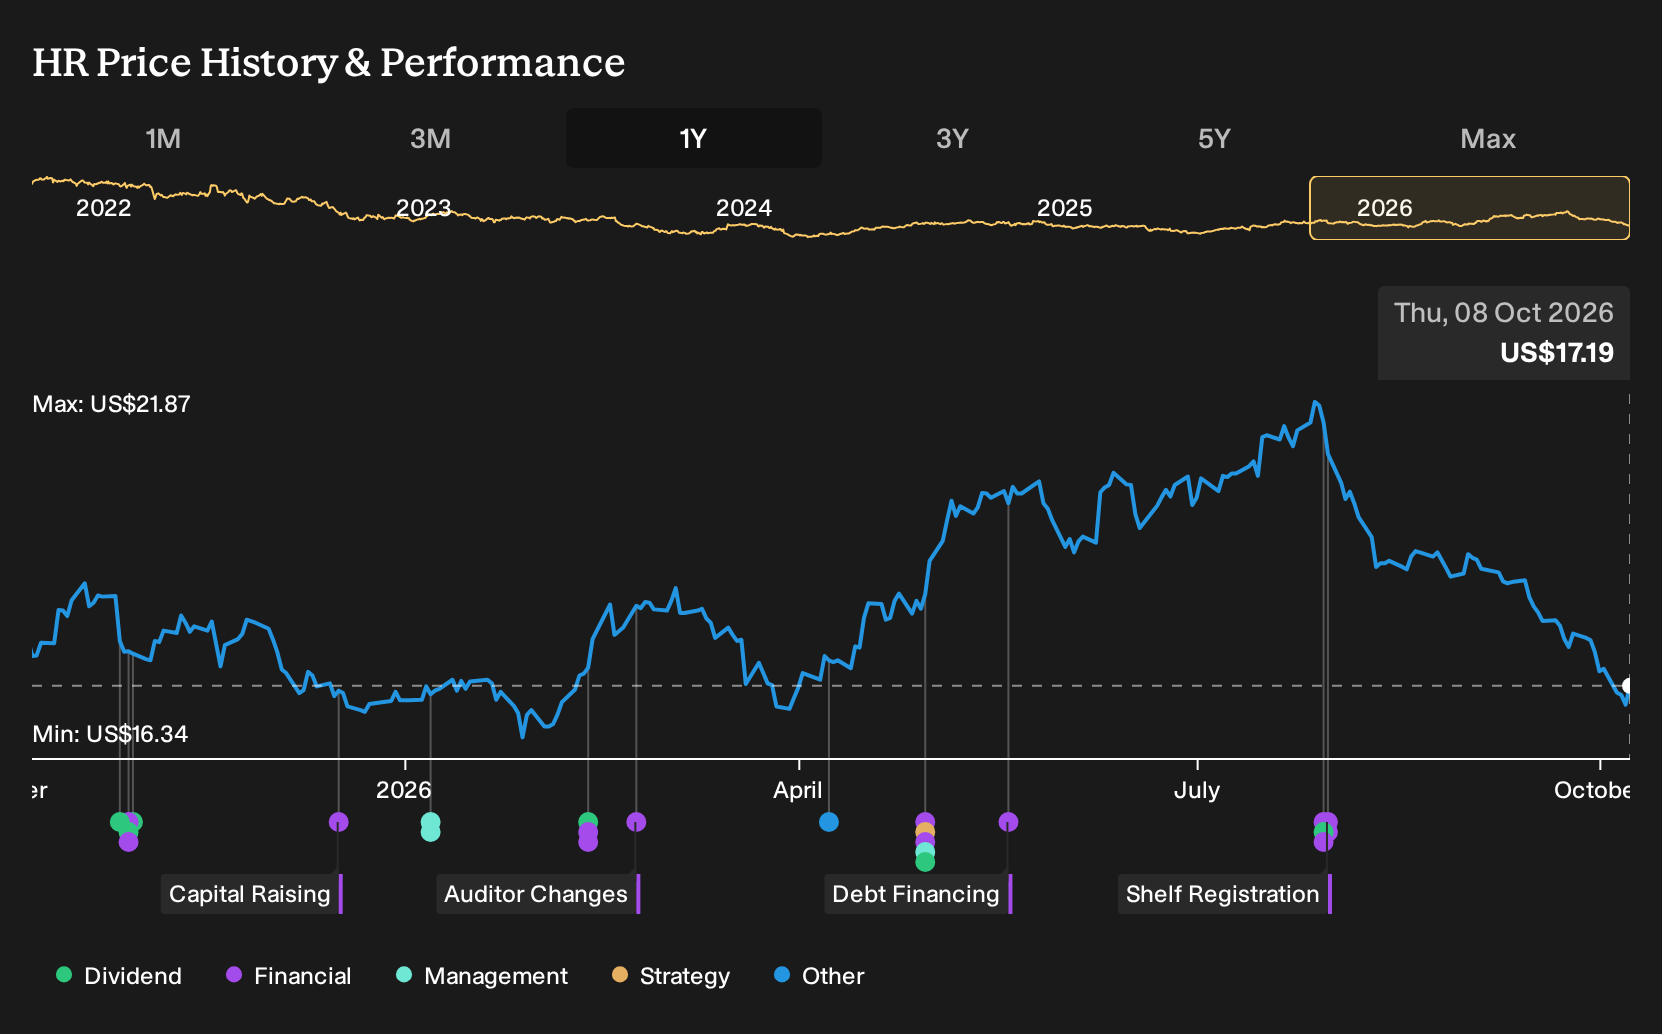
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$21.08 to US$28.29 per share, so retail opinions on Healthcare Realty Trust already cover a wide band. Those views do not factor in recent 2.0 plan progress. At the same time, execution risks around lease-up, health system ties, and leverage could still reshape expectations. Consider reviewing several community viewpoints before forming your own stance.
Explore another Healthcare Realty Trust fair value estimate, including one that suggests it could be worth just $21.08!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Healthcare Realty Trust research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Healthcare Realty Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Healthcare Realty Trust's overall financial health at a glance.
Looking For More Ideas Beyond Healthcare Realty Trust?
If Healthcare Realty Trust has sharpened your focus on balance sheets, cash flow, and risk, it can help to compare it with a broader set of businesses that share similar qualities. The Simply Wall St Screener lets you filter for traits that match your style, so you can build a watchlist that lines up with your own risk and return preferences.
- If you prefer potential value opportunities with quality fundamentals over hype driven stories, and want a curated set of ideas to review, take a look at 20 high quality undiscovered gems.
- If capital preservation and steadier profiles matter most to you, filter for companies that score well on financial resilience using the 31 resilient stocks with low risk scores.
- For investors who want income and staying power in one place, focus on high-yield payers with robust fundamentals through the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com