
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hershey (HSY) Could Be 45% Undervalued As International Leadership Shifts
Leadership change puts Hershey’s international plans in focus
Hershey (HSY) just reshaped its global bench by appointing Amanda Almond as President, International. This move naturally draws attention to how investors view the stock’s overseas potential.
Recent trading has been choppy for Hershey, with a 1-day share price return of 1.37% and a 7-day gain of 2.03% coming after a 30-day share price decline of 6.19% and a year-to-date drop of 10.89%, while the 1-year total shareholder return is down 13.05%. This points to fading momentum even as the leadership reshuffle puts fresh attention on how the business is priced and perceived.
Scan how Hershey compares with other consumer-focused businesses under pressure and spot potential rebound candidates across our curated 27 high quality undervalued stocks.
Hershey still looks like a solid global confectionery and snacks franchise, especially with fresh leadership in its overseas arm. The real issue for investors is whether the recent share slide already reflects that strength or not.
Most Popular Narrative: 105% Overvalued
Hershey closed at $162.54, while the widely followed narrative fair value sits at $79.25, so the story centers on whether investors are still paying a premium for a slow but steady business.
A fortress brand-and-scale position in U.S. confectionery (Reese’s, Hershey’s, Kisses) generates ~23% through-cycle ROIC and exceptionally durable free cash flow that fell only ~13% even in the worst input-cost year on record. The 2025 cocoa shock, a ~60% GAAP EPS collapse driven largely by non-cash hedge mark-to-market, obscured an underlying cash engine that remained intact.
See why 7 investors see Hershey as 105% overvalued.
According to Esteban, the narrative behind Hershey assumes a discount rate of 7.11%, revenue growth of 9.21% in decline rather than expansion, and a profit margin of 9.12%, which together produce an assessed fair value of $79.25. Against a market value of roughly $32.2b, that view suggests investors today may be paying a full price for a business described as high quality but growth constrained.
Esteban also frames the thesis around three hinges for Hershey, including cocoa costs, the reach of the One Hershey playbook into salty snacks and international channels, and the long glide path of GLP-1 drugs on confectionery demand. For readers weighing the new international leadership, that lens treats overseas expansion less as a growth engine that transforms the story and more as a way to support moderate top-line progress while the core U.S. franchise keeps cash generation steady.
Result: Fair Value of $79.25 (OVERVALUED)
Still, the narrative could crack if cocoa costs stay elevated for longer than expected, or if GLP-1 adoption dents Hershey’s indulgence-driven volumes.
Find out about the key risks to this Hershey narrative.
Another View: Hershey Through A Cash Flow Lens
The narrative fair value pegs Hershey at $79.25 and labels the stock as expensive. Our DCF model tells a different story. On that cash flow view, HSY at $162.54 trades about 45.1% below an estimated future cash flow value of $296.07, which presents the premium argument in a very different light. Which lens do you trust more when the signals clash this sharply?
For readers who want to unpack how that cash flow estimate is built step by step, Look into how the SWS DCF model arrives at its fair value.
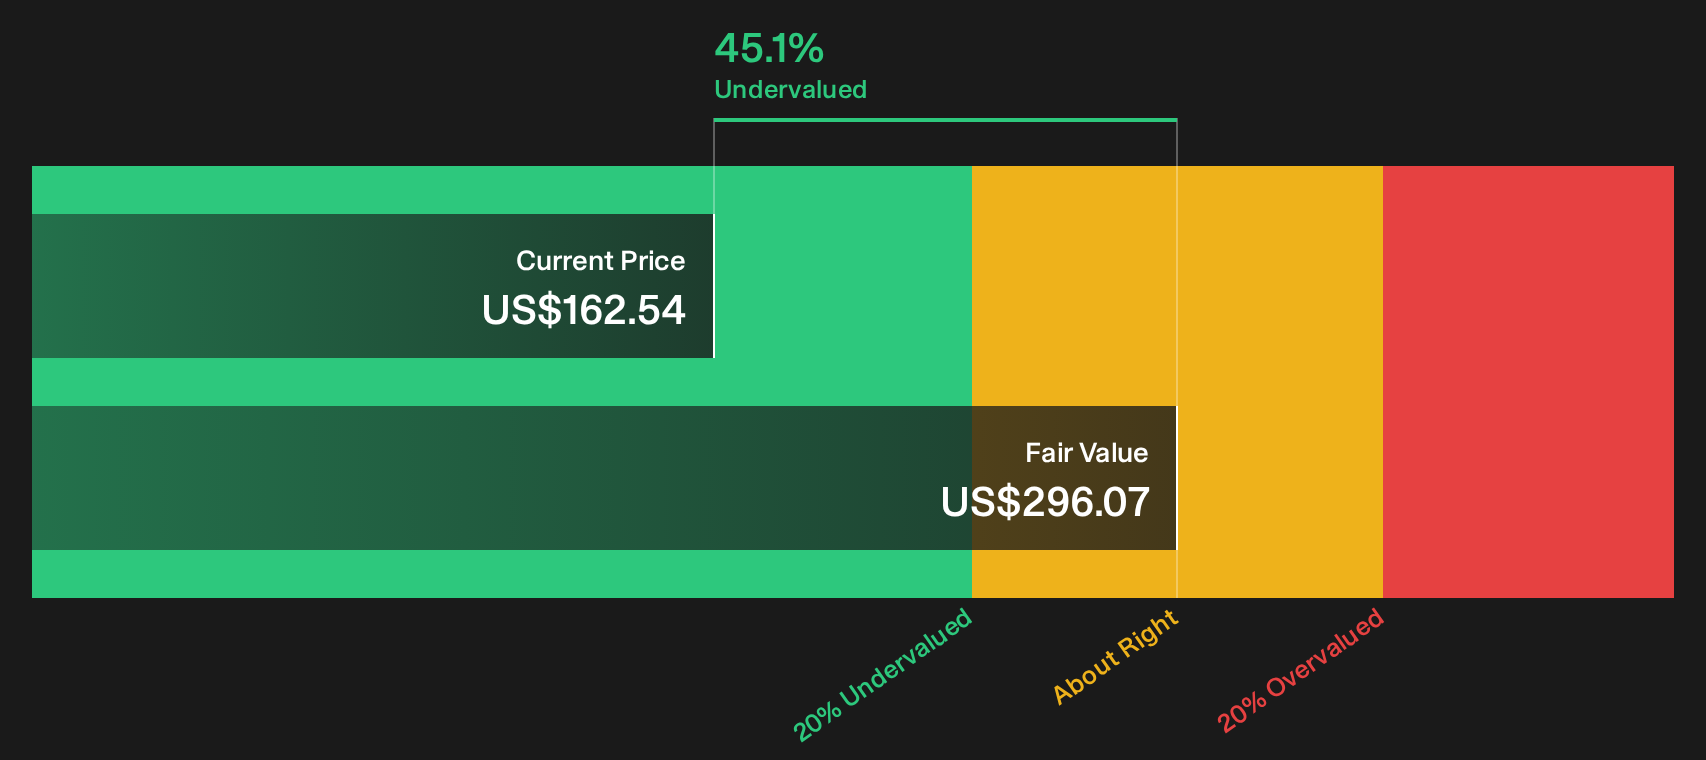
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hershey for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Hershey can leave you torn, so move quickly, review both the upside and the caution flags, and then weigh the 4 key rewards and 1 important warning sign.
Looking for more Hershey sized investment ideas?
If Hershey has you rethinking your playbook, do not stop there. Use the tools available now, or you risk missing stronger risk reward setups elsewhere.
- Target potential turnarounds by scanning our hand picked 27 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect them yet.
- Strengthen your income stream by reviewing a focused list of 8 dividend fortresses that aim to pair higher yields with resilient business profiles.
- Dial down portfolio volatility by assessing a curated 31 resilient stocks with low risk scores built around companies with sturdier financial and risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com