
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is PDD Holdings (NasdaqGS:PDD) Below Fair Value Near Its 52 Week Low?
PDD Holdings is trading close to its 52 week low after a difficult stretch for the share price, which puts a spotlight on a simple question for investors who care about fundamentals. Is the current market value of PDD stock still in line with what its earnings can reasonably support?
- The share price is down 40.4% over the past year, so the market has already repriced expectations and raised fresh doubts about how much of PDD’s earnings power is being recognized.
- Management is pushing hard on Temu’s international rollout while dealing with higher cross border costs and regulatory pressure, which can affect how much profit eventually falls to the bottom line and how lumpy those earnings might be.
- Your read on PDD Holdings is one view; the desks covering it have another. See what analysts think PDD Holdings's shares could be worth.
The issue now is whether PDD Holdings’ current share price is justified by the earnings the business is generating today and is realistically expected to produce in the near term.
If you are weighing whether PDD Holdings still earns its current P/E, it can help to benchmark against a wider field using a focused screener of 27 high quality undervalued stocks.
Is PDD Holdings a Bargain on Earnings?
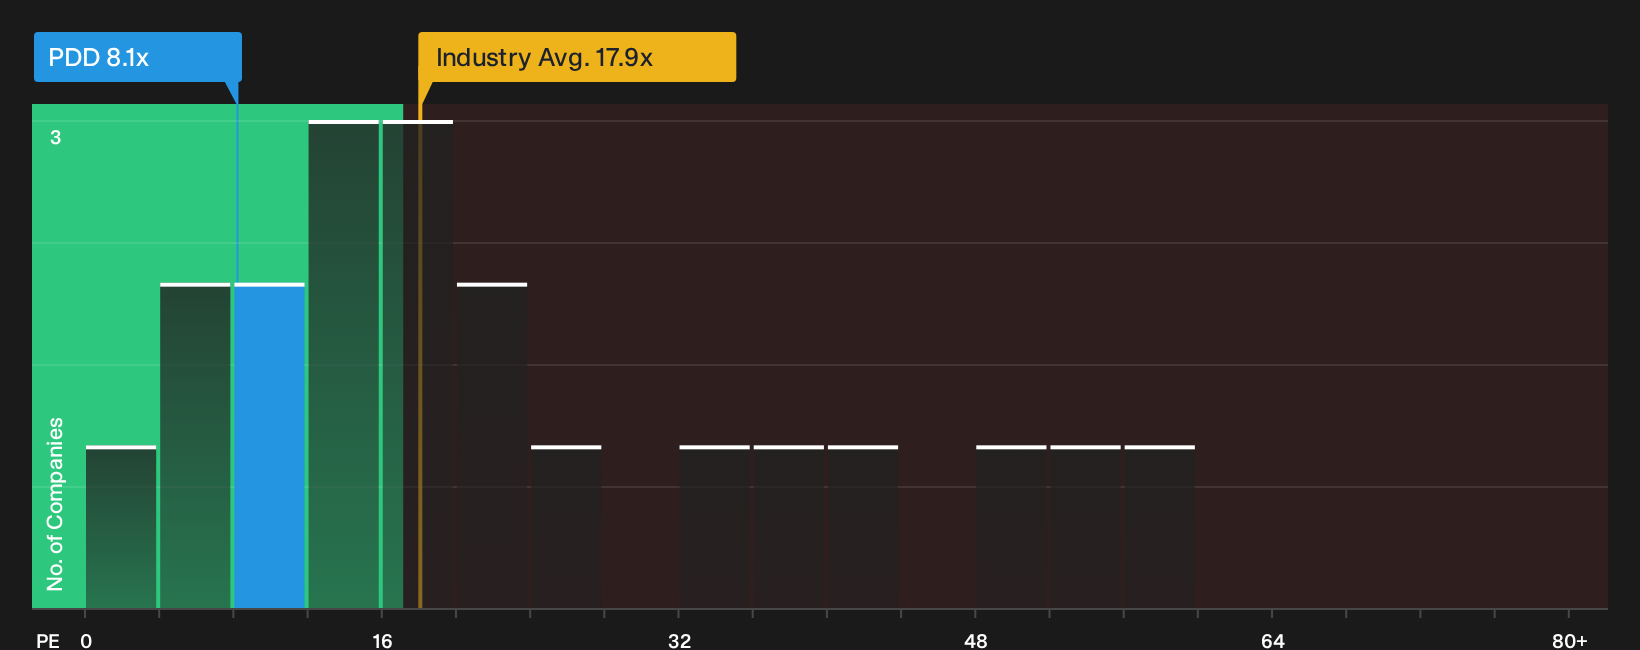
The P/E ratio is a useful shortcut here because earnings remain the main anchor for how PDD Holdings is being valued. On this measure, the stock trades on roughly 8.1x earnings, which is far below the wider multiline retail group on about 17.9x and also sits well under a broader peer set on roughly 33.0x. For a business still investing heavily in Temu and absorbing higher cross border costs, that is a low headline multiple for the current profit stream.
The tailored fair multiple, which blends factors like growth expectations, margin profile, size and risk, points to a higher P/E than where PDD Holdings changes hands today. Because the share price is near a 52 week low after regulatory and international expansion setbacks, this gap suggests the market is pricing in a lot of execution and policy risk even against that more customised benchmark. For investors, the question is whether those concerns fully explain such a wide P/E discount or leave room for a re rating if earnings hold up. Explore the numbers behind PDD Holdings's P/E valuation.
The PDD Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this PDD Holdings valuation puzzle leaves off and explain which future paths for growth, margins and earnings would need to occur for the share price to look materially higher or lower than it does today on the Community page. Each scenario treats PDD Holdings' implied worth as a thesis that can be tracked over time, so you can see how the reasoning holds up as fresh information becomes available.
One of the top community narratives on PDD Holdings: 32% undervalued
"Investments in ecosystem development, supply chain efficiency, and international expansion are diversifying revenue streams and strengthening PDD's ability to capture e commerce growth..."
Discover why this Narrative puts PDD Holdings at 32% undervalued.
One more PDD Holdings check that sits beside the P/E math
You have a snapshot of what PDD Holdings costs today, but there is a separate lens in how covering analysts map out profits and revenue a few years from now, and how that lines up with this price. Explore where analysts expect PDD Holdings to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com