
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CITIC Construction Investment: Building a zero-carbon park into a systematic project is expected to become the main line of resonance between green finance and industrial investment
The Zhitong Finance App learned that CITIC Construction Investment released a research report stating that in China, the park has a dual strategic position as an economic growth carrier and carbon emission control scenario. Under the guidance of the Central Economic Work Conference and multi-departmental supporting policies, the construction of a zero-carbon park has become a systematic project in China. According to the bank's estimates, the zero-carbon transformation of national zero-carbon parks alone has invested 100 billion dollars. At the level of sustainable financial instruments, green credit, ESG bonds, green leasing, etc. have taken shape and are highly compatible with the characteristics of projects with large capital expenditure, long payback periods, and stable cash flow for some assets. Cases such as Mengsu in Ordos and Dafeng Port in Yancheng have verified the closed commercial loop of “low-cost traceable green electricity+industrial agglomeration”, and zero-carbon parks are expected to become the next main line of resonance between green finance and industrial investment.
CITIC Construction Investment's main views are as follows:
1 Zero-carbon parks are the next focus of sustainable finance
Zero-carbon parks can become a new core driving force in the field of sustainable finance. The root cause is the dual strategic position of various parks, mainly industrial parks, in national economic development and carbon emission control, and the iterative upgrading of domestic green and low-carbon policies from unified transformation to systematic zero-carbon construction. On the one hand, through industrial agglomeration, infrastructure integration, and optimal allocation of factor resources, the park has become a core space carrier supporting China's new industrialization, industrial structure upgrading, and open layout to the outside world, and is an important pillar of domestic economic growth; on the other hand, industrial production and centralized energy supply scenarios within the park are highly concentrated, and it is the core control scenario and core gripper for China's industrial sector to achieve the “double carbon” goal. In this context, the green and low-carbon development policy for domestic parks has changed from a single-point upgrading model such as energy-saving transformation, resource recycling, and green factory construction to a systematic construction model using the park as an overall unit to coordinate the energy structure, industrial system, infrastructure, and carbon asset management.
In December 2025, with the implementation of the first batch of national zero-carbon park construction lists, top-level system requirements are being fully transformed into physical projects and implementation projects. This transformation has not only restructured the park's energy supply model and industrial organization, but also broadened the service boundaries of sustainable finance, upgraded the traditional single energy saving and environmental protection project service to a comprehensive park project service system covering green power utilization, energy storage facilities, energy efficiency improvement, resource recycling, and digital carbon management, opening up new business scenarios and investment tracks for financial institutions.
1.1 The park has an important strategic position in China
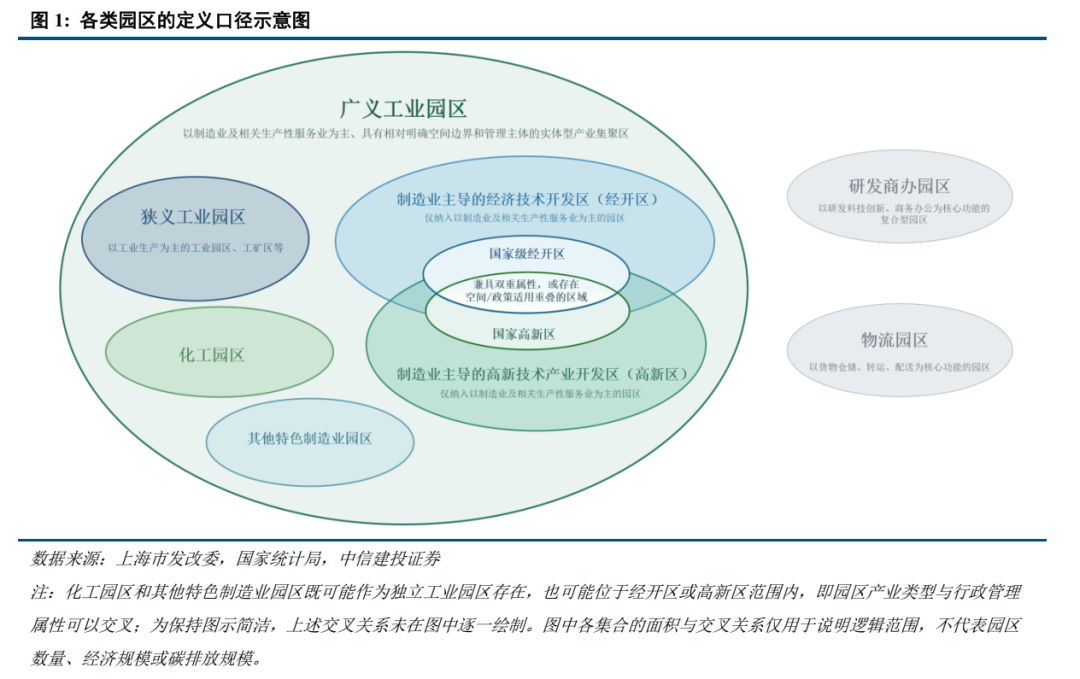
The park has the dual attributes of an economic growth carrier and a green transformation unit. From an economic perspective, the park cultivates industrial chain synergy advantages and economies of scale by gathering market players, integrating supporting facilities, optimizing resource allocation, undertaking investment in the manufacturing industry, and promoting industrial division of labor and collaboration. From a low-carbon perspective, highly concentrated industrial production activities, centralized energy supply systems, and public supporting facilities have made it the main bearing area for domestic energy consumption and carbon emissions. Based on this, various types of parks, mainly industrial parks, are not only a core platform for China to promote new industrialization, industrial upgrading, and expand opening-up to the outside world, but also a core implementation scenario for low-carbon transformation and carbon reduction in the industrial sector.
1.1.1 Parks account for a large proportion of China's total economy
Various parks are the core space carriers for China to undertake investment in the manufacturing industry, organize industrial division of labor and collaboration, and promote opening-up to the outside world. Through unified planning and intensive allocation of resources such as land, standard plants, energy supply, logistics facilities, pollution control and public services, the park can guide upstream and downstream enterprises in the industrial chain to form geospatial clusters, effectively reduce the cost of collaboration between enterprises and the marginal cost of public service supply, and give full play to economies of scale and industrial cluster effects. On February 6, 2017, “Certain Opinions on Promoting the Reform and Innovative Development of Development Zones” issued by the General Office of the State Council clearly states that various development zones, which are important components of industrial parks, play an irreplaceable role in promoting institutional reform, improving the investment environment, guiding industrial agglomeration, and developing an open economy, and are an important platform for promoting China's industrialization, urbanization process and expanding opening-up to the outside world.
National economic and technological development zones and national high-tech industrial development zones are typical platforms in industrial parks where industrial energy levels are high, national policy priorities are skewed, and the corresponding ministries and departments focus on them. Using national economic development zones and national high-tech zones as typical samples, it is possible to explain the park's carrying role in the industrial economy, innovation activities, and green transformation.
In terms of industrial carrying capacity, national economic development zones account for a high proportion of the country's secondary sector. According to data from the Ministry of Commerce, 232 national economic development zones across the country achieved an added value of 9.8 trillion yuan in the secondary sector in 2024; according to the National Bureau of Statistics, the value added of the country's secondary sector during the same period was 49.21 trillion yuan. According to this estimate, the value added of the secondary sector in national economic development zones accounts for about 19.9% of the country's secondary sector value added. The indicator shows that the national economic development zone gathers large-scale industries and related production activities, and is an important spatial unit for observing the green transformation of the manufacturing industry, the transformation of park infrastructure, and the low-carbon upgrading of the industrial chain.
Judging from the concentration of advanced manufacturing and innovation resources, national economic development zones and high-tech zones have a significant supporting effect on the country's industrial growth. According to data released by the Ministry of Industry and Information Technology, in 2025, the National High-tech Zone achieved a gross domestic product of 20.4 trillion yuan, accounting for 14.6% of the country's gross domestic product, and achieved tax revenue of about 2.1 trillion yuan; its industrial value added exceeded 10 trillion yuan, accounting for 24.1% of the country's industrial value added. According to data estimates released by the Ministry of Commerce, the national economic development zone will account for about 12.5% of the country's GDP in 2024, and will also account for a large share of the national economy.
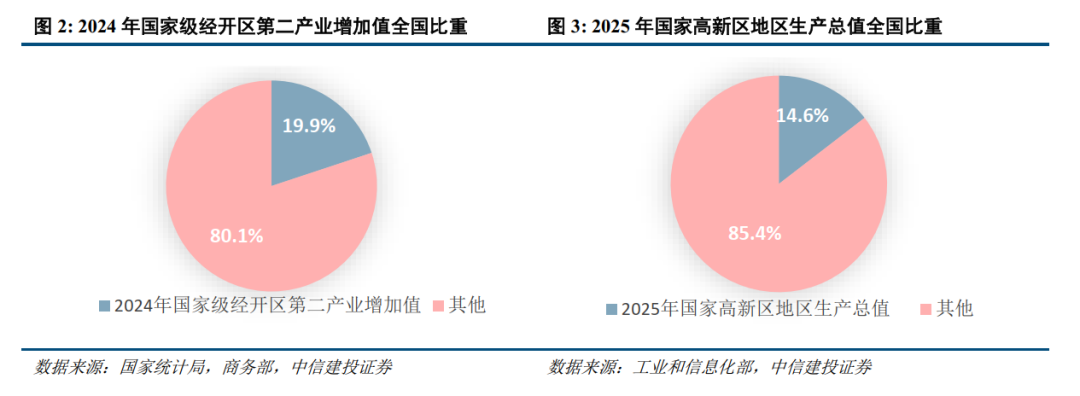
Based on the concentration of comprehensive industrial output, the overall size of the park system, and comparable statistics of high-energy parks, it can be determined that parks account for a high proportion of China's industrial economy and regional economic development. National economic development zones and national high-tech zones account for a high share of the country's industrial value added, which has fully demonstrated that manufacturing and related economic activities are highly concentrated within the park space. The park is therefore an important form of spatial organization that promotes industrial growth, technological innovation, industrial chain collaboration, and green and low-carbon transformation.
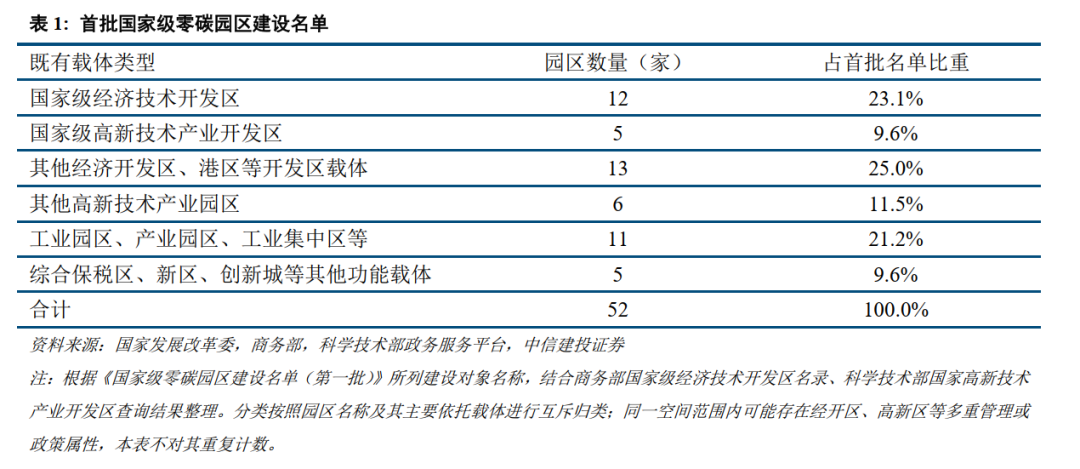
Over 30% of the first batch of national zero-carbon park construction targets were located in national economic and technological development zones and national high-tech industrial development zones. After comparing the first batch of national zero-carbon park construction lists, the Ministry of Commerce's national economic and technological development zone list, and the official search results of national high-tech industrial development zones, out of 52 national zero-carbon park construction targets, 12 were located within national economic development zones and 5 were located within national high-tech zones, for a total of 17, accounting for 32.7%. The remaining 35 rely on the construction of other economic development zones or special functional carriers such as the Lingang Economic Zone, other high-tech industrial development zones, industrial parks, industrial parks, free trade zones, new zones, and science and technology innovation cities.
Other types of parks also have a high concentration of economic and industrial activities. According to the 2024 assessment results issued by the Fujian Provincial Department of Commerce, the province's development zones achieved a gross domestic product of 2485.473 billion yuan, accounting for 43.0% of the province's gross domestic product; the operating income of industrial enterprises above scale was 4187.932 billion yuan, accounting for 70.6% of the province; and tax revenue of 195.155 billion yuan, accounting for 41.8% of the province. According to provincial response data from the Liaoning Provincial Department of Commerce, the gross domestic product, general public revenue, actual use of foreign capital, and import and export volume achieved by 106 economic development zones above the provincial level in 2024 accounted for 36.0%, 40.9%, 49.8%, and 61.6% of the province's total volume, respectively, including 92 economic development zones and 14 high-tech industrial development zones. Research by the Standing Committee of the Yunnan Provincial People's Congress shows that in 2024, 89 development zones in the province contributed 20% of the province's gross domestic product, 40% of industrial investment, and nearly 80% of the total industrial output value. Types include industrial parks, economic and technological development zones, high-tech industrial development zones, comprehensive bonded zones, and border (cross) border cooperation zones with less than 1% of the land area. The above provincial evidence shows that in addition to national economic development zones and national high-tech zones, other development zones and industrial parks also carry highly concentrated industrial production, investment, and opening up activities.
1.1.2 The park also accounts for a high share of China's total carbon emissions
Industrial parks are space carriers where energy consumption and carbon dioxide emissions are highly concentrated in China, and are a core scenario for carbon reduction control in the industrial sector. A large number of industrial production enterprises such as steel, chemicals, building materials, non-ferrous metals, and equipment manufacturing are gathered within the park space, and public infrastructure such as centralized heating, electricity supply, sewage treatment, warehousing and logistics are combined; the production process emissions of industrial enterprises are superimposed on each other, making the park a centralized bearer of industrial carbon emissions, which also determines its key management position in the industrial low-carbon transformation process.
Industrial parks account for about 30% of the country's total carbon emissions. According to Tsinghua University's “Report on the Green and Low-Carbon Development of Industrial Parks in China (2023)”, there are 2,543 national and provincial parks. 80% of industrial enterprises are already concentrated in parks. National and provincial parks account for 31% of the country's carbon emissions. Recent emission data from micro industrial parks can also support this conclusion. Take the Ningbo Petrochemical Economic and Technological Development Zone as an example. In 2024, the park's carbon emissions exceeded 11 million tons, accounting for 16.7% of Ningbo's total carbon emissions. In regions where high-energy industries such as petrochemicals, steel, non-ferrous metals, and building materials are concentrated, a single industrial park can generate large-scale carbon emissions equivalent to the scale of a city.
The carbon intensity baseline disclosed in the latest policy interpretation further reflects that industrial parks across the country are currently facing greater pressure for deep decarbonization. In July 2025, the National Development and Reform Commission issued an expert interpretation of the “Notice on Launching the Construction of Zero-Carbon Parks”, suggesting that the current carbon emissions per unit of park energy consumption in the country are roughly 2.1 tons of carbon dioxide per ton of standard coal. Compared with the national zero-carbon park construction index system, for parks with an annual comprehensive energy consumption range of 200,000 to 1 million tons of standard coal, the carbon emission per unit energy consumption should not be higher than 0.2 tons of carbon dioxide/ton of standard coal; for parks with an annual comprehensive energy consumption greater than or equal to 1 million tons of standard coal, the carbon emissions per unit of energy consumption should not be higher than 0.3 tons of carbon dioxide/ton of standard coal. It can be seen from this that achieving the goal of zero-carbon park construction is inseparable from carrying out systematic transformation of industrial parks.
1.2 Policies promote the construction of zero-carbon parks
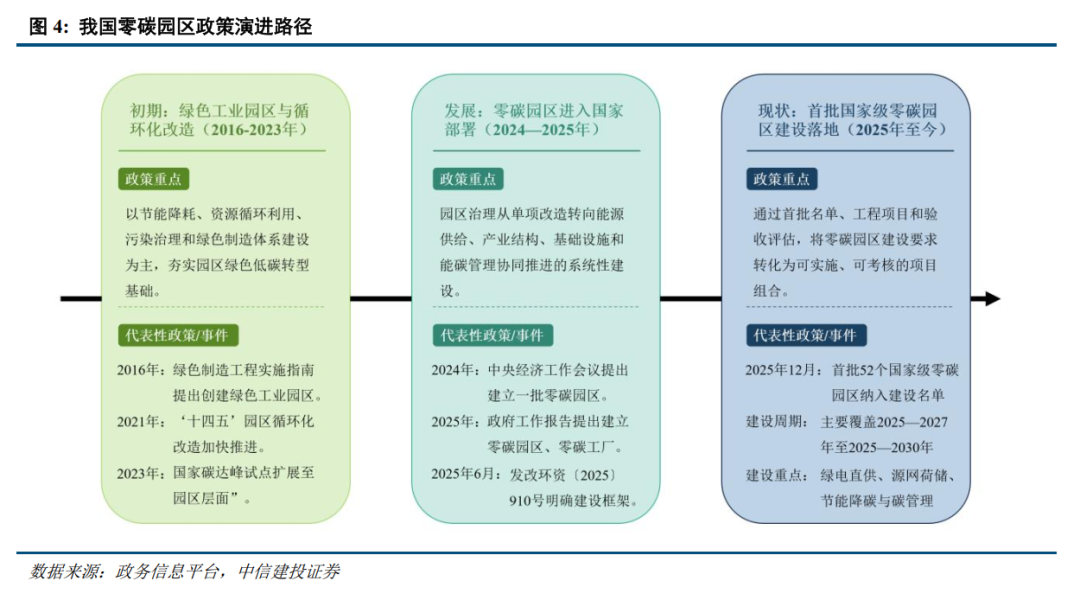
China's green and low-carbon policy for parks has gradually moved from individual transformation focusing on energy efficiency, recycling, and green manufacturing to systematic construction using parks as units to coordinate energy, industry, infrastructure, and carbon management. The main line of policy evolution can be summarized into three stages: initially consolidating the foundation of low-carbon development through the creation of green parks and circular transformation of parks; incorporating zero-carbon park construction into the country's top-level deployment in the medium term to establish a unified standardized construction framework; and at this stage, through the implementation of the first batch of national zero-carbon park lists, to promote the full transformation of system regulations into physical engineering projects and implementation results.
Along with policy iterations, the park's low-carbon management goals have been deeply upgraded from “reducing the intensity of resource and environmental consumption” to “building a comprehensive development system with near-zero emissions.” Traditional green park construction focuses on improving resource and energy efficiency and optimizing environmental performance; new zero-carbon park construction also focuses on high proportion of renewable energy consumption, collaborative linkage of source and load storage, low-carbon upgrading of industrial structures, refined energy carbon management, and green business model innovation. Corresponding to the field of sustainable finance, the service boundary has also expanded from a single energy saving and environmental protection project to a full-chain integrated park project system covering green power applications, energy storage facilities, energy efficiency upgrades, circular economy, and digital carbon management.
1.2.1 Early stage: green industrial park
The creation of green industrial parks and the circular transformation of parks are the policy source and practical foundation for the construction of zero-carbon parks in China. Relying on the construction of a green manufacturing system, this stage focuses on improving resource utilization efficiency, clean production and recycling. The aim is to improve extensive development methods with high consumption, high emissions and low circulation in industrial parks, and to accumulate practical experience, improve supporting standards and cultivate a foundation for transformation for subsequent zero-carbon park construction. In September 2016, the Ministry of Industry and Information Technology and other departments issued the “Green Manufacturing Project Implementation Guidelines (2016-2020)”, officially incorporating green industrial parks into the green manufacturing system. The document proposes to create 100 green industrial parks by 2020, guide the parks to carry out basic greening transformation such as hierarchical utilization of energy, recycling of water resources, exchange and utilization of solid waste, and intensive land utilization, and promote the green transformation of parks from scattered exploration to large-scale creation.
Follow-up policies continue to complete the park's green and low-carbon governance system and promote the transformation process from model creation to full promotion. In December 2021, the National Development and Reform Commission and the Ministry of Industry and Information Technology jointly deployed the “14th Five-Year Plan” park recycling transformation work, making it clear that by the end of 2025, parks above the provincial level that meet the conditions will basically complete circular transformation, focus on improving the efficiency of water, land, energy and other resources, and work together to reduce emissions of carbon dioxide, solid waste, wastewater, and major air pollutants.
The Carbon Dafeng Park pilot has further enriched the practical scenarios for carbon reduction in the park system. In November 2023, the National Development and Reform Commission issued the “National Carbon Peak Pilot Construction Plan”, which proposes to carry out carbon peak pilot projects in representative cities and parks; 10 parks were included in the first batch of pilot lists announced in December of the same year to explore differentiated and regional carbon peak paths based on different resource endowments and development. The definition, cultivation and management mechanisms of green industrial parks were then further regulated. In January 2024, the Ministry of Industry and Information Technology issued the “Interim Measures on Gradient Cultivation and Management of Green Factories”, which defines a green industrial park as an industrial park that integrates the concept of green and low carbon into the whole process of planning, spatial layout, industrial chain design, energy resource utilization, infrastructure, ecological environment and operation management, and positions it as a platform for gathering green factories and green infrastructure.
Overall, the core value of this stage is to complete the basic transformation of the park's green development. Relevant policies have improved the efficiency of park resource utilization, standardized pollution control, and established a green manufacturing evaluation system; however, they mainly focus on individual technological transformation, resource cycle optimization, and environmental performance improvement, and have not yet formed a near-zero emission control mechanism centered on unified carbon emission accounting, rigid target constraints, and system emission reduction paths. Therefore, green parks and recycling transformation form the early stages of zero-carbon park construction, but it is difficult to meet the deep emission reduction requirements during the critical period of carbon peak before 2030 alone.
1.2.2 Development: Propose the construction of zero-carbon parks
On the basis of the practice of green parks, recycling transformation, and carbon peak pilots, the country officially deployed zero-carbon park construction at a critical point in time, marking that the green transformation of the park has evolved from stock transformation and pilot exploration at the departmental level to a systematic task of serving the green transformation of the macroeconomy and the improvement of industrial competitiveness. As a result, the construction of a zero-carbon park has entered a stage of institutionalized construction guided by near-zero emissions and the entire park as a unit.
Judging from the timing of the introduction of the policy, the 2024 Central Economic Work Conference proposed “establishing a number of zero-carbon parks”, which is of phased significance. The Central Economic Work Conference undertakes the important function of deploying economic work for the next year. The zero carbon park was included, reflecting that it is not only a matter of green manufacturing or recycling transformation for the department, but also a key task linked to the transformation of economic development methods. The deployment coincides with the end of the “14th Five-Year Plan”, the “15th Five-Year Plan” layout, and the entry into a critical window of carbon peak before 2030. The “Pre-2030 Carbon Peak Action Plan” suggests that the “14th Five-Year Plan” period should lay a solid foundation for carbon peak, that a low-carbon development model for key areas during the “15th Five-Year Plan” period should be basically formed, and that the goal of reaching the carbon peak by 2030 should be achieved. Based on the previous estimate that the park accounts for about 30% of the country's carbon emissions, the park is an important breakthrough in deep industrial carbon reduction. Promoting the construction of a zero-carbon park at this point will help coordinate short-term economic green transformation and medium- to long-term carbon peak goals.
The 2025 government work report further transformed the construction of zero-carbon parks into an annual priority task. In March 2025, the government work report proposed to solidly launch the second batch of national carbon peak pilot projects, establish a number of zero-carbon parks and zero-carbon factories, and deploy them in conjunction with a dual carbon emission control system, expansion of the national carbon emission rights trading market, and the construction of a product carbon footprint management system and carbon labeling certification system to push the top-level strategy into the implementation stage. Moving further from a green park to a zero-carbon park is not a denial of the results of earlier policies, but rather an inevitable iteration to adapt to the upgrading of emission reduction targets. Green parks and recycling transformation mainly focus on resource efficiency, cleaner production, resource recycling, and pollution control, which are intensity improvements and basic capacity building; zero-carbon parks require coordination of energy supply, industrial structure, production processes, infrastructure, and energy carbon management to achieve deep emission reduction and near-zero emissions.
The current high carbon intensity of the park shows that it is difficult for traditional individual transformation to meet the near-zero emission target alone. According to the National Development and Reform Commission's July 2025 policy interpretation, the current carbon emissions per unit energy consumption of national parks are roughly 2.1 tons of carbon dioxide/ton of standard coal; the construction of national zero-carbon parks requires that parks with an annual comprehensive energy consumption of 200,000 to 1 million tons of standard coal should not be higher than 0.2 tons of carbon dioxide/ton of standard coal, and parks with an annual comprehensive energy consumption of not less than 1 million tons of standard coal should not be higher than 0.3 tons of carbon dioxide/ton of standard coal. The gap of about 7-10 times between the two shows that the park needs to shift from optimizing stock efficiency to a systematic transformation of green power replacement, energy storage regulation, industrial optimization, process transformation, and collaborative promotion of energy and carbon management.
The construction of zero-carbon parks also has a policy function connecting the energy transition, carbon market, product carbon footprint, and green trade rules. The Central Economic Work Conference and the government work report placed the zero carbon park, the national carbon market, the product carbon footprint management system, and the carbon labeling certification system side by side, reflecting the synergy between relevant systems: the carbon market forms market-based emission reduction restrictions and incentives. Product carbon footprint and carbon labeling certification provide a rule basis for carbon information accounting, certification and supply chain transmission throughout the product life cycle, and the park provides a common physical carrier for green energy supply, public infrastructure transformation, and enterprise carbon data management. In this policy coordination system, the role of a zero carbon park is to transform carbon constraints and product carbon information requirements into substantial emission reductions on the production side. By unifying the layout of direct green power supply, energy storage facilities, and complementary energy systems, the park can improve renewable energy consumption capacity; through low-carbon upgrading of industrial structures, collaborative transformation of public infrastructure, and refined global energy carbon management, the park can implement the carbon market price signals and product carbon footprint accounting requirements to the energy side, production side, and product side. The “Opinions on Accelerating the Establishment of a Product Carbon Footprint Management System” issued in 2023 also proposes to push enterprises to carry out process transformation, strengthen energy saving and carbon reduction management, and drive upstream and downstream enterprises to strengthen carbon footprint management and collaborative supply chain transformation.
Document 910 of Development and Reform and Environmental Finance (2025) officially establishes a standardized system framework for the construction of national zero-carbon parks. On June 30, 2025, the National Development and Reform Commission, the Ministry of Industry and Information Technology, and the National Energy Administration jointly issued the “Notice on Launching Zero Carbon Park Construction”, which clearly uses the park as the overall unit to promote energy structure transformation, energy saving and carbon reduction, industrial structure optimization, resource conservation and intensive infrastructure upgrading, technology application, energy carbon management, reform and innovation, and standardize the whole process working mechanism such as park declaration, local recommendation, national review, construction implementation and acceptance evaluation.
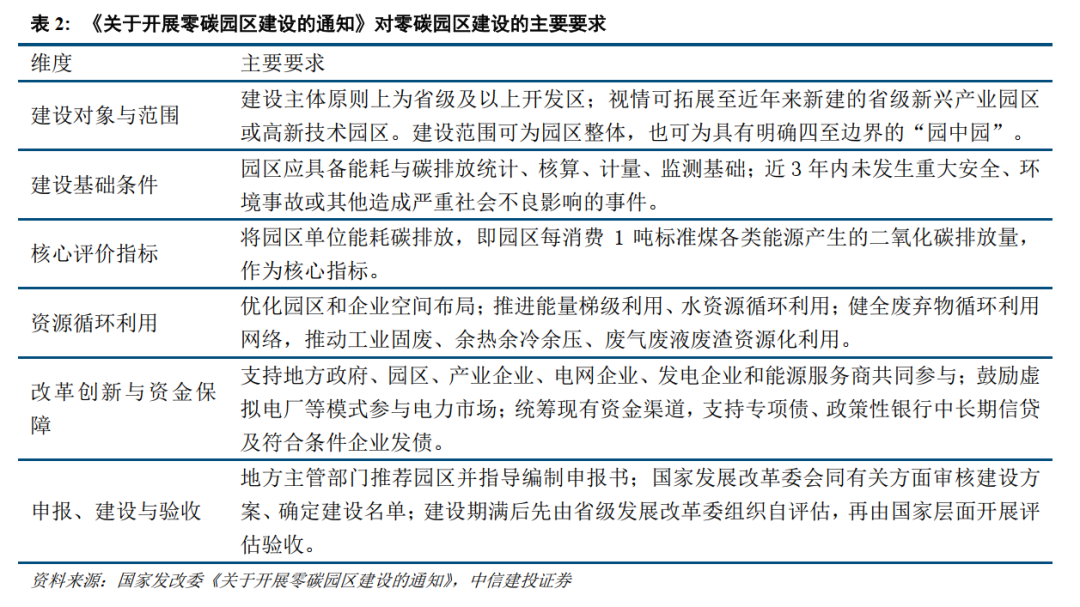
In terms of construction logic, zero-carbon parks emphasize the use of green energy supply and system collaboration to achieve substantial emission reduction within the park's boundaries. The document supports the park's development of a direct green power supply model, such as direct connection of green electricity, the nearby connection of new energy sources to incremental distribution grids, energy storage, and multi-energy complementarity, and encourages the formation of a “green to green” industrial development model. As a result, zero-carbon parks do not obtain the “zero carbon” label through a single project or simple purchase of carbon offsets, but instead form a replicable and promotable industrial near-zero emission transformation path through collaborative innovation through energy supply, industrial organization, infrastructure, and investment and financing mechanisms.
1.2.3 Status: Development of the first batch of zero-carbon parks
The construction of the first batch of national zero-carbon parks has completed the policy layout and has fully entered the practical stage of “listing publicization-project implementation-acceptance certification”. On December 26, 2025, the National Development and Reform Commission, the Ministry of Industry and Information Technology, and the National Energy Administration announced the national zero-carbon park construction list (first batch), which included a total of 52 parks; the list required all regions and parks to prepare construction plans according to the index system, optimize energy supply and consumption and source load matching, plan key tasks and infrastructure projects, and organize inspection and evaluation after reaching the targets.
The first batch of lists showed the common characteristics of national coverage, adaptation to local conditions, and the use of green electricity to support the transformation of the manufacturing industry. According to the National Development and Reform Commission, the first batch of 52 parks was selected by each province (district, city) and at least 1 park by the Xinjiang Production and Construction Corps, and is appropriately skewed towards regions with abundant new energy resources and a good construction foundation; after completion of the park, the direct green power supply ratio is expected to be no less than 50% of the park's electricity consumption, and carbon emissions per unit of energy consumption are about 0.25 tons of carbon dioxide/ton standard coal, which is about one-eighth of the current national park average. The two main construction cycles listed on the list are 2025-2027 or 2025-2030, reflecting that the construction of a zero-carbon park is a medium- to long-term system project.
Currently, the construction of the first batch of zero-carbon parks has completely moved from early plan verification to the physical project implementation phase. On December 31, 2025, the National Development and Reform Commission revealed that of the 52 selected parks, 24 have begun construction of major projects and key low-carbon projects, 24 have completed preliminary preparations and formed physical workloads, and 4 have finalized complete construction paths and implementation plans. Take the Yancheng Dafeng Port Economic Development Zone as an example. The park has built the country's first park-level, physically-traceable “source network load storage” integrated new power system and is exploring a “one-to-many” green power supply model. As of March 2026, it has connected 480,000 kilowatts of new energy installed capacity, which can provide 800 million kilowatt-hours of green electricity per year. According to the construction plan, by 2028 and 2030, the park's new energy installed capacity will reach 1.99 million kilowatts and 2.45 million kilowatts, respectively, and the annual green power supply will increase to 3.4 billion kilowatt-hours and 4.3 billion kilowatt-hours, respectively. At the same time, the park is promoting the transformation of offshore wind power connected to green power dedicated lines, and enhancing green energy service capabilities for new energy and export-oriented enterprises through green power green license transactions, carbon emission surveys, and international certification. This case fully confirms that the construction of the first batch of zero-carbon parks has entered an advanced stage of implementation led by green infrastructure investment and collaborative promotion of low-carbon industrial upgrading and carbon management services.
Since the construction of the first batch of national zero-carbon parks began, supporting implementation plans at the local level have also continued to be followed up, promoting the extension of national deployment to projects, funding, and financial support mechanisms. In September 2026, the Shanghai Municipal Development and Reform Commission and the Municipal Economic and Information Technology Commission issued the “Shanghai Zero Carbon Park Construction Work Plan”, which clearly supports zero-carbon construction in key parks that meet the conditions, and proposes a systematic implementation path around direct green power supply and centralized procurement of green certificates, distributed photovoltaics and energy storage, microgrids, energy saving and carbon reduction transformation, resource recycling, and digital energy carbon management. The plan also proposes to coordinate relevant funds from the country and the city to support technology integration and demonstration projects such as energy-saving transformation, renewable energy development and utilization, and smart energy carbon management in the park; at the same time, guide financial institutions to improve accurate investment mechanisms and innovate green finance products. The local plan shows that the construction of the zero-carbon park is being further promoted through national pilot selection and further into the collaborative promotion stage of local project reserve, construction implementation, and diversified financial support. It also provides a more clear project carrier for sustainable finance to participate in the park's green infrastructure and low-carbon technology transformation.
2 Analysis of the scale and construction and transformation of zero-carbon parks
2.1 Analysis of the scale of zero-carbon parks
2.1.1 Zero-carbon park construction goals
In June 2025, the National Development and Reform Commission, the Ministry of Industry and Information Technology, and the National Energy Administration began construction of a national zero-carbon park. The applicant is a park with an industrial foundation, energy conditions, and carbon reduction potential. After the construction period expires, it must go through provincial self-assessment and national assessment and acceptance, and only after passing the inspection can it officially become a national zero-carbon park.
In December 2025, the three departments announced the first batch of national zero-carbon park construction lists, with a total of 52 parks, covering 31 provinces (districts and cities) and the Xinjiang Production and Construction Corps; the construction cycle is mainly concentrated from 2025-2027 to 2025-2030. The National Development and Reform Commission revealed that 52 parks are expected to have an output value of 3.54 trillion yuan after completion; of these, 24 parks are already advancing major projects and key projects, 24 have begun preliminary work and formed a certain physical workload, and 4 have formed clear construction paths.
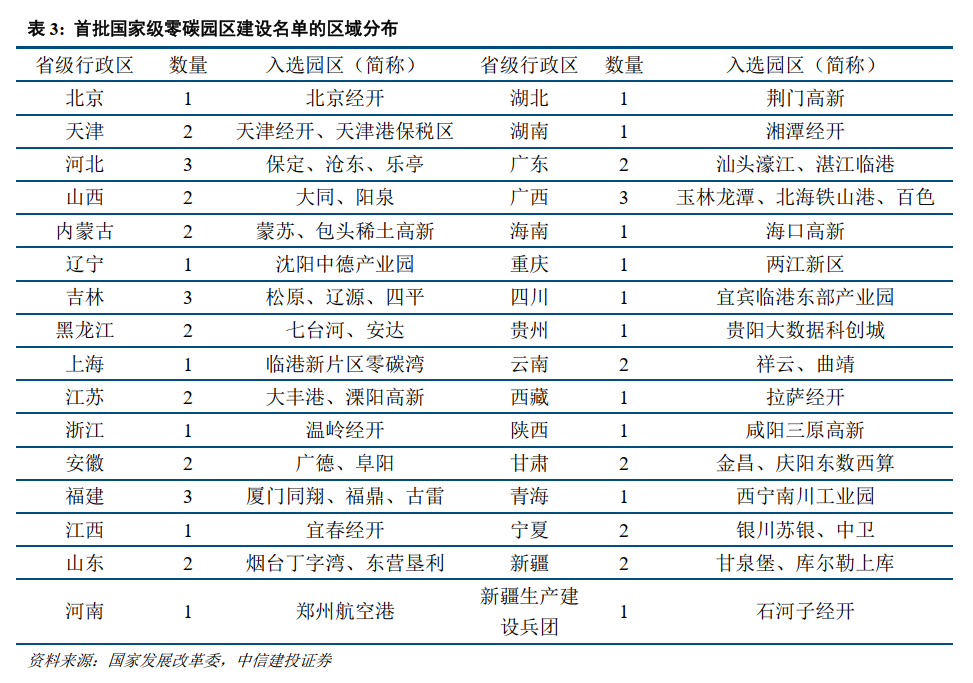
The first batch of lists showed the characteristics of “national coverage and multi-point layout in key provinces”. Hebei, Fujian, Jilin, and Guangxi each have 3 parks; Tianjin, Shanxi, Inner Mongolia, Heilongjiang, Jiangsu, Anhui, Shandong, Guangdong, Yunnan, Gansu, Ningxia, and Xinjiang each have 1. The park type is mainly a “park within a park”, with a few being created as a whole, which means that construction boundaries generally focus on industrial zones that meet the conditions, rather than incorporating the entire original development zone at once.
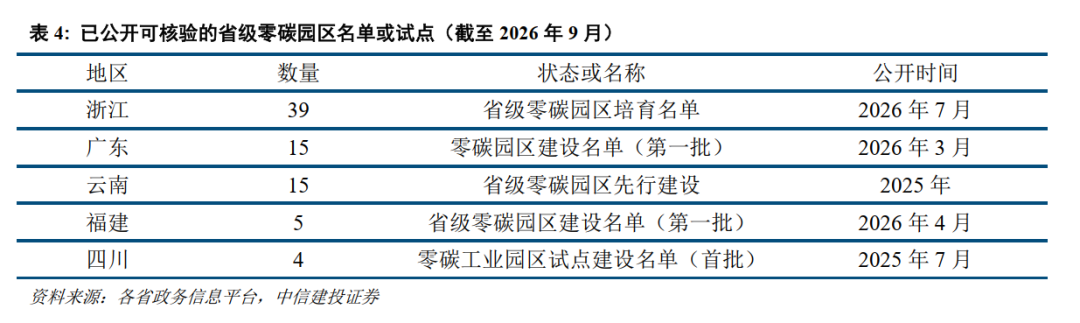
There is no nationally unified “provincial zero carbon park” certification scale or summary list at the provincial level: different regions use different names such as “zero carbon park,” “near zero carbon park,” “zero carbon industrial park pilot project,” and “cultivation list,” and the statistical status of construction, cultivation, certification, and inspection is not the same, and cannot be simply added to the 52 national lists. Take the list that has been made public as of September 2026 and can be verified by the issuing department. There are 39 in Zhejiang, 15 in Guangdong, 15 in Yunnan, 5 in Fujian, and 4 in Sichuan, for a total of at least 78 provincial construction or cultivation units.
2.2 Analysis of zero-carbon park construction and transformation
2.2.1 Analysis of zero-carbon park construction and transformation requirements
2.2.1.1 Zero-carbon park construction standards
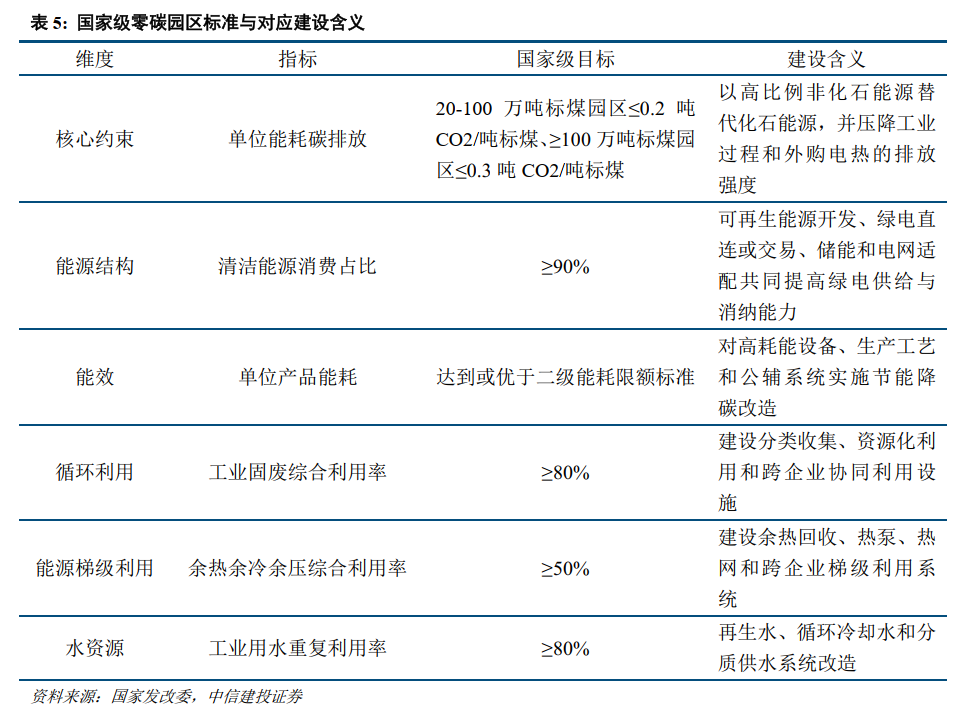
The construction of a zero-carbon park is not just about building a few photovoltaics and energy storage projects. Instead, it aims to significantly reduce the overall carbon emission intensity of the park and carry out systematic transformation of energy supply, industrial production, and resource utilization. National zero-carbon parks use “carbon emissions per unit of energy consumption” as the core acceptance constraint: parks with an annual comprehensive energy consumption of 200,000 to 1 million tons of standard coal should not exceed 0.2 tons of carbon dioxide/ton of standard coal; parks with annual comprehensive energy consumption of not less than 1 million tons of standard coal should not be higher than 0.3 tons of carbon dioxide/ton of standard coal. In principle, parks that do not meet this core target are not allowed to apply for inspection. The park's carbon emission accounting covers direct and indirect carbon dioxide emissions from energy activities and industrial production processes. Therefore, simply purchasing a green certificate or constructing a single photovoltaic project is not enough to prove that the park as a whole meets the zero carbon requirements.
Focusing on the core carbon intensity target, the national index system further puts forward guidance requirements from the three aspects of energy structure, energy efficiency, and recycling: in principle, the proportion of clean energy consumption should not be less than 90%, the energy consumption per unit product in the park should meet or exceed the second-level energy consumption limit standard, the comprehensive utilization rate of industrial solid waste, the comprehensive utilization rate of waste heat and waste pressure, and the reuse rate of industrial water have reached 80%, 50%, and 80%, respectively. This means that the construction of a zero-carbon park focuses not only on increasing the supply of green electricity, but also on reducing pressure production and energy consumption in public and auxiliary systems, recycling waste heat from surplus energy, and raising the level of recycling of water resources and solid waste.
On the energy supply side, direct connection to green electricity is an important path to achieve a high proportion of green electricity consumption. According to national policy, direct green power connection refers to a model where new energy power sources such as wind power and photovoltaics are supplied to users through dedicated lines and the electricity is physically traceable. For high-capacity parks or parks facing export carbon footprint requirements, the significance of direct green power connection is not only about obtaining green electricity certificates, but also about simultaneously constructing new energy power sources, dedicated lines, energy storage regulation, and operation management mechanisms, so that parks can steadily consume traceable green electricity.
The relationship between national standards and provincial standards is a combination of a “unified bottom line and a path adapted to local conditions”. The national index system focuses on stipulating the inspection results, that is, the carbon intensity, clean energy, and resource utilization levels that the park should eventually achieve; provincial policies usually combine local energy endowments, industry types, and construction foundations to further refine implementation paths. For example, Sichuan incorporated zero-carbon management agencies, enterprise carbon accounting, green power direct supply, source grid storage, smart microgrid, and energy storage allocation into the evaluation system; Yunnan added characteristic indicators on the basis of the target national indicators; and Jiangsu promoted construction in six areas: energy efficiency, production process, energy supply, infrastructure, resource recycling, and digital intelligent management. Therefore, provincial policies can answer “exactly how to build” parks, but they cannot replace national-level inspection restrictions on core carbon intensity indicators.
2.2.1.2 Renewal and transformation requirements corresponding to standards
The construction and transformation of zero-carbon parks can be summarized into two main lines: one is to build a “source-grid-load-storage” integrated energy system around direct connection to green electricity and a high proportion of new energy consumption; the other is to implement low-carbon transformation of existing production, public support, and resource utilization systems. The former addresses “where does energy come from and how to deliver it stably to the park”, while the latter addresses “how to reduce emissions from existing energy and production processes”. Both require metering, tracking, scheduling, and accounting support from energy carbon data platforms.
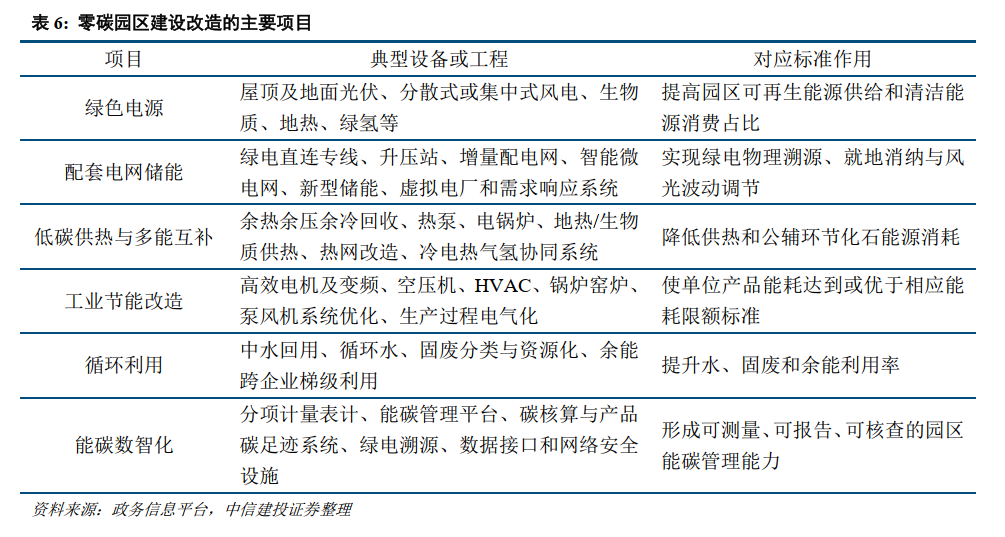
It is important to note that not all of the above projects require complete configuration for every park. Resource-based and high-capacity parks usually focus on external renewable energy bases, direct green power connections, energy storage regulation, and process decarbonization; manufacturing parks are more likely to focus on distributed photovoltaics, public and auxiliary systems, green power trading, and energy carbon management; ports, logistics, and port parks also require superposition of shore power, charging and switching, low-carbon transportation, and port energy facilities. The construction plan should form a “one garden, one policy” project list based on carbon emission baselines, load curves, renewable resources, heating methods, and leading industrial processes.
2.2.2 Estimation of capital requirements for zero-carbon parks
Of the first batch of 52 national zero-carbon parks, most parks have yet to disclose a complete construction project schedule that can be verified item by item. Some parks have announced planned investment amounts, but there is a big difference in caliber. Overall, zero carbon park investment can be divided into two parts: industrial investment and zero carbon investment. Industrial investment is the park's own industry, mainly low-carbon industries such as new energy vehicles and wind energy storage. It may also include emerging industries such as data centers, or transformation industries such as chemicals. Zero-carbon investments include the upgrading of various infrastructure and equipment to achieve zero-carbon goals. At present, 22 national-level zero-carbon parks have announced an estimated investment amount of over 700 billion yuan of various calibers.
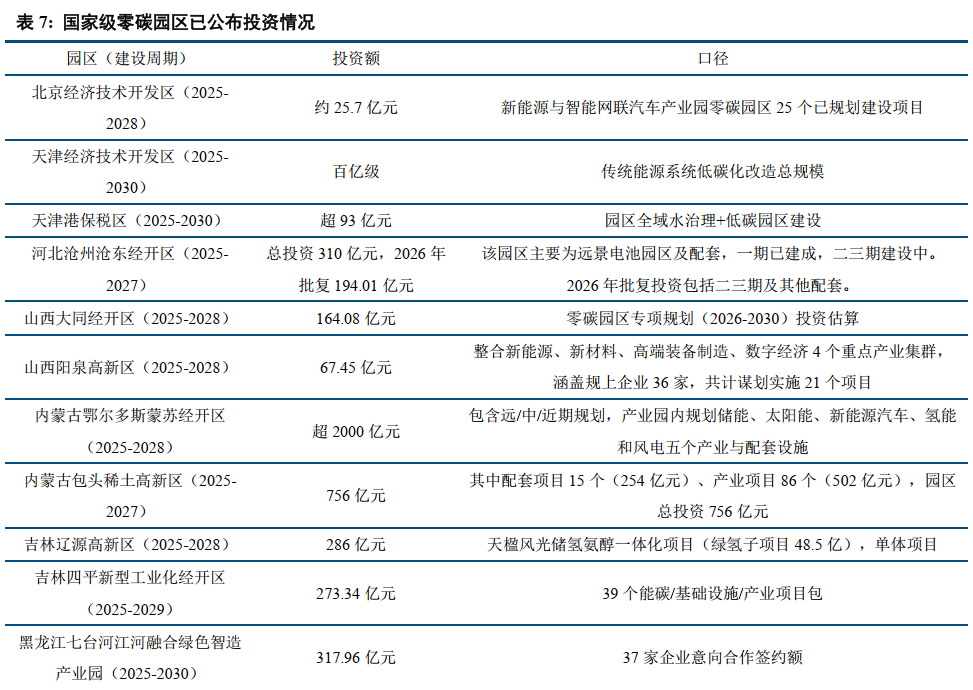
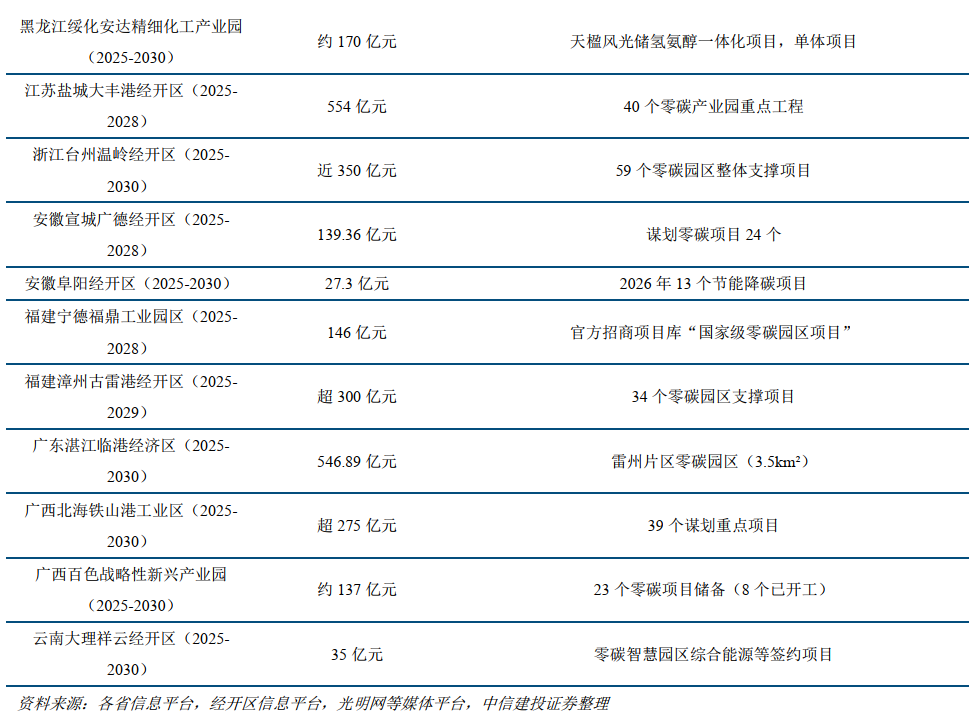
Of all our investments, we are focusing more on increasing investments that serve our zero-carbon goals. The Cangdong National Zero Carbon Park announced a detailed list of investment projects. We defined the zero carbon investment as “energy, energy efficiency, recycling, energy and carbon management projects directly built by the park to achieve zero carbon goals, as well as park support and infrastructure that serve these goals.” Industrial production expansion projects such as battery manufacturing are not included. The purpose of this caliber is to estimate the engineering investment required for the zero-carbon construction of the park. It is not equivalent to the entire investment of the park, nor is it equivalent to the cost of reducing emissions throughout the life cycle of an enterprise's individual products.
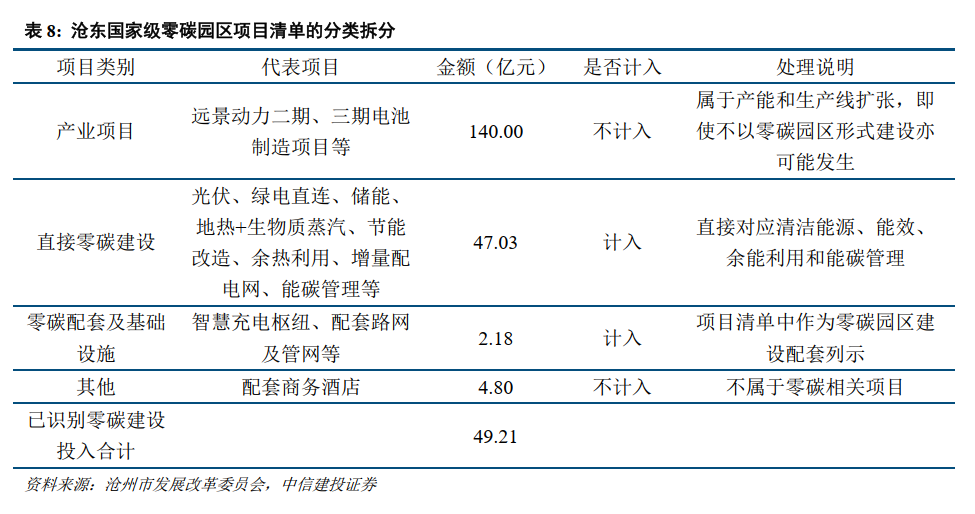
Cangdong's 2026 zero carbon park project list consists of 25 projects, with a total investment of 19.401 billion yuan. Among them, the identified direct zero-carbon construction investment was 4.703 billion yuan, and zero-carbon support and infrastructure investment was 218 million yuan, for a total of 4.921 billion yuan. Considering that the overall investment in zero-carbon parks (industry+zero-carbon transformation) has already been announced, the Cangdong Zero Carbon Park is at the midstream level. Based on this, it can be estimated that the zero carbon transformation investment scale corresponding to 52 zero-carbon parks is at the level of 100 billion dollars.
3 Sustainable financial instruments to support the development of zero-carbon parks
A zero-carbon park is not a one-time investment project completed by a single entity; its funding source should match the asset attributes, construction entity, and debt repayment cash flow. Park road networks, reclaimed water, public energy carbon management platforms, etc. have strong public attributes, and are usually coordinated by local governments or park platforms; energy assets such as new energy power sources, direct green power connections, energy storage and distribution grids can be invested and operated by power generation companies, power grid companies, or integrated energy service providers; energy saving transformation, waste heat utilization, and electrification transformation of enterprises are mainly carried out by energy companies. The national policy on zero-carbon park construction also clearly supports the participation of various types of actors such as local governments, park enterprises, power generation companies, power grid companies, and integrated energy service providers, and suggests that construction can be supported through existing funding channels, local government special bonds, medium- and long-term credit from policy banks, and eligible corporate bonds.
Funding sources for different construction projects depend on the public nature of assets, cash flow stability, and technical risk. Energy assets such as direct green power connections, new energy, energy storage, and microgrids can be allocated capital, green credit or project financing based on project income by professional operators; public supporting benefits such as road networks, recycled water, and public energy carbon platforms are weak, suitable for financial capital, eligible special debt, and policy medium- to long-term capital; enterprise energy saving transformation mainly uses energy efficiency revenue as a source of repayment, suitable for green loans, equipment renewal loans, financial leases, or contract energy management. Projects that are not yet mature in technology and business models, such as hydrogen energy or long-term energy storage, require industrial capital, industrial funds, or risk sharing arrangements.
Sustainable finance is the most direct and systematic external funding channel for the construction of zero-carbon parks. Currently, it has formed a multi-level engineering system of claims, equity and equity, and environmental rights. Since the People's Bank of China and seven other departments issued the “Guiding Opinions on Establishing a Green Finance System” in 2016, China's green finance system framework has continued to improve; the “Catalogue of Green Finance Support Projects (2025 Edition)” unifies the project identification standards for green loans, green bonds, etc., and in 2025, the Central Office and the State Administration issued “Opinions on Promoting Green and Low-carbon Transformation and Strengthening the Construction of the National Carbon Market” to further incorporate carbon finance into the top-level system agenda. Implemented in the zero-carbon park scenario, debt instruments include green credit and ESG bonds, which are mainly used to match large and long-term project capital during construction; non-debt instruments include sovereign funds, financial leases, and REITs, which are mainly used to supplement capital, cover equipment investment, and revitalize existing assets.
Judging from policy deployment, financial support for zero-carbon parks has entered the stage of institutionalization and commercialization. The “Notice on Launching Zero Carbon Park Construction” of three departments including the National Development and Reform Commission clearly states that zero carbon park construction can be supported through existing funding channels, local government special bonds, medium- and long-term bank loans, and eligible corporate bonds; in March 2025, the Jiangsu Branch of the People's Bank of China, in conjunction with the Provincial Development and Reform Commission, the Provincial Department of Industry and Information Technology, and the Provincial Department of Finance issued the “Implementation Plan for Financial Support for the High-Quality Development of Zero Carbon Parks”, which became the first provincial level special policy for financial support for zero carbon parks in the country; the “Shanghai Zero Carbon Park Construction Further Work Plan” issued in September 2026 requirements Guide financial institutions to improve accurate investment mechanisms and innovate green finance products. The certainty of green infrastructure investment in zero-carbon parks, the cash flow attributes of assets, and the accounting basis of carbon assets together form the basis for a scenario where sustainable financial instruments are deeply involved.
3.1 Debt instruments
Debt instruments are the most important source of funding during the construction of zero-carbon parks. Zero-carbon park investments are mainly energy infrastructure, energy-saving transformation, and public supporting projects. They have the characteristics of large capital expenditure, long payback periods, and relatively stable cash flow, and are most compatible with the risk-return characteristics of debt financing. From a structural perspective, green credit occupies the absolute majority of China's green finance system and is the main capital for park projects and equipment transformation; green bonds, transformation bonds, and sustainable development-related bonds provide medium- to long-term direct financing for park platforms and large enterprises; policy arrangements such as carbon emission reduction support tools and financial interest rates have further reduced actual financing costs in key areas.
3.1.1 Green Credit: the mainstay of the green finance system
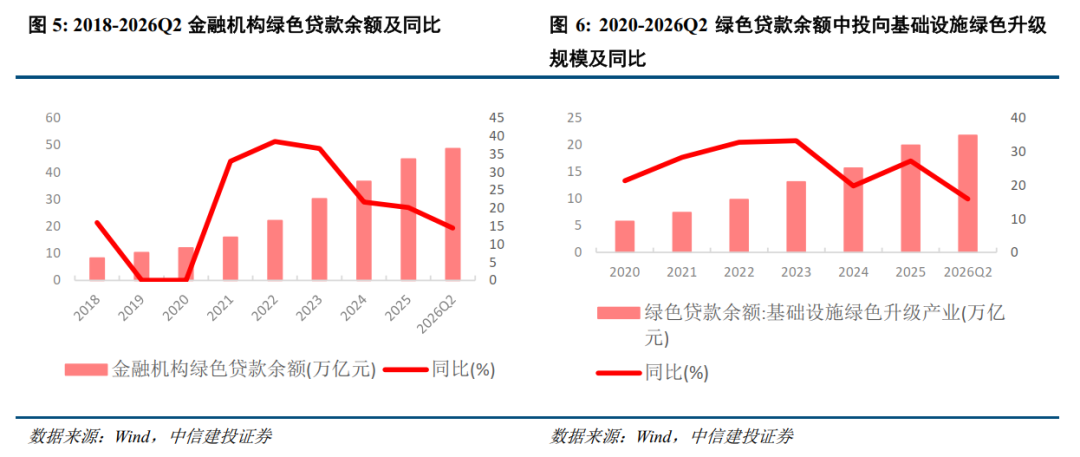
The scale of green credit has continued to grow at a high rate and has become the absolute mainstay of the green finance system. Statistics from the People's Bank of China show that at the end of the second quarter of 2026, the balance of green loans in local and foreign currencies was 48.63 trillion yuan, up 14.5% year on year, and increased by 3.82 trillion yuan in the first half of the year. The growth rate was significantly higher than the overall growth rate of 5.2% of RMB loans during the same period. Looking at the investment structure, green infrastructure upgrades and clean energy industry loans account for the highest share. This is highly consistent with the investment direction of zero-carbon park energy supply system transformation and green public infrastructure upgrading. Naturally, the park's green power connection, energy storage, microgrid, and energy-saving transformation projects fall within the scope of green credit support.
In terms of financing costs, with the support of the People's Bank of China's carbon emission reduction tools, the interest rate advantage of green credit is obvious. The Carbon Emission Reduction Support Tool is a financial policy tool created by the People's Bank of China in November 2021. It aims to provide low-cost capital to financial institutions through a “loan first, then loan” mechanism to guide them to invest in the fields of clean energy, energy saving and environmental protection, and carbon reduction technology. The carbon reduction tool initially provides financial support to financial institutions at 60% of the loan principal. The interest rate is 1.75%, the term is 1 year, and it can be extended 2 times. After many policy extensions and interest rate cuts, the one-year reloan interest rate has now been lowered to 1.25%. In January 2026, the People's Bank of China decided to include projects with direct carbon emission reduction effects, such as energy-saving transformation, green upgrading, and green and low-carbon energy transformation, into the field of support tools to reduce carbon emissions, further expanding policy coverage. At the same time, the annual operating volume in 2026 will not exceed 800 billion yuan, which is expected to leverage trillion-level green credit.
Jiangsu established a policy framework for the country's first provincial financial support zero-carbon park and pioneered the implementation of products. In March 2025, the Jiangsu branch of the People's Bank of China, together with the Provincial Development and Reform Commission, the Provincial Department of Industry and Information Technology, and the Provincial Department of Finance issued the “Implementation Plan for Financial Support for the High-Quality Development of Zero Carbon Parks”. The plan is the first provincial special plan to finance zero carbon parks in the country and officially launched the “Zero Carbon Park Loan” product. The core innovation is to include the park's green electricity consumption ratio, carbon emission intensity, and carbon emission reduction into bank credit approval and risk management grounds, and encourage carbon asset pledges and syndicated loans. Subsequently, the Bank of Nanjing introduced a special work plan to support the construction of zero-carbon parks, and has signed green and low-carbon strategic cooperation agreements with nearly 30 parks; by the end of 2025, loan balances in fields related to zero-carbon park construction had exceeded 19 billion yuan. Among them, more than 1.3 billion yuan of green credit was provided for pilot projects in Yancheng Sheyang Port, Binhai Port, Dafeng Port, etc., including Yuguang complementary photovoltaic project loans, sustainable development linked loans, green agricultural carbon remittance loans, etc.; the Bank of Jiangsu implemented the first carbon account-linked loan in Yancheng Zero Carbon Industrial Park, implementing differentiated pricing based on corporate carbon performance, which became a representative case of combining the linked mechanism with the park's carbon management.
In the future, green credit is expected to evolve towards carbon account drivers and overall park solutions. With the improvement of systems such as carbon pledge and carbon repurchase, environmental equity pledge financing is expected to be scaled up. The credit foundation extends from individual projects to the carbon accounts of parks or enterprises. Furthermore, the park's overall integrated financial services are expected to account for a larger proportion. For example, Industrial Bank has launched a “Finance Smart+Financing” comprehensive service plan for the construction of low-carbon and zero-carbon parks. The Bank of Nanjing's 2026 semi-annual report revealed that it has implemented the first batch of special financial service plans for zero-carbon parks in Jiangsu Province. The services cover the entire process of park planning, construction and operation, and provide comprehensive financial support for carbon reduction, equipment renewal, and energy saving technology reform.
3.1.2 ESG bonds: an important source of financing for green finance
China's ESG bond market is large and is an important source of financing for green finance. According to Wind statistics, as of the end of September 2026, there were 4,277 ESG bonds in existence, with a survival scale of over 6 trillion yuan. The funds raised by green bonds are invested in fields such as clean energy, green transportation, and pollution control, and are highly compatible with the zero carbon park project lineage.
The types of bonds have formed a complete lineage of “green bonds+transformation bonds+sustainability-linked bonds”. Carbon neutral bonds in green bonds raise funds specifically for projects with carbon emission reduction benefits; transformation bonds specifically serve the low-carbon transformation of high-carbon industries; the coupon interest rate of sustainability-linked bonds (SLB) is linked to key performance indicators (KPIs) such as carbon reduction and energy consumption intensity. Overall, various types of ESG bonds can provide financing support for the construction of zero-carbon parks. For park builders, ESG bonds provide medium- to long-term, batch direct financing channels. The interest rate for issuing ESG bonds is basically the same or slightly lower than the same period credit bonds, and the investment of capital raised can be linked to green industry catalogues such as the “Catalogue of Green Finance Support Projects (2025 Edition)”. In November 2025, the General Office of the Ministry of Industry and Information Technology and the General Office of the People's Bank of China issued the “Notice on Making Good Use of Green Finance Policies to Support the Construction of Green Factories”, which supports eligible enterprises to issue green bonds and transformation bonds, focusing on supporting national green factories to implement investments using green and low-carbon technologies specified in the “Green Finance Support Project Catalogue (2025 Edition)”. Enterprises in the park that have been awarded national green factories obtain a direct policy basis from this.
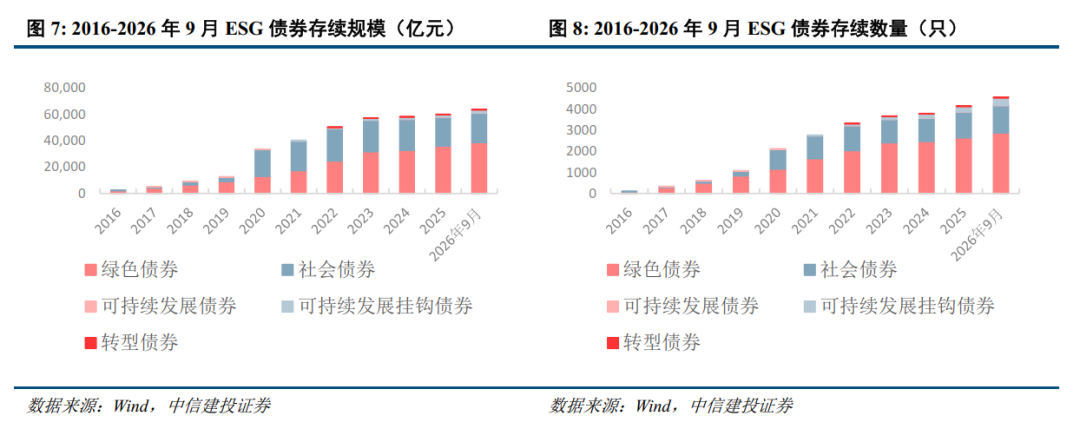
Currently, the green industry is quite mature for financing through ESG bonds. There are already quite mature examples of green bonds supporting related industries. Since 2026, Ningde Times has issued green technology innovation bonds on a rolling basis (the first 5 billion yuan, multiple installments throughout the year). The green projects disclosed in the prospectus are the four major bases in Fuding, Liyang, and Yibin. Among them, the parks belonging to Fuding, Liyang, and Yibin (Fuding Industrial Park, Liyang High-tech Zone, and Yibin Lingang East Industrial Park) have also been selected for the first batch of national zero-carbon parks. The funds are used for the daily operation of affiliated lithium-ion battery production projects. With the development of zero-carbon parks, ESG bonds are also expected to provide financial support for the zero-carbon park industry and low-carbon transformation. Compared with green credit, bond financing is larger in size and has a longer term, and is more suitable for meeting capital requirements at the park platform level.
3.2 Non-debt instruments
Non-debt instruments address capital constraints and asset revitalization issues in zero-carbon park construction. Zero-carbon park projects have a large investment scale and a long payback period. Simply relying on debt financing will drive up the balance ratio and increase the risk of refinancing. Looking at different types of non-debt instruments, sovereign funds use equity investment to reduce capital gaps, financial leases rely on equipment asset credit to broaden financing boundaries, and REITs provide standardized exit channels for built energy and park infrastructure.
3.2.1 Sovereign funds (national development funds, local special funds, etc.)
Investments within the central budget provide a supplementary source of capital for zero-carbon parks. In September 2025, the National Development and Reform Commission formulated the “Special Administrative Measures on Investment in Energy Conservation and Carbon Reduction within the Central Budget”. This special project supports low-carbon, zero-carbon, and carbon-negative demonstration projects. The project support ratio is 20% of the approved total investment. The project clearly proposes projects such as energy supply facility construction, infrastructure transformation, and process carbon reduction transformation to support zero-carbon parks and zero-carbon transportation corridors to achieve near-zero carbon goals. At the same time, the project also supports basic capacity building such as carbon emission measurement, statistics, accounting, and monitoring. The specially arranged investment funds within the central budget are carried out in the form of direct investment, capital injection, investment subsidies, etc. according to the actual situation.
National green theme funds have also become an important source of capital for equity investment. The National Green Development Fund Co., Ltd. was established in July 2020, with an initial scale of 88.5 billion yuan. The Ministry of Finance and 11 provinces and cities in the Yangtze River Economic Belt made financial contributions and attracted social capital participation, focusing on environmental protection and pollution prevention, ecological restoration, energy resource conservation and utilization, green transportation, and clean energy. By the end of 2025, the fund had completed 83 investment decisions, with a decision amount of 41,753 billion yuan, of which about 20 billion yuan was used for sub-fund investments. The leveraging and amplification effects of financial capital were obvious. Furthermore, the 2026 government work report and the “15th Five-Year Plan of Action” issued by the State Council clearly state that a national low-carbon transition fund should be established and more commercial capital should be leveraged to enter low-carbon transformation projects.
Collaboration between local special funds and zero-carbon park construction is also expected to gradually come to fruition. The “Shanghai Zero Carbon Park Construction Work Plan” issued in September 2026 proposes to coordinate relevant funds at the national and municipal levels to support technology integration and demonstration projects such as energy-saving transformation, renewable energy development and utilization, and smart energy carbon management in the park.
Looking forward to the future, government funds are expected to expand from investment industries to investment in parks and infrastructure. As the first batch of zero-carbon parks enter the project implementation period, direct green power connection, energy storage, and microgrid projects gradually have stable cash flow, suitable for funds to intervene in the form of equity, etc., to play a capital supply function that leverages social capital; the linkage between national funds and local zero-carbon park special funds is expected to be closer, sinking to the park project level through sub-funds and joint investment methods to improve the efficiency of the recycling of financial resources.
3.2.2 Financial leasing: Highly compatible with zero-carbon park investment
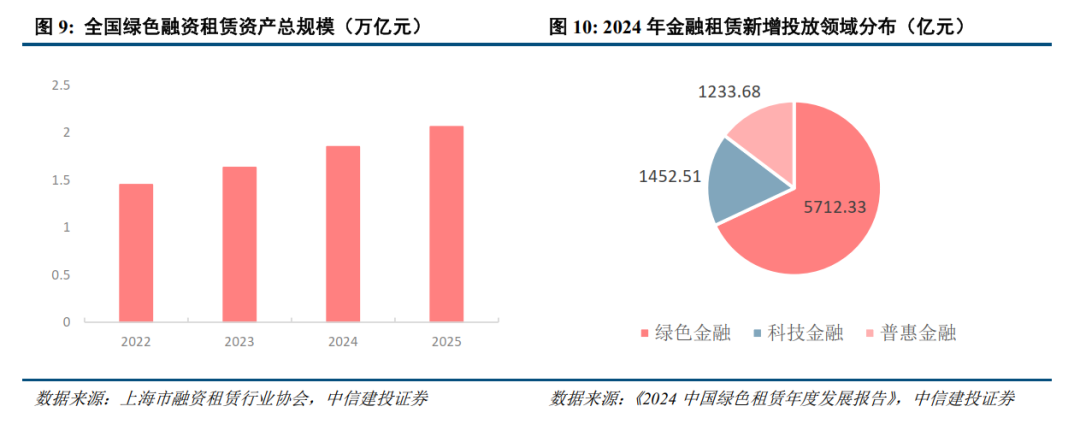
Green leasing has become the core engine of growth in the leasing industry and is highly compatible with equipment-intensive investment in zero-carbon parks. By the end of 2025, the country's total green leasing assets reached 2.06 trillion yuan, an increase of 11.7% over the previous year. Judging from 2024 data, green financial leasing has become the industry's biggest incremental direction. The “financing+melting” characteristics of financial leasing enable it to cover almost all categories of zero-carbon transformation equipment such as distributed photovoltaics, industrial and commercial energy storage, charging piles, waste heat utilization, high-efficiency motors and air conditioning and air compressor system updates: leasing companies hold ownership of the equipment, and tenants pay rent in installments, significantly reducing the one-time capital expenses of park enterprises.
Leading financial leasing companies have formed a batch service model for distributed energy in the park, which can directly connect with the needs of zero-carbon parks. In November 2021, CITIC Financial Leasing and three wholly-owned subsidiaries under BOE Energy Technology launched a 120 million yuan industrial and commercial rooftop distributed photovoltaic financial leasing project; CMB Financial Leasing's “Distributed PV Leasing Solution - Centralized Credit Enhancement Small Order Business Model” was selected as the Shanghai Banking Association's Outstanding Work Achievement in 2023; the “1+N” product of the “1+N” industrial and commercial distributed power station was selected as the first National Green Leasing Innovation Case of the Year and set up a distributed photovoltaic and energy storage business innovation research group. At the same time, leasing companies use equipment assets as links and can work with integrated energy service providers to provide integrated renewable energy solutions for the park.
3.2.3 REITs: An important way to revitalize existing assets and return to early capital
The public REITs market has entered the stage of normalized issuance, and the types of green assets continue to expand. In July 2024, the National Development and Reform Commission issued the “Notice on Comprehensively Promoting the Standardized Issuance of Real Estate Investment Trust Fund Projects in the Infrastructure Sector”, which promotes the transformation of REITs issuance from pilot to normalization and simplified application processes, and opens up institutional channels for the securitization of park new energy assets and industrial park properties.
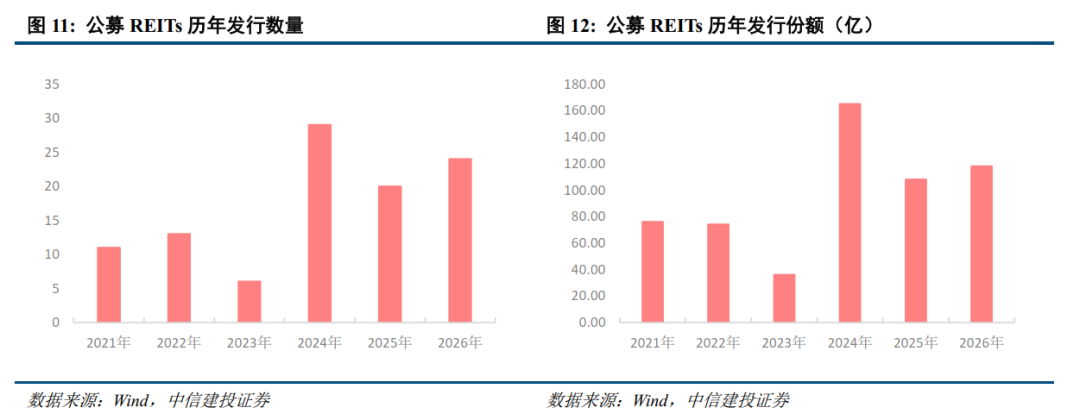
New energy REITs are moving from pilot to batch supply. In March 2023, CITIC Construction Investment China Power Investment New Energy REITs and China Aviation Jingneng International Energy REITs were listed in the first batch, achieving a breakthrough in new energy public funding REITs; since then, Harvest China Power Construction Clean Energy REIT and Huaxia TBEA New Energy REIT have been launched one after another, and asset types such as wind power, photovoltaics, hydropower, etc. have been continuously enriched; since 2026, Huatai Three Gorges New Energy REIT (distribution scale of 4.07 billion yuan) and China Aviation China Nuclear Power Investment New Energy REIT (distribution scale of 2,324 billion yuan) have completed fundraising. Gorge Group, Large power state-owned enterprises such as CNNC, industrial park REITs, and new asset REITs such as data centers are also expanding simultaneously.
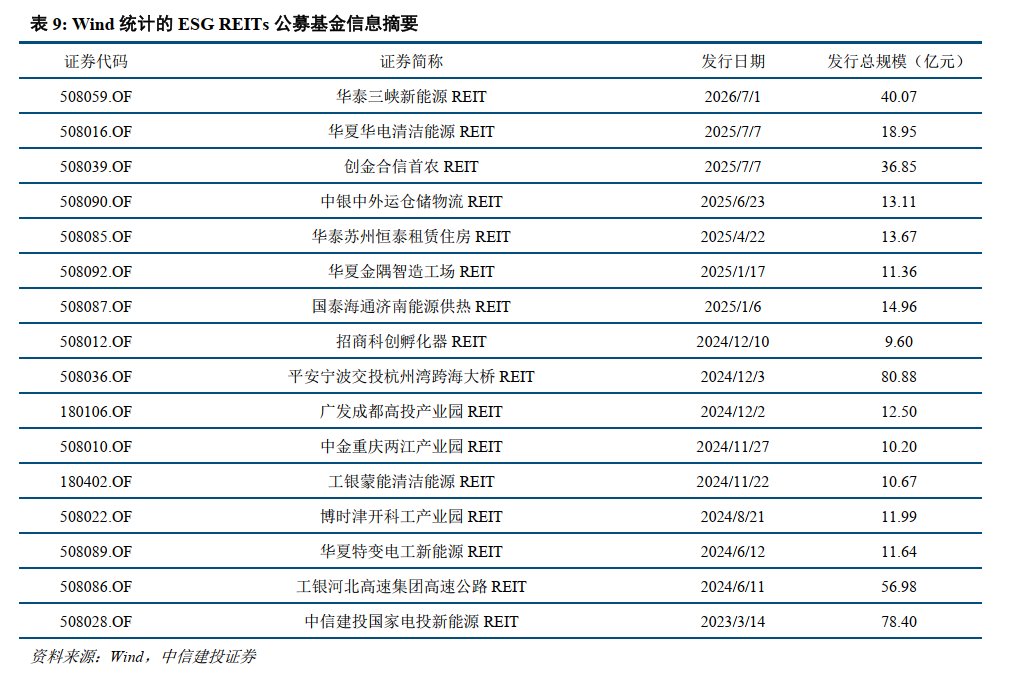
New Energy REITs have verified the complete closed loop of “investment, finance, construction and management withdrawal” of green power assets. Industrial Park REITs provide a funding mechanism for park platforms to revitalize their stock and feed back zero-carbon transformation. The underlying assets of the first batch of new energy REITs were offshore wind power and photovoltaic power plants. After listing, the operating stability and level of dividends were recognized by the market. The single issuance scale of the new energy REITs in 2026 was significantly larger than the new energy REITs issued in 2024-2025. For zero-carbon parks, the significance of REITs is to provide standardized exit channels for new energy assets. Industrial park REITs such as Zhangjiang, Lingang, and Suzhou Industrial Park have been listed one after another. By selling mature properties, park developers have recovered capital and invested in new parks and green transformation, forming a rolling model of “development - operation - securitization - reinvestment”. In the construction of a zero-carbon park, standard plants, R&D buildings, and supporting energy facilities held by the park platform can all be included in the scope of REITs reserve assets, and together with new energy REITs, they form two paths to revitalize the park's stock.
3.3 Themed investment opportunities brought by zero-carbon parks
3.3.1 Energy system transformation
A green power direct connection project supporting the construction of new loads is a prerequisite for zero-carbon parks to meet standards. Electricity access, distribution network transformation, and energy storage projects are the most definitive investment directions during the construction period. In terms of policy, according to the national zero-carbon park assessment rules, the annual comprehensive energy consumption of 20-1,000,000 tons of standard coal parks consumes less than 0.2 tons of carbon dioxide per unit, and the limit for parks that consume more than one million tons of standard coal is 0.3 tons of CO2/ ton of standard coal; in principle, the direct supply ratio of green electricity after completion is not less than 50% of the park's electricity consumption, and the share of clean energy consumption is aimed at more than 90%. The mandatory requirements of the policy bring definitive investment requirements for green power sources and supporting facilities.
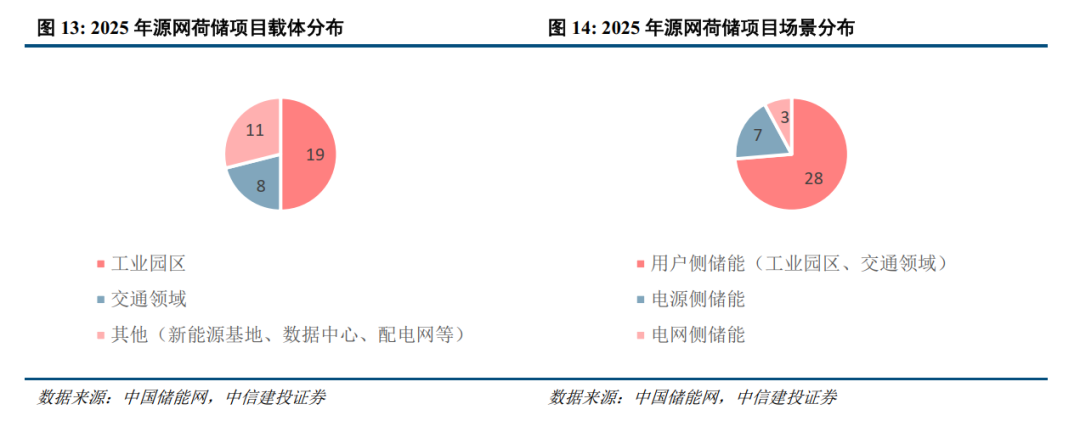
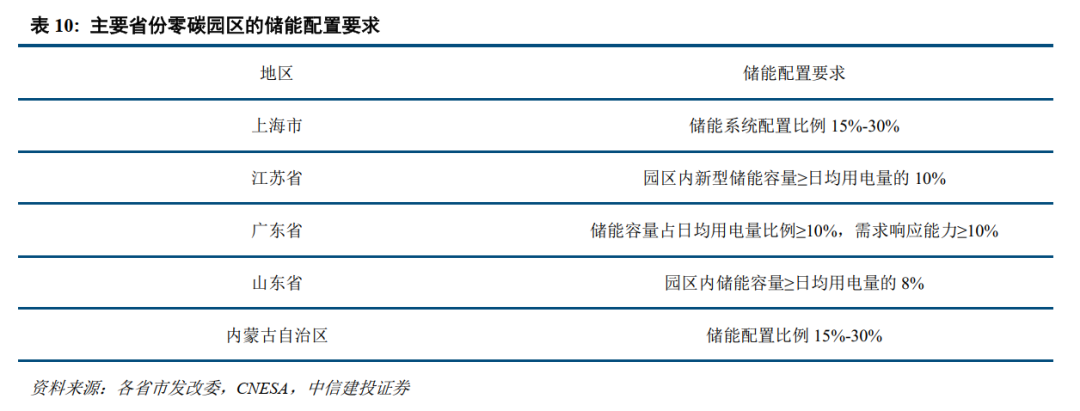
Various provinces have issued documents to restrict energy storage allocations in zero-carbon parks, and source network cargo storage is fully implemented in zero-carbon parks. Shanghai, Jiangsu and other places are demanding that provincial zero-carbon parks allocate a certain percentage of energy storage to promote consumption. Judging from the construction of source network load storage systems, a total of 38 integrated source network load storage projects have made actual progress in 2025. According to the distribution of energy storage network project scenarios in China, industrial parks are one of the core carriers of integrated source network load storage implementation. The number of integrated source network load storage projects in the industrial park scenario ranks first, with a total of 19, accounting for 50%; from the perspective of energy storage applications, the user side is currently the main focus of source network load storage construction, occupying an absolute dominant position, with a total of 28, accounting for 74%, mainly corresponding to industrial parks and transportation projects.
3.3.2 Low-carbon transformation of equipment/technology
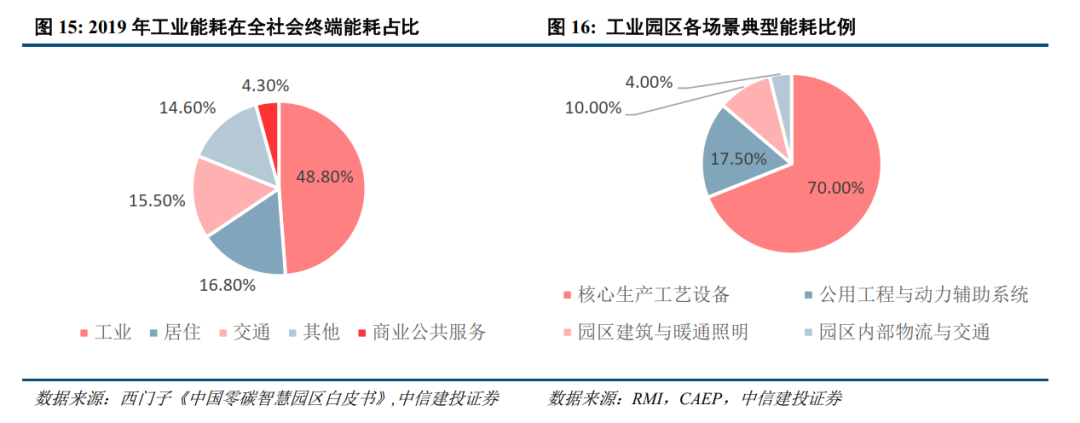
Energy consumption in industrial parks is mainly divided into four categories. Production equipment accounts for the highest proportion of energy consumption. We need to focus on investment opportunities brought about by related equipment upgrades. The first is the energy consumption of production equipment, which accounts for 60%-80% of the energy consumption of the park, including high-energy industrial boilers, kilns, compressors, motor drives and various production lines; the second is utility engineering and power assistance systems that support general power, including air compressors, industrial refrigeration and heating networks; the third is park architecture and HVAC and lighting, covering HVAC and lighting in factories and office buildings; the fourth is logistics and transportation within the park, involving mobile energy use scenarios such as heavy trucks, forklifts and AGVs in the factory area. A panoramic view of refined carbon management for chemical energy.
High-energy industries can reduce carbon emissions through advances in technology or equipment. According to information from the Chinese Academy of Information and Communications Technology, petrochemical enterprises in the Ningbo Petrochemical Economic and Technological Development Zone are speeding up energy saving and carbon reduction transformation. By introducing regenerative oil-liquid phase selective hydrodeolefin technology (FHDO) to replace high-risk and high-cost clay adsorption processes, waste white clay is reduced by more than 1,000 tons per year and carbon emissions are reduced by 1,800 tons; using “ultrasonic+centrifugal dehydration” technology to treat oil sludge, the total annual sludge production volume is reduced by more than 10,000 tons, and carbon emissions are reduced by more than 4,000 tons. At the end of production, carbon management can also be carried out, and technologies such as CCUS can be used to reduce carbon emissions.
4 Examples of zero-carbon parks at home and abroad
4.1 Domestic practice: Zero Carbon Industrial Park, Mengsu Economic Development Zone, Ordos
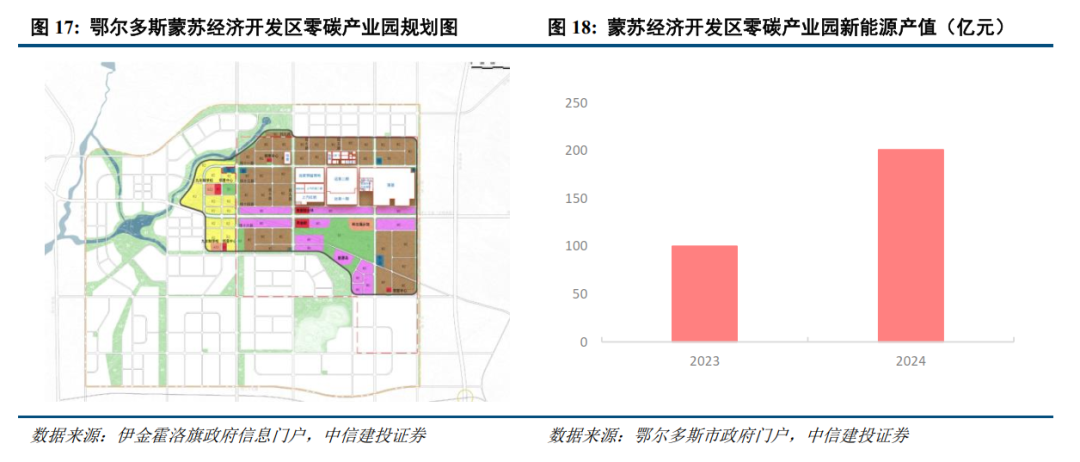
The Zero Carbon Industrial Park in the Mengsu Economic Development Zone in Ordos relies on the advantages of low-cost green electricity integrating wind and solar storage to attract investment. The park was jointly built by the Ordos Municipal Government, the Ekinholoqi Government, and Envision Group. It is the first zero-carbon industrial park in the world. The park has a wind farm within 150 kilometers of the surrounding area, and has built a 385,000 kilowatt integrated wind and solar storage project. It generates about 900 million kilowatts of green electricity per year, and realizes 80% of green electricity spontaneous direct supply and 20% online transactions through microgrids. Cheap and traceable green electricity directly reduces electricity costs for high-capacity manufacturing companies. The output value of the park's new energy industry jumped from about 10 billion yuan in 2023 to 20.09 billion yuan in 2024, and the total industrial output value of the park reached 65.29 billion yuan.
The park extends the industrial chain around green electricity to help transform the industry. The park lays out five zero-carbon industrial chain clusters according to the “Scenery Hydrogen Storage Vehicle”. Projects such as Envision Power Battery, Rongli, Baofeng, and Ningde Era have been launched one after another; the government has prepared and completed a 10 million kilowatt new energy planning plan, set up a green power company in the incremental power distribution area, and set up a net zero industrial environmental service company and carbon footprint accounting platform. According to the plan, the park will consume 10 billion kilowatts of green electricity during the “15th Five-Year Plan” period, which is more than ten times the current level.
4.2 Domestic practice: Yancheng Dafeng Port Zero Carbon Industrial Park
Backed by an offshore wind farm, Dafeng Port is blessed with excellent conditions. Dafeng has 112 kilometers of coastline, 4,844 square kilometers of sea area, and more than 1,000 square kilometers of tidal flats. The average annual wind speed exceeds 7.6 m/s at an altitude of 100 meters offshore, the number of hours of sunshine per year exceeds 2,000 hours, and is rich in wind and solar energy resources. Under superior natural conditions, Yancheng accounts for 46% of the installed scale of offshore wind power in Jiangsu Province, 15% of the country, and 8% of the world. In 2025, the entire Dafeng district will generate more than 10 billion kilowatt-hours of new energy generation, fully meeting the clean energy consumption needs of zero-carbon parks.
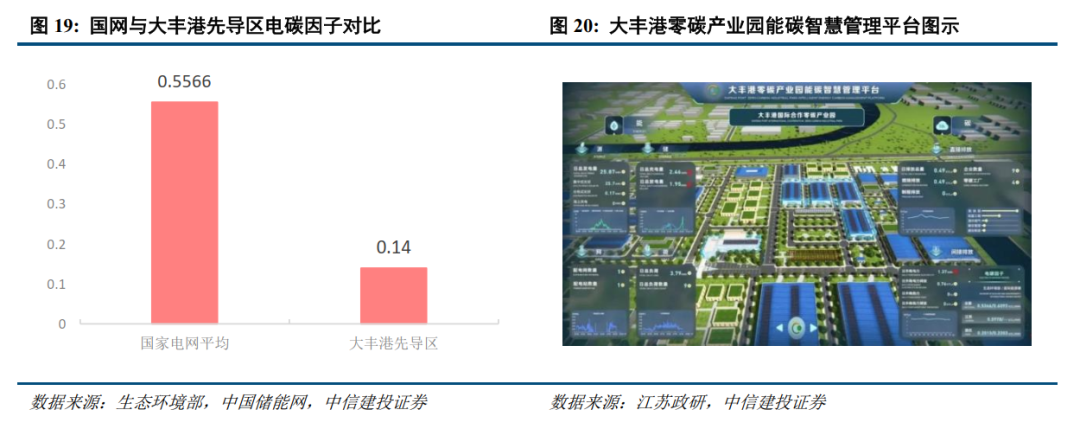
Dafeng Port Zero Carbon Industrial Park helps companies go overseas with traceable direct green electricity. Exporting companies need to be able to verify the source of green electricity, traceable flow direction, and verifiable data. The verifiability of green electricity has become a hard threshold for entering the supply chain. Yancheng Dafeng Port Zero Carbon Industrial Park cooperated with the State Grid Yancheng Power Supply Company to transfer all other loads from the 110 kV Jincheng Substation to remove all other loads from the second section bus line of the station, making the bus a dedicated green power line for 75% of the park's load, built a new “source grid load storage” integrated power system based on the existing national grid architecture and physical traceability, and was approved by the British Standards Institute (BSI); the electric carbon reduction factor was 0.14 tons of carbon dioxide/megawatt-hour, which is lower than the national grid average. Using the green power resource project, the park successfully attracted a number of export-oriented enterprises such as Shanghai Yongjiu, Weina Hongxin, and Shark Bay Technology.
In terms of energy and carbon management, Dafeng Port Zero Carbon Industrial Park also provides intelligent management services. The park uses enterprise energy consumption and carbon emission data as management targets. Through three core functional modules, the park realizes closed-loop management from monitoring and accounting to optimization: the first is a data collection and monitoring module. Through intelligent sensors deployed in wind power stations, substations, and enterprise production workshops, green electricity data and carbon emission data in the enterprise's production process are collected in real time and accurately. The large screen of the platform updates the park's energy and carbon data in real time, showing the energy consumption, carbon emissions and green power usage of each enterprise. The second is a carbon footprint accounting and certification module. The platform has built-in internationally accepted carbon accounting standards, which can automatically match accounting rules according to the enterprise's export destination. Enterprise users only need to log in to the enterprise side and enter basic production data, and the system automatically generates carbon emission inventory reports that meet international standards. Currently, the service has covered 81 regulated enterprises in the Dafeng Port Economic Development Zone. The third is an intelligent control and optimization module. The platform is based on artificial intelligence algorithms, combined with multi-dimensional data such as enterprise electricity demand and product export destinations to provide enterprises with personalized energy efficiency optimization solutions and carbon emission reduction path suggestions.
4.3 Overseas practice: Kalundborg Park, Denmark
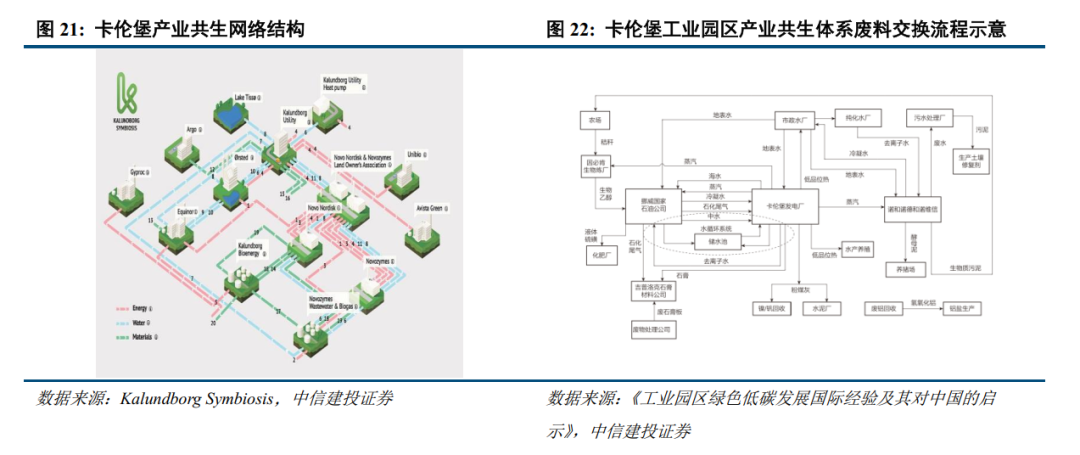
The Kalundborg Park is a typical example of carbon reduction in high-energy industries. It reduces carbon and pollution through industrial cycle symbiosis. The Kalundborg Park is an industrial system composed of four enterprises: a coal power plant, an oil refinery, a pharmaceutical factory, and a gypsum board factory. Among them, the core nodes of the park are the Asnaes (Asnaes) coal power plant and the Statoil (Statoil) refinery. Coal-fired power plants save about 100 million kilowatt-hours of electricity or fuel consumption each year through cogeneration. Based on the Kallenberg Symbiosis System and scientific data, with 2015 as a baseline, companies in the symbiosis system have reduced carbon dioxide emissions by 80%, reducing emissions by 586,000 tons per year. At the same time, waste water and waste are exchanged through the entire industrial system, so pollution reduction and resource collaboration have been achieved.
4.4 Overseas Practice: Saudi Neom—Oxagon Net Zero Industrial City
Saudi Oxagon is a “net zero industrial city” planned and built by NEOM. The plan mainly includes two aspects. First, as an important port hub in the planned Red Sea region, Oxagon will develop a fully automated logistics hub using technical solutions combining renewable energy and intelligent systems. The goal is to make Oxagon an energy and data hub. Therefore, energy self-sufficiency is the core of the port strategy: the port area is designed to make extensive use of on-site renewable energy to support shore power operations and provide cleaner and more resilient energy supply; while making maximum use of renewable energy, support systems to ensure the reliability of power supply are designed, and capacity expansion plans are reserved for the growth in electricity demand.
Second, Oxagon is building the world's first gigawatt-scale green hydrogen project. The project has a total investment of 8.4 billion US dollars, and is developed by NEOM, ACWA Power and Air Products. It is planned to supply about 4GW of wind power and photovoltaic power supplies, and will produce about 600 tons of green hydrogen per day, which will be exported after economic cooperation. The project is expected to be put into operation in 2027. At that time, it can produce up to 1.2 million tons of green ammonia every year to serve the decarbonization of industries that are difficult to reduce emissions around the world, such as heavy industry and transportation. The area where the project is located has excellent scenic resource conditions and is close to the port — equipment and materials can be transported directly by sea during construction, and green ammonia can be directly shipped out of the ship after construction, significantly improving construction and export efficiency.
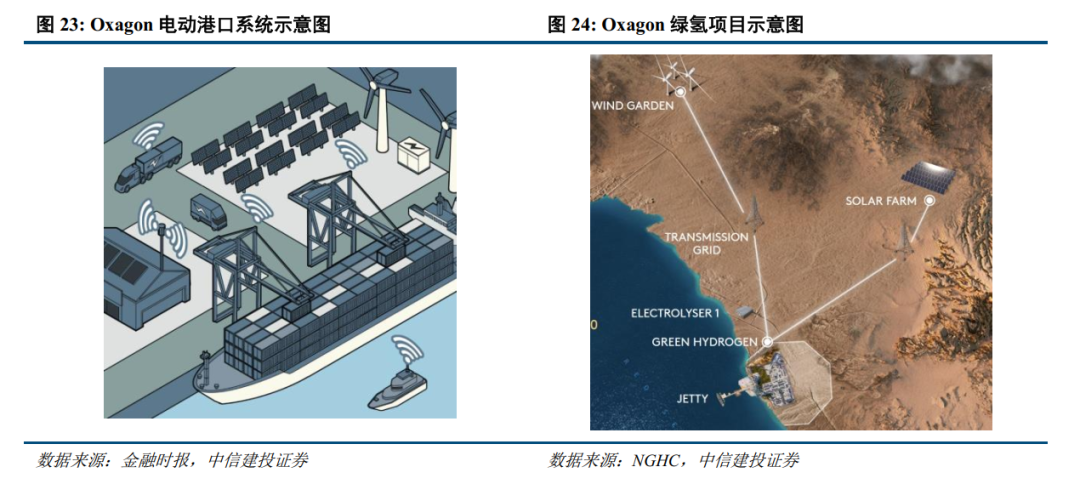
5 Summary and suggestions
Zero-carbon parks are a hub vehicle for moving the “double carbon” goal from a top-level system to physical engineering, and it is also the next systemic driving force for sustainable finance. With the establishment of the standardized system framework in June 2025 (2025) document No. 910, the first batch of 52 national zero-carbon parks was launched in December 2025, and China's zero-carbon park construction officially moved from policy deployment to the practical stage of project implementation and acceptance certification. Looking ahead to the “15th Five-Year Plan”, we put forward the following summary and suggestions from the park side, financial side, and policy side.
Park side: Systematic restructuring to reduce emissions to make carbon reduction a core competitiveness in attracting investment. The national index system uses “carbon emissions per unit of energy consumption” as the core acceptance constraint, and is guided by clean energy consumption accounting for no less than 90%, the comprehensive utilization rate of industrial solid waste 80%, the utilization rate of waste heat and waste cold waste pressure of 50%, and the reuse rate of industrial water of 80%. This means that a zero-carbon park is not a superposition of renewable power projects, but rather a comprehensive system transformation. On the one hand, the park should have a “source-grid-load-storage” integrated energy system with direct connection to green electricity as the key path, and on the other hand, it is necessary to upgrade production, public assistance, and resource utilization in a low-carbon manner. Therefore, we recommend using carbon emission baselines and load curves as a starting point to plan a list of projects, giving priority to the construction of physical platforms such as direct connection to green power and energy storage; at the same time, it is also necessary to build a carbon data platform to make carbon data measurable, reportable, and verifiable, thus forming tradable carbon assets and traceable green power supply. Thus, we will create a park that effectively reduces carbon export costs for enterprises.
Financial side: Moving from individual products to comprehensive services, turning the park into a green finance scene. Zero-carbon park investment has the risk-return characteristics of large capital expenditure, long payback period, and relatively stable cash flow, and is a natural fit for sustainable financial instruments. We encourage financial institutions to use zero-carbon parks as an important driving direction for green finance and carry out green finance innovation. Using Jiangsu's “Zero Carbon Park Loan” as a reference, the park's green electricity consumption ratio, carbon emission intensity, and carbon emission reduction can be included in credit approval and risk pricing, and the extension of the credit base from individual projects to carbon accounts of parks and enterprises can be promoted. At the same time, we are more actively promoting the application of financial products such as REITs in the zero-carbon park sector.
Policy side: Improve the incentive mechanism to make carbon reduction accountable, monetizable, and sustainable. The policy has completed the “three steps”: initially, the foundation was consolidated with green industrial parks and recycling transformation; in the medium term, unified standards and inspection mechanisms were established with Document No. 910; at this stage, the first batch of lists is used to promote the transformation of the system into a project. Looking ahead, we expect the policy to continue to strengthen in three directions: one is to improve the price and revenue mechanism, speed up the clarification of direct green electricity prices and transmission and distribution prices, improve the energy storage capacity compensation and revenue mechanism, so that the most definitive green power and energy storage investments can obtain sustainable returns; the second is to strengthen the institutional interface of environmental rights, promote mutual recognition and exchange between green certificates, carbon markets and carbon footprint accounting, avoid double calculation, and speed up mutual recognition of carbon accounting standards and international certifications in the park to help export enterprises cope with green trade rules such as CBAM; the third is to expand carbon capital channels to help export enterprises cope with green trade rules such as CBAM; Emission Reduction Support Tools and Fiscal Interest Rate Coverage Meanwhile, encourage special bonds, policy finance, and government funds to sink park projects in the form of capital, and use a normalized mechanism to promote the selection of subsequent batches of zero-carbon parks to stabilize market expectations.
Taken together, the zero-carbon park implements the dual-carbon target as a physical project that can be calculated, can be inspected, and has cash flow. Under the resonance of policy, parks, and sustainable finance, zero-carbon parks are expected to reshape a new infrastructure track for the green industrial development paradigm during the “15th Five-Year Plan” period.