
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Getlink (ENXTPA:GET) Reports Stronger September Traffic, Is The Premium Already Priced In?
Getlink (ENXTPA:GET) is back in focus after fresh traffic figures. LeShuttle Freight carried 102,014 trucks in September, while passenger shuttles transported 197,717 vehicles, both higher than a year earlier.
The fresh traffic update lands alongside a solid run in the shares, with Getlink trading at €18.74 after a 1-day share price return of 1.30% and a year-to-date share price return of 17.79% that points to building momentum. Over a longer window, the 1-year total shareholder return of 28.04% and 5-year total shareholder return of 59.95% indicate that investors have already been rewarded as perceptions of the business have shifted.
Scan how Getlink compares with other transport and infrastructure stocks showing strong momentum and solid fundamentals using the list of solid balance sheet and fundamentals (206 results) in the same place.
After a strong run in Getlink shares and a price still below consensus targets, the debate tightens. Is that market discount a margin of safety, or a warning that caution on this stock is justified?
Price-to-Earnings of 31.3x: Is it justified?
Valuation has moved quickly for Getlink, with the shares at €18.74 implying a P/E of 31.3x that puts a clear premium on current earnings compared with peers.
The P/E ratio compares what investors are paying for each euro of profit. For an infrastructure operator like Getlink, this highlights how much the market is prepared to pay for relatively steady cash generation rather than rapid expansion.
That premium is steep. The stock trades on 31.3x earnings while the wider European infrastructure group sits at 17.3x, and the peer average is 9.5x. Against an estimated fair P/E of 13.9x, the current valuation looks stretched, which signals that expectations embedded in the price are far richer than the level our fair ratio suggests the market could move toward.
Explore the SWS fair ratio for Getlink.
Result: Price-to-Earnings of 31.3x (OVERVALUED)
Still, Getlink’s premium P/E leaves little room for earnings disappointment, and any setback in cross-Channel demand or ElecLink performance could quickly cool enthusiasm.
Find out about the key risks to this Getlink narrative.
Another View on Getlink’s Value
The high P/E suggests investors already pay a steep price for Getlink. A different lens, the SWS DCF model, points the other way and indicates the shares trade above an estimated future cash flow value of €12.69. If earnings slow, does this richer price still feel comfortable?
Look into how the SWS DCF model arrives at its fair value.
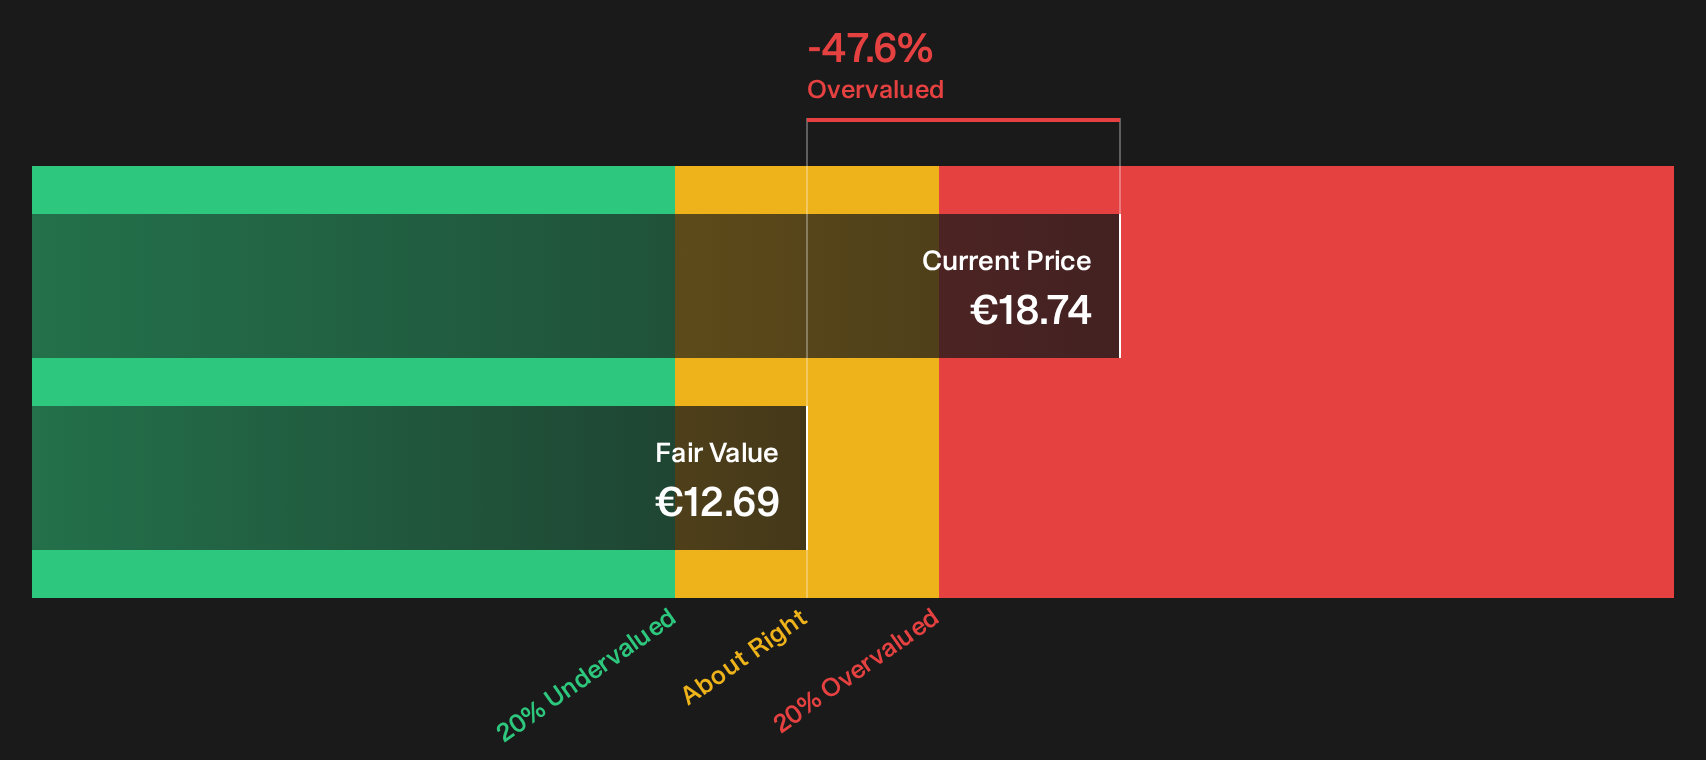
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Getlink for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Big swings in valuation and mixed signals on Getlink’s prospects will always split opinion, so move fast and stress test the numbers yourself against your own risk tolerance. To see how the potential upsides stack up against the potential pitfalls in one place, take a look at the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Getlink?
If Getlink has sharpened your appetite for opportunities, do not stop here. The next move often comes from comparing different types of strengths side by side.
- Target long term resilience by scanning companies with robust finances and conservative leverage using the 225 resilient stocks with low risk scores.
- Hunt for quality at a discount by reviewing companies that pair solid fundamentals with appealing pricing through the 179 high quality undervalued stocks.
- Focus on income potential by checking which companies offer higher yields with staying power via the 225 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com