
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Azenta (AZTA) Stock Still Looks Undervalued Following A 64% Five Year Fall
Azenta shares have climbed in the short term, yet longer term investors have seen deep value wiped away, which raises a simple question for today: Is the current US$36.00 price supported by what the company is generating in sales?
- Over 5 years the stock has fallen 64.4%, which puts the focus squarely on whether the underlying revenue base still matches the market’s latest pricing.
- The recent resignation of long serving President and CEO John P. Marotta and related legal investigations may reshape expectations for how efficiently Azenta can turn its life sciences offerings into future sales.
- Your read on Azenta is one view; the desks covering it have another. See what analysts think Azenta's shares could be worth.
The issue now is whether Azenta's recent share price level is justified by its sales when set against a Fair Ratio benchmark.
To see this same sales versus price question applied across a broader set of companies, compare Azenta with the 27 high quality undervalued stocks.
Is Azenta Still Cheap on Sales?
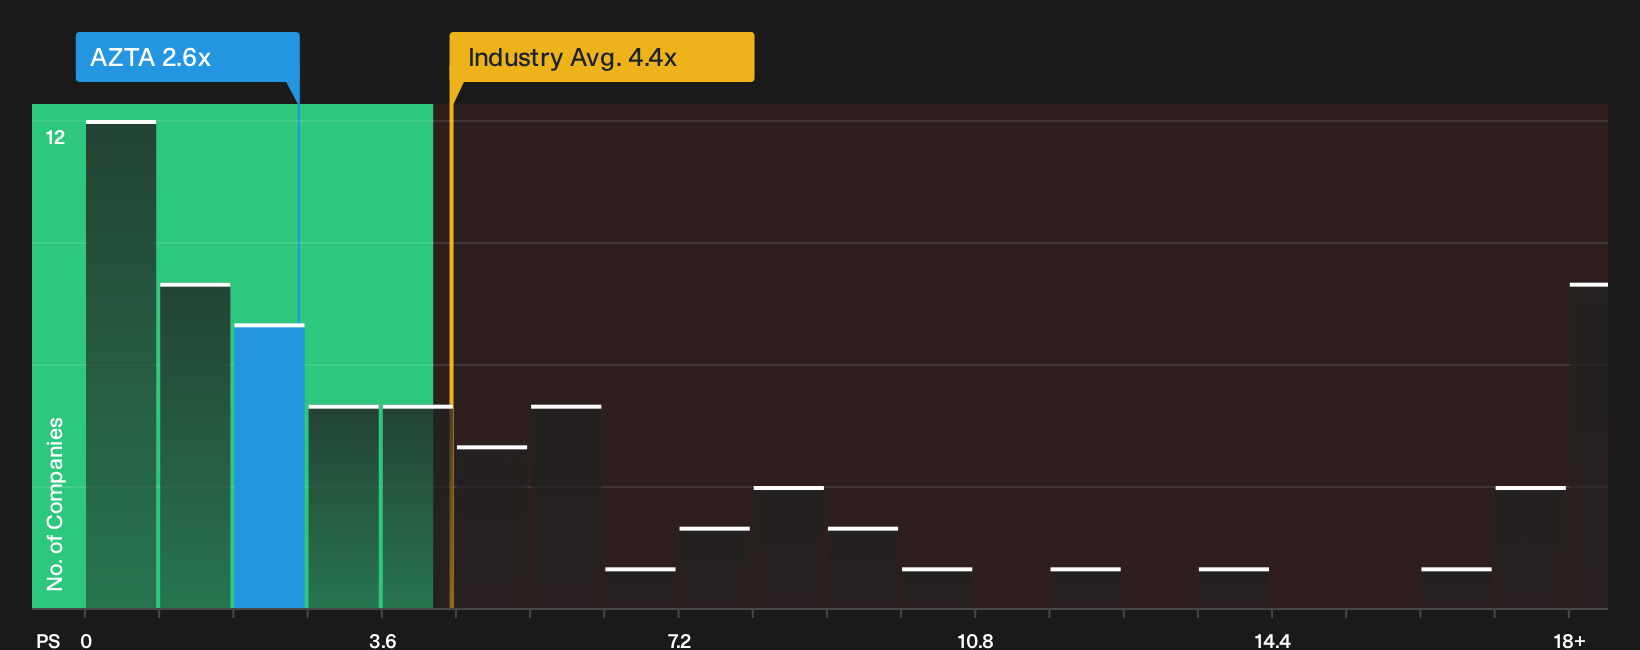
P/S is a useful lens for Azenta because the focus is on how much investors pay for each dollar of sales in a business where earnings can swing around investment cycles and legal costs. On this measure, the stock trades on a P/S ratio of 2.6x, compared with a Life Sciences industry average of 4.4x and a broader peer group closer to 11.9x.
The Fair Ratio model, which adjusts for Azenta's margins, market position, size and risk profile, points to a higher P/S than where the stock currently trades, so the shares screen as undervalued on this framework. Because the August 2026 CEO resignation and ongoing legal investigations have pulled attention to governance and execution risk, the gap to that Fair Ratio suggests the market is applying a substantial precautionary discount to the revenue base rather than paying up for potential. Explore the numbers behind Azenta's P/S valuation.
The Azenta Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Azenta pick up where the P/S puzzle leaves off and explain which potential paths for Azenta's growth, profitability and earnings would need to occur for the stock to be worth meaningfully more or less than its current market price.
Where a single valuation ratio or model outputs one number, these narratives unpack the future it relies on so you can track how real world developments either support or challenge that picture over time, all in one place on Simply Wall St's Community page.
Community views on Azenta split between investors who see more upside and others who think the stock already prices in much of the story.
Bull case: 14% undervalued
"Decentralized operating companies with clear accountability, a rebooted North America commercial team and growing sales capacity in Europe, Asia and China create a broader commercial reach..."
Discover why this Narrative puts Azenta at 14% undervalued.
Bear case: roughly fairly valued
"Persistent customer budget constraints and internal realignments in the pharma and biotech sectors are causing delays in orders for Azenta's higher-margin capital equipment and core product lines..."
Explore why this Narrative puts Azenta at roughly fairly valued.
Before you move on from Azenta's valuation, one more piece matters
Price tags on shares only tell part of the story, because the people setting priorities, allocating capital and rewarding themselves inside Azenta can tilt outcomes in ways this piece has not explored yet. See who runs Azenta and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com