
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Slow Revenue Growth Change CDW Stock's Narrative
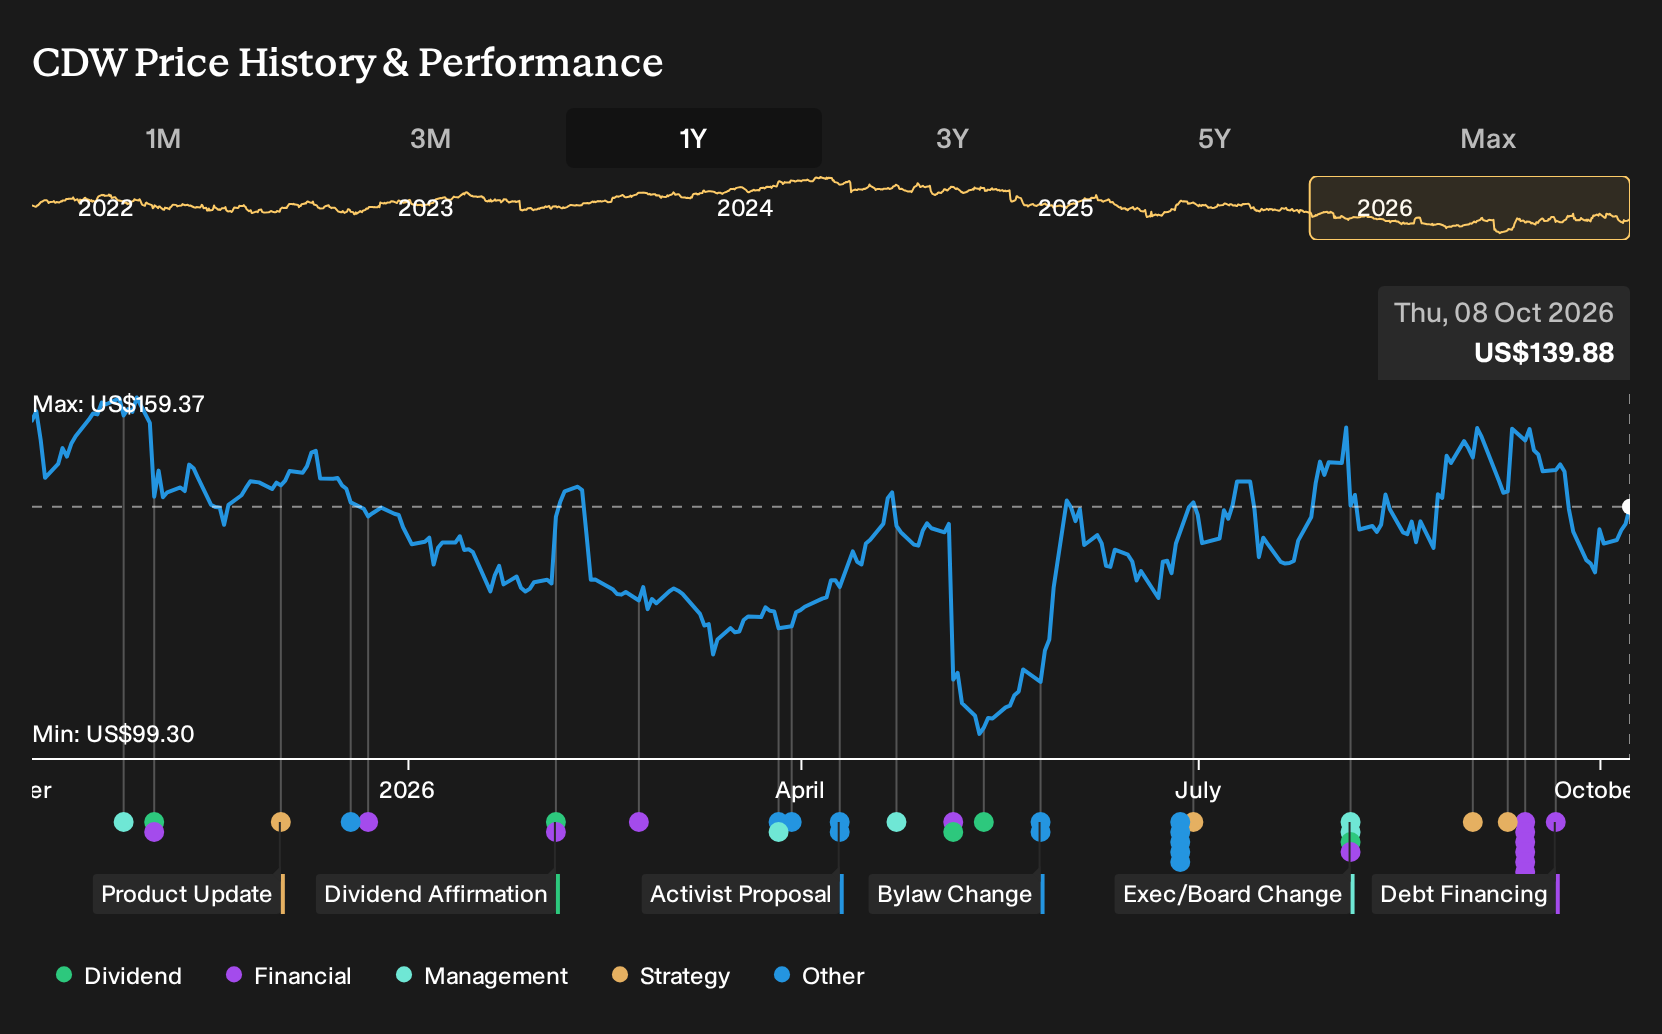
- CDW has come under pressure as investors reassess its fundamentals, with long term revenue growth of 3.6% a year over the past five years and analyst forecasts pointing to only 3.7% revenue growth over the next 12 months.
- The key concern is that this slow top line trajectory, combined with analyst views that business quality is below sector standards, could leave CDW more exposed to demand headwinds than peers that are growing faster.
- We will now explore how CDW's modest projected revenue growth shapes its investment narrative and what that could mean for investors.
CDW Investment Narrative Recap
To own CDW, you need to be comfortable with a slower top line and a story that leans on execution rather than rapid expansion. The thesis rests on demand for AI, cloud, security and hybrid IT projects turning into steady hardware, software and services activity. The recent focus on modest 3.7% revenue growth does not change that core idea, but it does underline that patience is required.
The near term swing factor is whether CDW can shift mix back toward higher margin services while keeping infrastructure deals flowing. The biggest risk sits in margins and cash conversion. Gross margin is guided modestly below 2025, services grew only 1% in Q2 2026, and working capital tied up in inventory has already pulled free cash flow conversion down.
With no fresh announcements disclosed since the Q2 2026 update, that quarter still frames the most relevant context for this slower growth debate. Management reported strong demand for servers, storage, networking, security, software and cloud, which helps explain why hardware heavy projects are driving more of CDW’s activity. Those orders support scale, but they also lean toward lower margin mix.
For you as a shareholder, the operational question is whether that Q2 pattern evolves toward higher value recurring services as AI and cloud projects move from build to deployment. The Lovelytics acquisition, which brought more than 600 data and AI specialists, is already aimed at that services shift. Execution on this pivot, plus delivery from the Geared for Growth efficiency program, will likely matter more than near term revenue optics.
CDW's current analyst story points to US$26.5b in revenue and US$1.4b in earnings by 2029, based on a projected 4.0% yearly revenue growth rate and an uplift in profit margins from 4.6% to 5.3%. That earnings path implies an increase of about US$0.3b from the US$1.1b reported today.
Uncover how CDW's fair value indicates a 13% potential upside to its current price that could narrow quickly if sentiment improves.
Exploring Other Perspectives
For a very different angle on CDW, the most optimistic analysts focus on the services pivot as a potential upside swing factor. They were modeling about US$27.9b of revenue and US$1.4b of earnings by 2029, with a higher 18.0x P/E. Those projections were set before this news, so you should expect opinions to shift and explore both narratives yourself.
Explore 4 other CDW fair value estimates, including one that suggests as much as 56% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CDW research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CDW. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CDW's overall financial health at a glance.
Looking For More Investment Ideas Beyond CDW?
If CDW helps sharpen your view on IT services and infrastructure, it can also be a useful reference point as you scan for other opportunities with different growth, quality or balance sheet profiles using the Simply Wall St Screener.
- If you want companies that combine quality with what may be more modest pricing, start with a focused set of 27 high quality undervalued stocks that could fit a value driven watchlist.
- For investors who put resilience first, consider a group of 31 resilient stocks with low risk scores that score well on stability and business risk factors.
- To hunt for less crowded opportunities, use a curated pool of 20 high quality undiscovered gems that pair solid fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com