
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Alphamin Resources (TSXV:AFM) Could Be 85% Undervalued Following Dividend And Tin Update
Alphamin Resources (TSXV:AFM) grabbed investor attention after the board declared an interim 2026 cash dividend of CA$0.13 per share, alongside fresh quarterly tin production figures and detailed exploration updates.
Those updates landed after a stretch where Alphamin Resources has shown firm momentum, with a year to date share price return of 23.28% and a 1 year total shareholder return of 42.10%, even though the 30 day share price return declined 4.67%.
Compare Alphamin Resources with other tin producers and materials stocks by scanning the hand picked 16 top copper producer stocks that could benefit from similar cash generation and resource driven catalysts.
Bulls point to Alphamin Resources’ hefty interim dividend and ongoing drilling success, while bears focus on declining annual revenue and earnings. Which side does the current valuation actually support, given this mix of cash returns and operational risk?
Preferred P/E of 5.9x for Alphamin Resources: Is it justified?
Valuation for Alphamin Resources currently leans on a low P/E of 5.9x, which sits against a CA$1.43 share price and a market narrative that still treats this as a high cash generator facing declining forecast earnings.
The P/E multiple compares what investors pay today for each dollar of earnings. For a tin producer like Alphamin Resources, that lens matters because earnings are closely tied to commodity prices, mine performance, and capital spending choices, all of which feed directly into reported profit.
A P/E of 5.9x is far below the Canadian Metals and Mining industry average of 15.2x and also sits under the estimated fair P/E of 7.1x that our fair ratio work suggests the stock could move toward if conditions align. That gap indicates the market is pricing in meaningful risk around forecast revenue and earnings declines, insider selling, and an unstable dividend record, even though return on equity is described as outstanding at 58.3% and net margins have widened compared to last year.
AFM is also described as trading at good value compared to peers with a 27.6x average P/E, which is a very large premium to Alphamin Resources, and at good value on a broader peer and sector check. That combination of strong historical profit growth at 27% per year over five years, high quality earnings, and a low earnings multiple suggests the current ratio reflects investor caution rather than a shortage of recent profitability.
Explore the SWS fair ratio for Alphamin Resources.
Result: Price-to-Earnings of 5.9x (UNDERVALUED)
Still, declining annual revenue and net income, along with full reliance on a single Bisie tin asset in the DRC, could quickly challenge the Alphamin Resources thesis.
Find out about the key risks to this Alphamin Resources narrative.
Another view on Alphamin Resources using cash flows
Valuing Alphamin Resources purely on its 5.9x P/E tells only part of the story. Our DCF model points to a future cash flow value of CA$9.58 per share against a CA$1.43 price, which signals a very wide gap. Is that a genuine opportunity or just reflecting the forecast earnings and revenue declines?
Look into how the SWS DCF model arrives at its fair value.
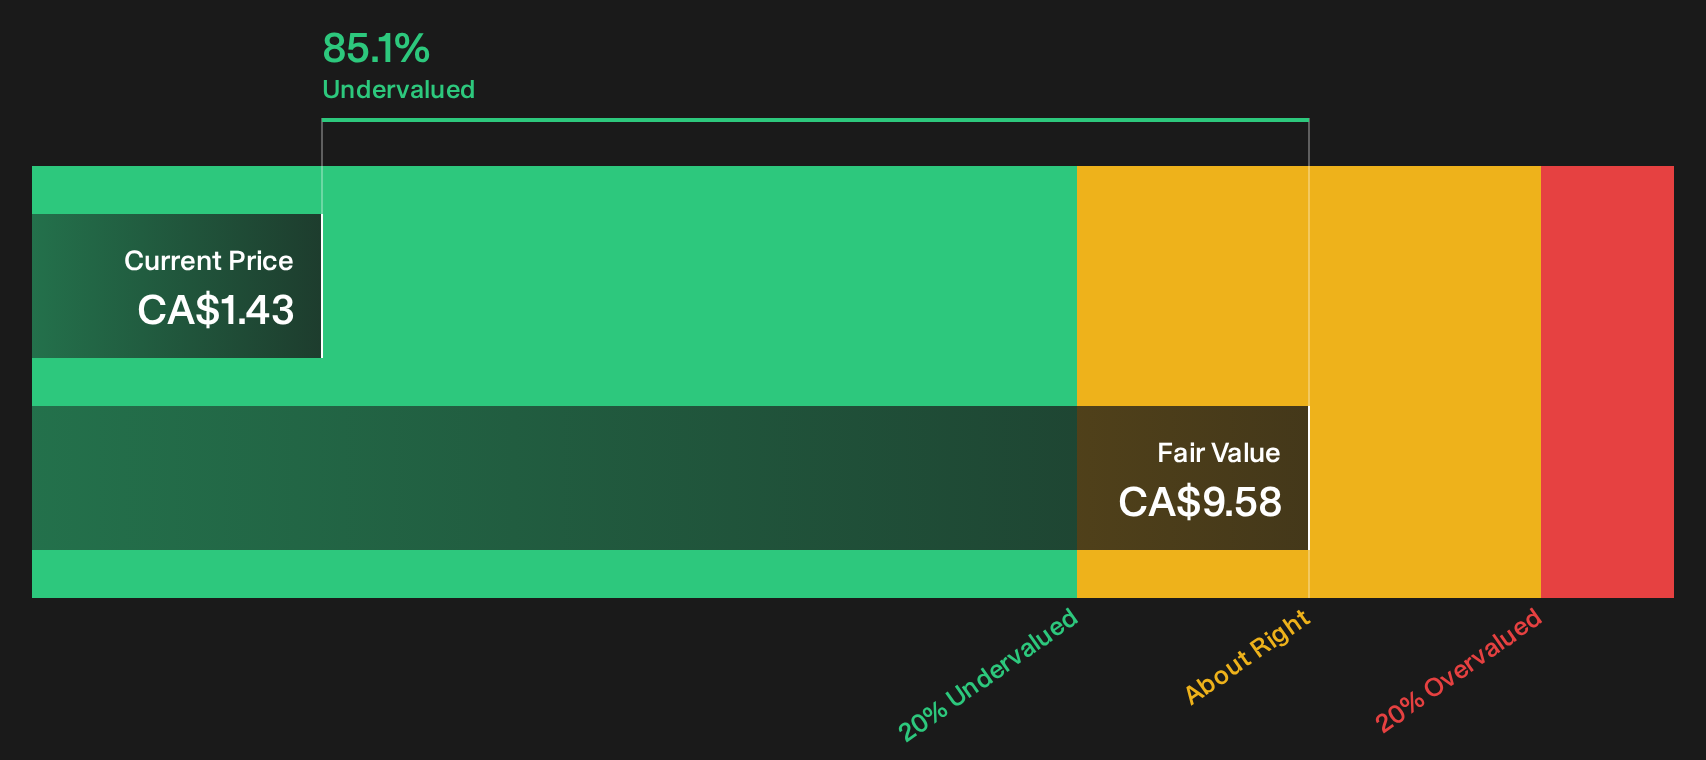
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Alphamin Resources for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Alphamin Resources can pull sentiment in both directions, so consider acting while the data is fresh and weigh the 3 key rewards and 3 important warning signs carefully.
Looking for more investment ideas beyond Alphamin Resources?
You have a clear picture of Alphamin Resources now. Before moving on, it may help to line up a few fresh candidates that fit your style.
- Target potential mispricings by scanning companies that screen as attractively valued through the 7 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses that pass the high yield quality checks in the 3 dividend fortresses.
- Prioritise resilience by filtering for companies with robust finances using the list of solid balance sheet and fundamentals (7 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com