
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Chewy (CHWY) Stock Looks Fully Priced On Its 70% Five Year Slump
Chewy has had a rough ride over the past few years, and with the stock closing at US$18.91 most recently, the key question is whether that price is properly supported by the earnings the business is generating today.
- Over the past 5 years the share price has fallen 69.8%, which puts the spotlight squarely on whether current earnings can justify even this lower level.
- The business model leans heavily on repeat pet supply orders and subscription style revenue. This can matter a lot for how reliably earnings convert into cash over time.
- The analysts covering Chewy have run their own numbers. See what analysts think Chewy's shares could be worth.
The issue now is whether Chewy's current share price fairly reflects what its recent earnings say about the underlying business.
If Chewy's earnings driven story has you reassessing risk and reward, it can help to compare it with other businesses screened for 31 resilient stocks with low risk scores.
Does Chewy Look Pricey on Earnings?
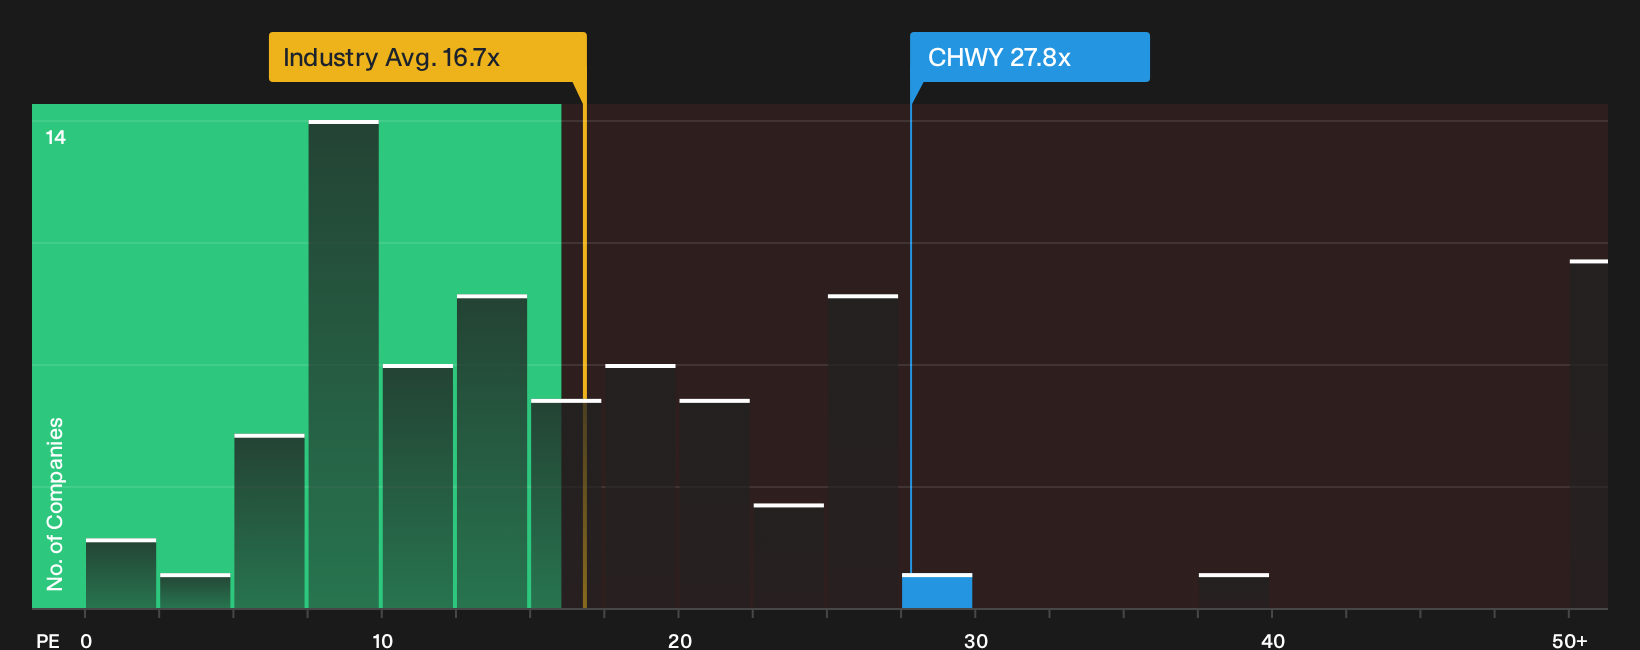
The P/E ratio suits Chewy because investors often focus on how consistently subscription driven orders can turn into earnings. At a P/E of 27.8x, Chewy trades well above the Specialty Retail industry average of 16.7x and the peer average of 15.4x. This means each dollar of its current earnings is priced more richly than many comparable retailers.
The tailored fair multiple that blends Chewy's margins, size, sector and risk profile points to a lower figure than today, so the stock screens as overvalued on this specific earnings lens. For you as a shareholder or potential buyer, the key question is whether Chewy's recurring pet supply model and cash generation justify paying this higher earnings tag, or whether the valuation leaves less room for disappointment. Explore the numbers behind Chewy's P/E valuation.
The Chewy Narrative: What Would Justify Today's Price?
Chewy's valuation puzzle raises a simple question. What kind of future would have to play out for this price to look cheap or expensive when viewed through earnings, margins and growth? Narratives on Simply Wall St’s Community page turn that question into specific stories about Chewy's potential catalysts and risks, with each one tying a fair value estimate to a different scenario so you can track over time which version seems to be unfolding.
One of the top community narratives on Chewy: 47% undervalued
"Chewy Vet Care and the acquired Modern Animal clinics are now described as outperforming the initial economic case, with roughly 60 clinics expected..."
Discover why this Narrative puts Chewy at 47% undervalued.
Before acting on Chewy's valuation, there is one more angle to check
Price tags and recent earnings only tell part of Chewy's story, since professional models already sketch where revenue, profits and cash flows could land a few years from now. Explore where analysts expect Chewy to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com