
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Japanese Undervalued Stocks Trading Up To 48% Below Fair Value
AI related goods are now a powerful driver of global trade, with East Asia leading the charge according to recent forecasts through 2029. That backdrop shines a brighter light on Japanese companies that quietly produce strong cash flows and keep their balance sheets in good shape. For investors who hate overpaying, this is where mispricing can matter. This article highlights three high quality Japanese stocks that currently appear to be overlooked.
The three Japanese stocks below are just a sample of what screens well on cash generation, balance sheet quality and value scores. The full filter surfaced 11 more businesses with equally compelling narratives that are not covered here. If you want to move straight from ideas to a working watchlist, head into the High Quality Undervalued Stocks screener to identify, analyze and focus on the highest conviction setups.
Rakus (TSE:3923)
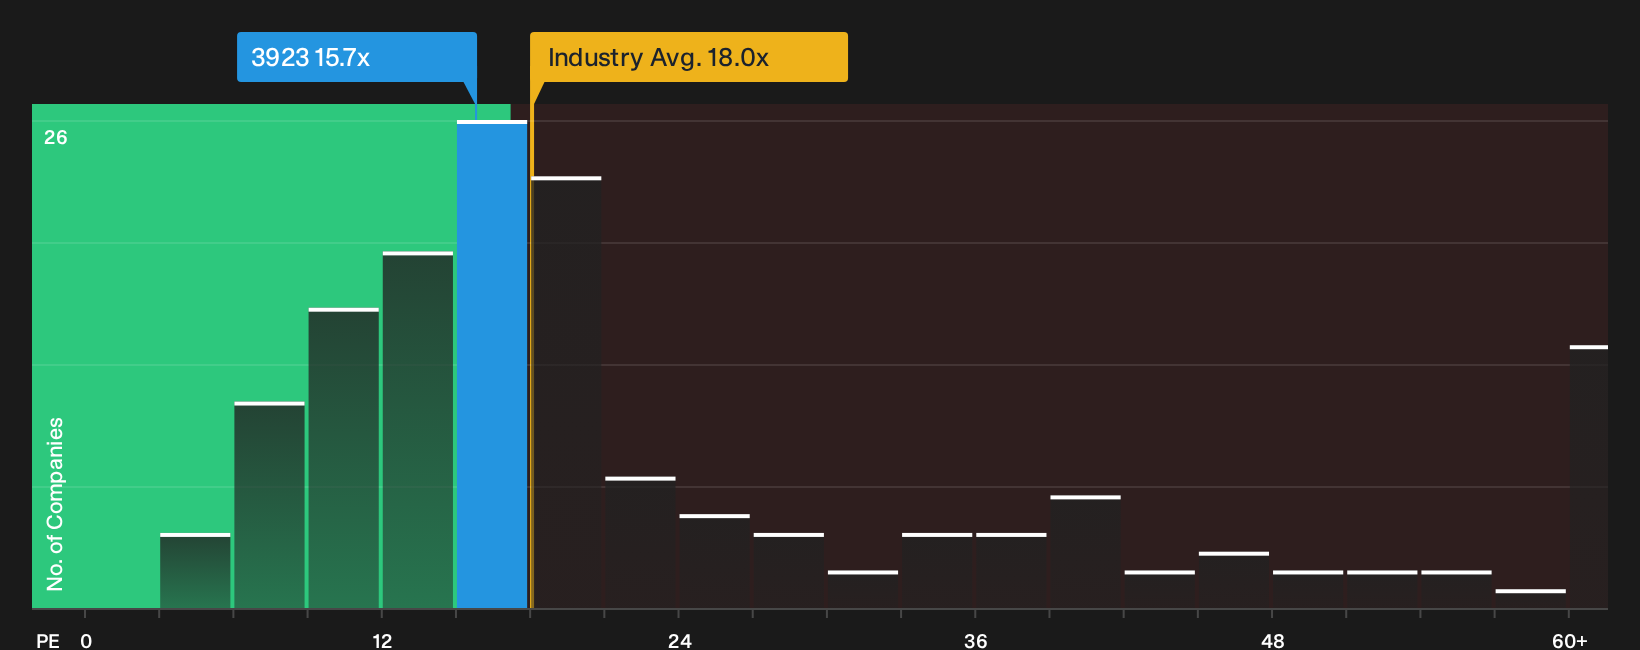
Rakus is a Japan based software business that delivers cloud services like RakuRaku Settlement and RakuRaku Statement, alongside an IT staffing arm that provides engineers and infrastructure support. It generates ¥60.4 billion of revenue in Japan and carries a market value of about ¥383.7 billion.
Rakus lines up cleanly with the High Quality Undervalued Stocks theme. The cloud SaaS suite contributes recurring cash flow, the P/E of 15.7x sits far below a peer average of 83.5x, and current net profit margins of 40.4% indicate strong economics that could look very different if one unseen pressure on those returns shifts.
If that hidden pressure point matters to you, go straight to the 4 key rewards and 2 important warning signs to see what might be masking or exaggerating those rich margins.
Dexerials (TSE:4980)
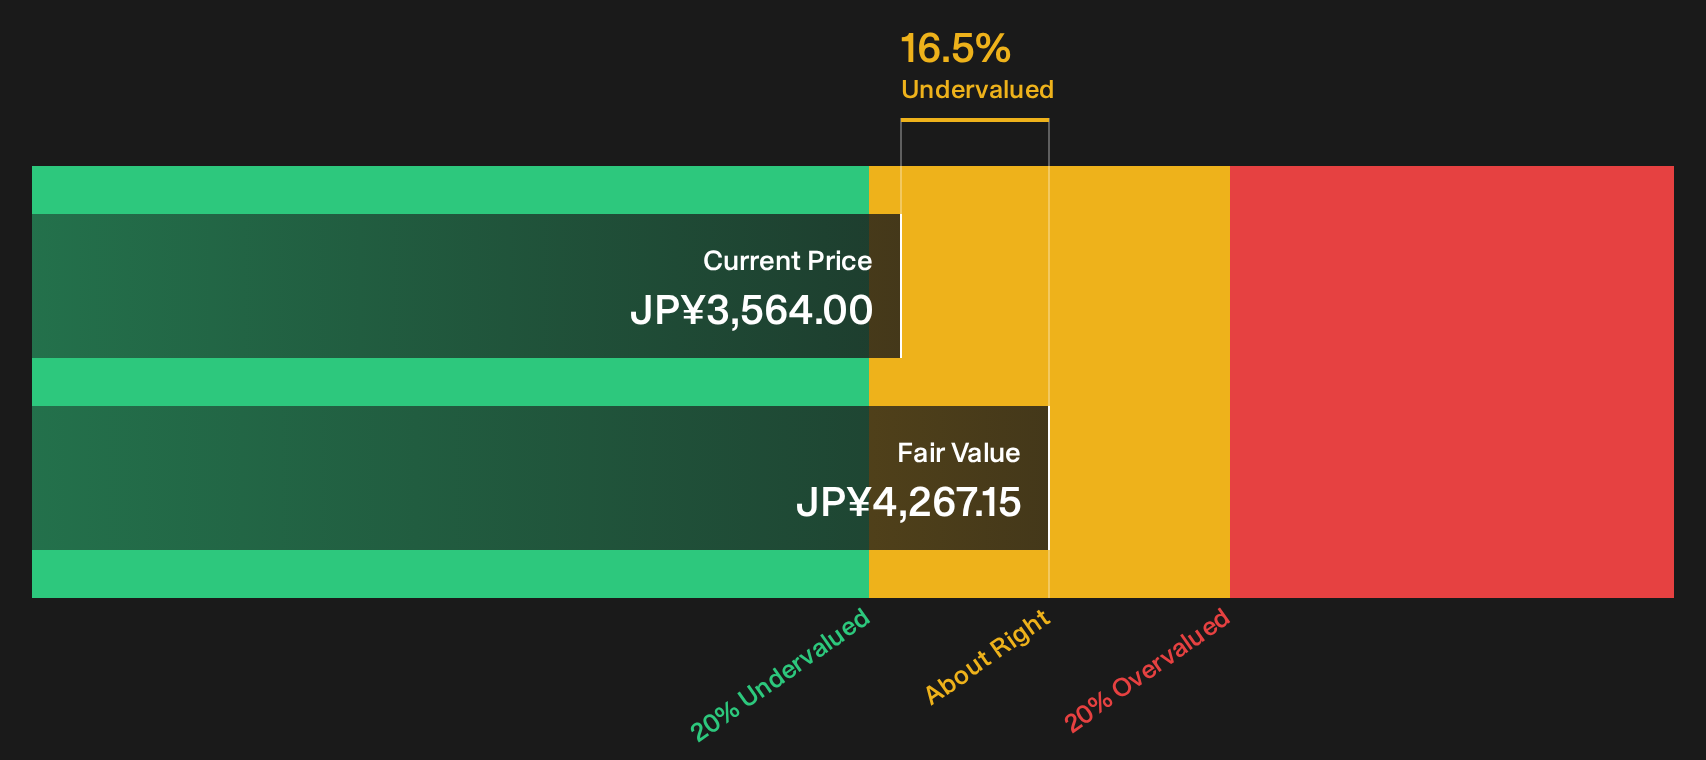
Dexerials is a Tochigi based electronics manufacturer whose Optical Materials and Components segment, supplying items like conductive films and anti reflection films into devices, anchors its fit with the High Quality Undervalued Stocks theme. That division generates about ¥46.4 billion of revenue alongside ¥69.4 billion from Electronic Materials and Components, with the group valued at roughly ¥597.1 billion.
Dexerials ties cleanly into this screen because its optical materials segment converts smartphone, TV, automotive and communications demand into cash flow, supported by around 25% net profit margins and a value score that highlights its current valuation if a single assumption about future device demand proves too conservative.
If that device demand assumption looks too cautious, review the DCF valuation analysis for Dexerials to see where Dexerials might be mispriced before expectations catch up.
GMO Payment Gateway (TSE:3769)
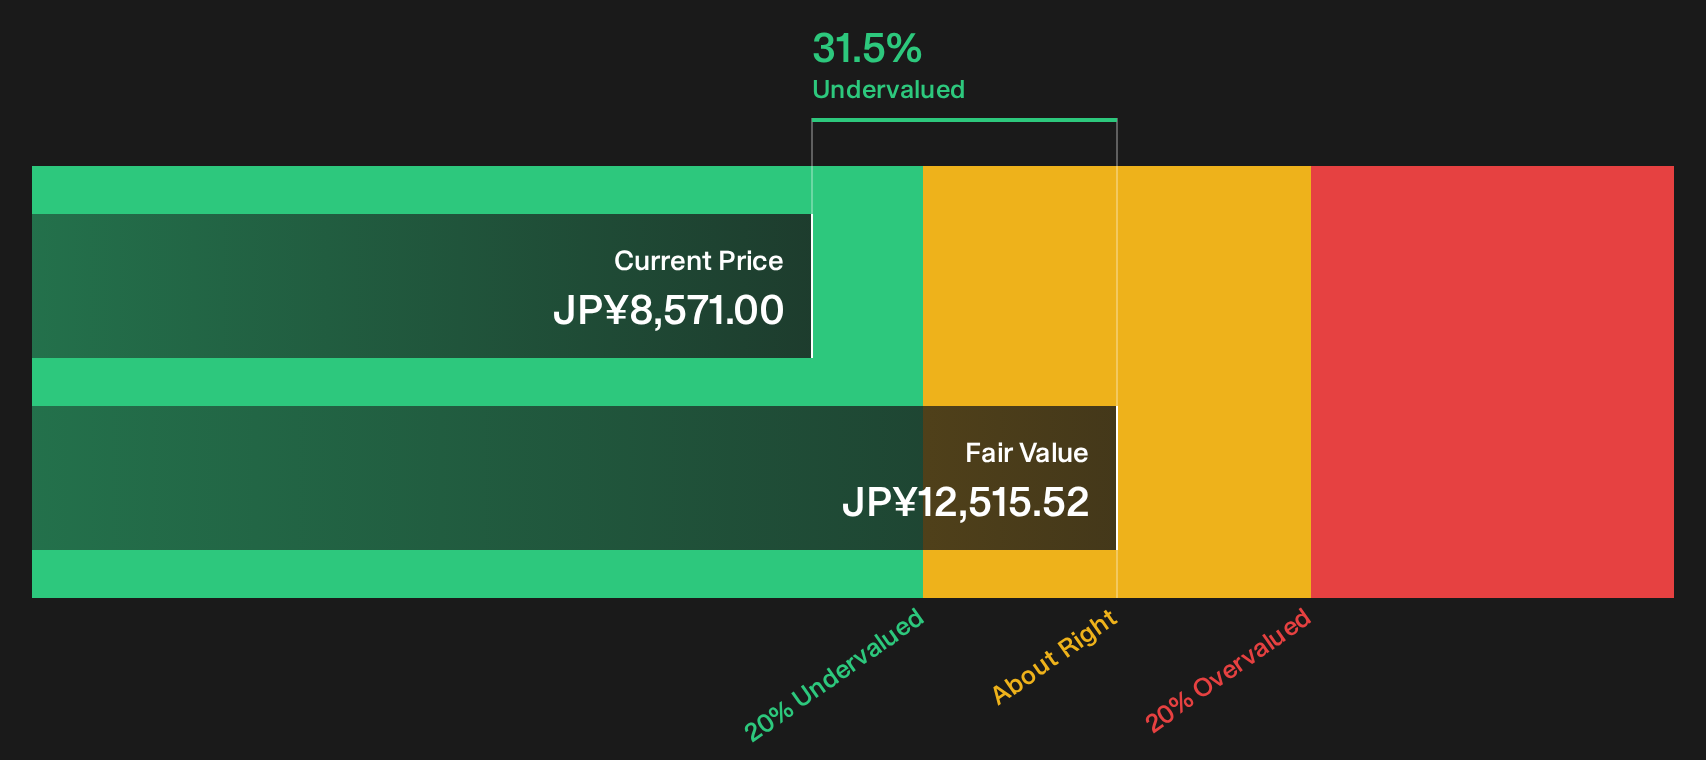
GMO Payment Gateway runs payment processing platforms that handle online and in person transactions, which ties into the High Quality Undervalued Stocks theme through recurring, cash-generating services such as PG multi-payment and GMO-PG processing. The business earns about ¥67.9 billion from payment processing and ¥21.7 billion from money services, and has a roughly ¥651.0 billion market value.
GMO Payment Gateway turns recurring payment flows into cash, with the payment processing unit generating about ¥67.9 billion in revenue and the money services arm adding roughly ¥21.7 billion. The stock is presented as undervalued in this screen, so a key consideration is how the market evaluates the company’s recurring transaction engine over time.
To see how the market is really pricing that recurring engine, review the DCF valuation analysis for GMO Payment Gateway and judge whether GMO Payment Gateway’s cash flows are being underestimated.
Seeking Fresh Alternatives Before They Fly
Fresh ideas often move first. Breakout momentum can develop quickly once the crowd notices. Scan under the radar for now, while it matters, and act early.
- Track income that keeps coming in by reviewing a curated mix of higher yielding opportunities through the 32 dividend fortresses before payouts and prices move away from you.
- Explore demand for tomorrow’s infrastructure by assessing the curated 91 AI infrastructure stocks that may be building momentum while much of the focus remains on headline tech giants.
- Consider real assets that can respond when money chases scarcity by scanning the focused 35 elite gold producer stocks before renewed interest potentially tightens the entry window.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com