
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Qualcomm (QCOM) Sues Over A Royalty Dispute With Multibillion Dollar Stakes
- Qualcomm (NasdaqGS: QCOM) has filed a lawsuit against Arm Holdings over an alleged breach of contract tied to chip royalty terms.
- The case centers on essential chip testing tools and licensing rights that underpin multi billion dollar royalty streams between the companies.
- Qualcomm argues the disputed royalties relate to future payments on Arm based designs used across a wide range of connected devices.
- The Qualcomm lawsuit over Arm royalties adds a fresh layer to the licensing picture that recent agreements with Apple and Huawei helped clarify. Check out 1 major warning sign that QUALCOMM investors should know about.
This royalty fight highlights how Qualcomm is not alone in facing legal and commercial pressure around chip design and AI infrastructure exposure, so it is worth comparing it with peers through 92 AI infrastructure stocks.
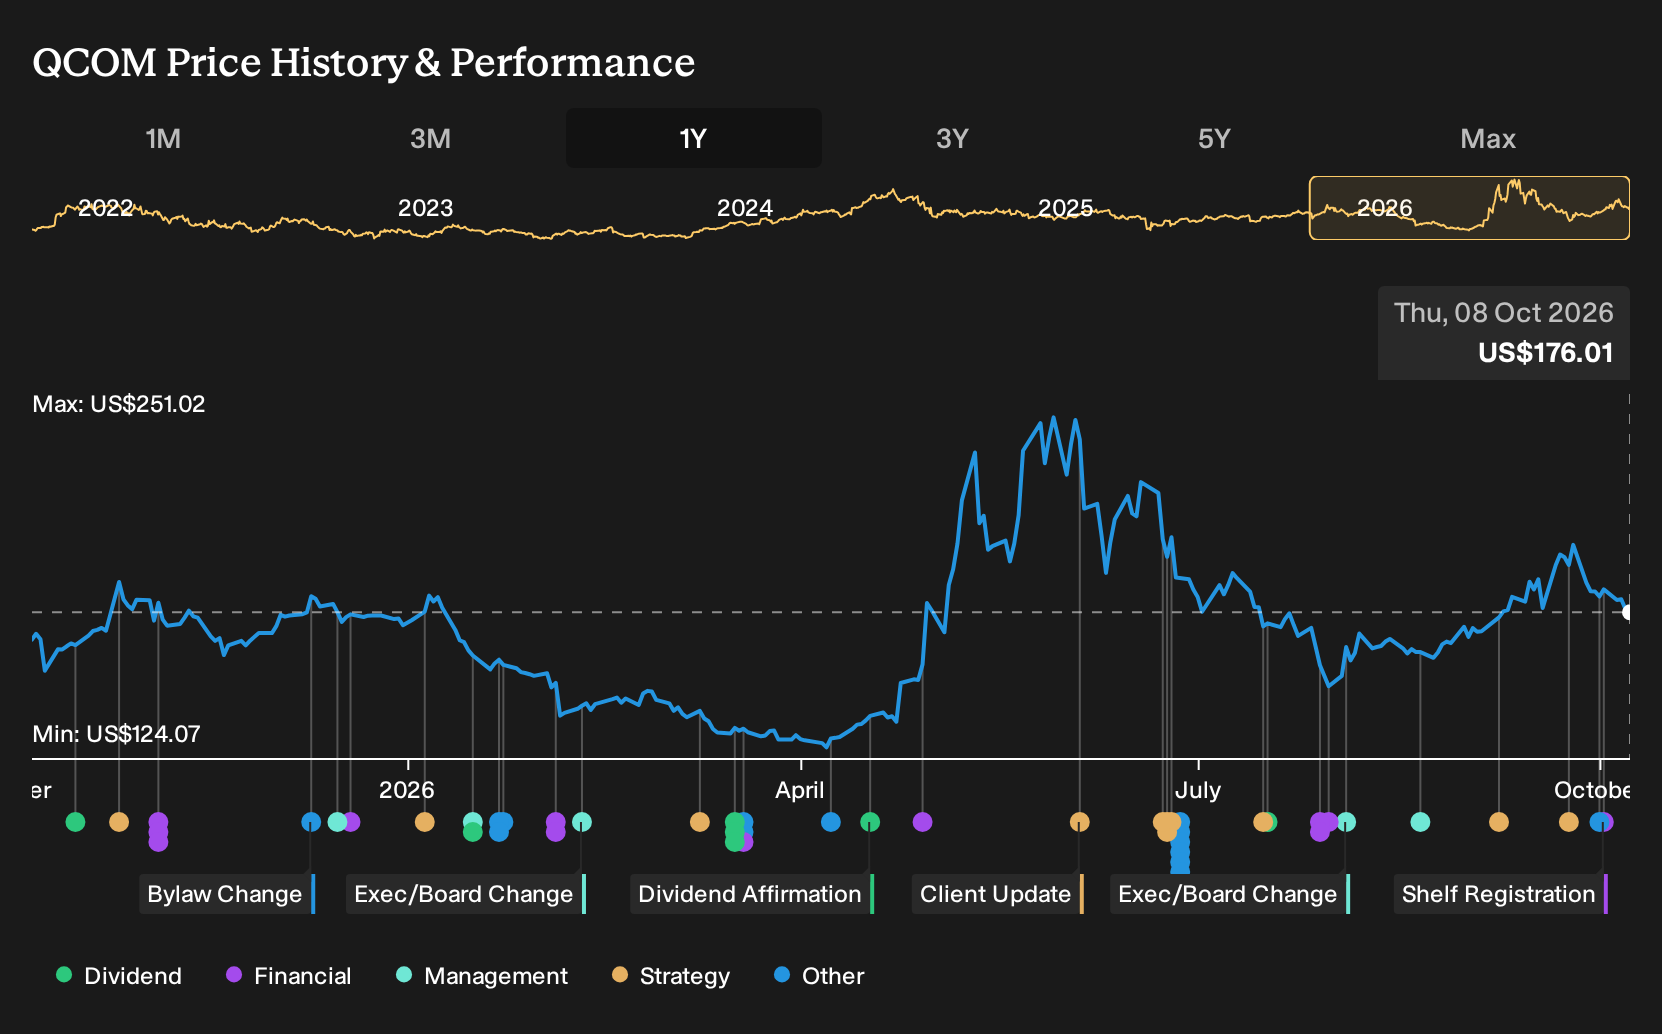
Qualcomm develops and licenses core wireless technologies that other chipmakers and device manufacturers depend on, so any dispute over royalty terms touches a critical revenue engine for a US$189.1b semiconductor heavyweight and its partners across the broader wireless ecosystem.
See how QUALCOMM's balance sheet measures up.
How the Arm lawsuit stresses Qualcomm’s royalty engine, not just its AI story
The Qualcomm Narrative assumes a resilient licensing machine quietly funding a big shift toward AI devices, automotive, IoT and data center, so a multi billion dollar royalty fight with Arm lands right on that premise.
"Execution against Qualcomm’s fiscal 2029 target of US$40b in non handset QCT revenue, including more than US$14b from IoT and US$10b from automotive, together with long term operating margin goals of about 30% for QCT and 70% for QTL, would support a shift in the company’s earnings profile away from handset cyclicality and toward a broader AI and compute revenue base..."
See how the full story points towards a $194 fair value for QUALCOMM.
The lawsuit cuts across the idea that Qualcomm can rely on stable royalty flows while it pushes into data center AI and automotive. Any court imposed change to what gets tested, licensed or paid for could complicate the path to those long term 70% QTL margin ambitions that underpin the handset to non handset transition.
At the same time, this dispute sits alongside renewed Apple and Huawei patent deals that support the view of Qualcomm as an IP heavyweight, not just another chip vendor like MediaTek or Nvidia. The market reaction may fixate on legal risk and overlook that licensing depth is also what gives the firm leverage when contracts or tools are challenged.
For an investor, linking headlines like this lawsuit back to a clear Qualcomm Narrative is what turns raw legal noise into a coherent decision on risk and reward.
One more thing Qualcomm investors should check before moving on
Short term headlines only tell you what just happened. The analyst models go somewhere very different with Qualcomm a few years out, and that path can reshape how you think about risk and payoff. See where analysts expect QUALCOMM to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com