
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Canadian National Railway (TSX:CNR) The Latest Update Raises A Bigger Question
Canadian National Railway (TSX:CNR) just set a quarterly record by moving 7.94 million metric tonnes of grain from Western Canada. This is a fresh data point that puts its dividend profile and recent share performance in sharper focus.
That grain record landed as Canadian National Railway’s share price climbed 20.65% year to date to CA$166.23, with a 27.05% total shareholder return over the past year, suggesting that investors are rewarding the combination of operational execution, a dividend growth story, and perceived resilience in its rail network.
Scan beyond Canadian National Railway’s record grain volumes and dividend story by sizing up hand picked transportation and infrastructure peers in our list of solid balance sheet and fundamentals (7 results).
Canadian National Railway now trades at CA$166.23, below an average analyst target of CA$189.32. One intrinsic value model, however, points to a roughly 10% premium. Which reference point appears closer to fair value?
Price-to-Earnings of 21x: Is it justified?
Canadian National Railway trades on a P/E of 21x, while our intrinsic value model flags the current CA$166.23 share price as roughly 10% above its CA$151.25 future cash flow estimate and below the average analyst target of CA$189.32.
The P/E multiple measures how much investors are paying today for each dollar of Canadian National Railway’s earnings. For a rail and intermodal operator with steady profit generation and a long operating history, earnings-based valuation is a common yardstick because cash flows are relatively established and profits are not purely speculative.
On that measure, the stock is described as “trading at good value compared to peers and industry” with its 21x P/E below both the Canadian and North American Transportation averages of 27.5x, and under a fair P/E estimate of 25.4x. These comparisons point to the market assigning a lower earnings multiple than both peer pricing and the fair ratio level the valuation could move toward if sentiment or expectations converge.
Explore the SWS fair ratio for Canadian National Railway.
Result: Price-to-Earnings of 21x (UNDERVALUED).
Still, Canadian National Railway’s story could be shaken if grain volumes soften or if higher costs pressure earnings, which could weigh on that 21x P/E multiple.
Find out about the key risks to this Canadian National Railway narrative.
Another View On Canadian National Railway’s Value
The P/E comparison presents Canadian National Railway as inexpensive relative to peers; however, the SWS DCF model suggests a different perspective. At CA$166.23, the stock price is roughly 10% above an estimated future cash flow value of CA$151.25. This frames the current level as overvalued from that valuation standpoint. Which signal is more important for your own analysis?
Look into how the SWS DCF model arrives at its fair value.
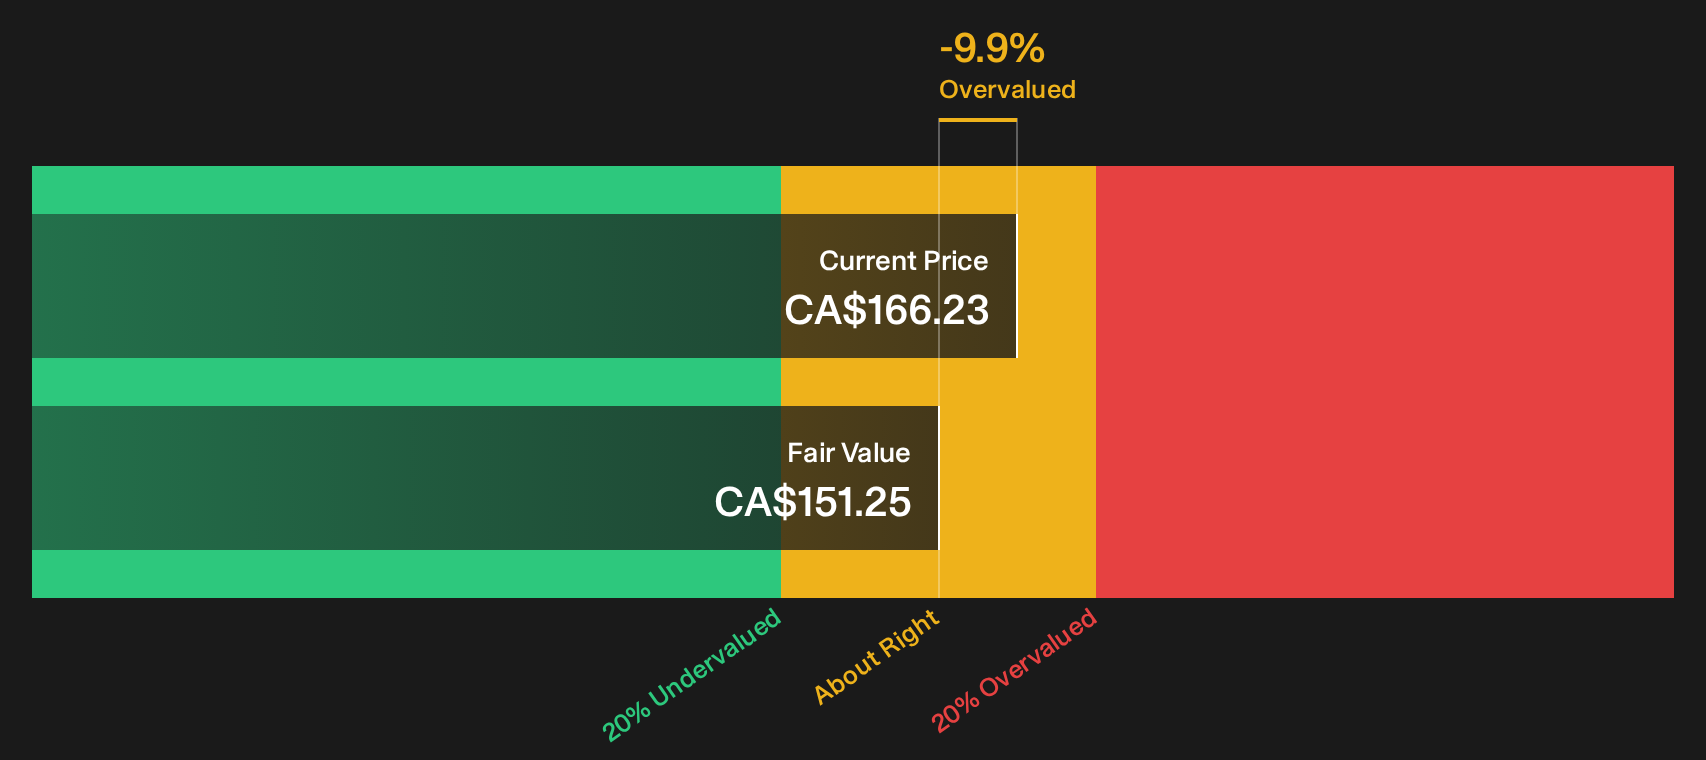
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Canadian National Railway for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Canadian National Railway’s valuation and fundamentals can feel like noise, so move quickly to check the underlying data, compare the positives and negatives, and weigh the 5 key rewards and 1 important warning sign
Looking for more Canadian National Railway investment ideas?
Do not stop your research with Canadian National Railway. Use the Simply Wall Street screener to pressure test your thinking, spot fresh angles, and avoid leaving potential opportunities on the table.
- Target resilient businesses with strong balance sheets and solid fundamentals by scanning the list of solid balance sheet and fundamentals (7 results).
- Hunt for quality companies that trade below their estimated worth by running the 7 high quality undervalued stocks.
- Prioritise stability and income by assessing companies that show up as 8 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com