
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Canadian Dividend Stocks With Yields Over 3%
Ray Dalio warns that rising bond yields are eroding the cushion for equities, which puts regular income front and centre for many Canadian investors. Reliable dividend payers offering more than a 3% yield can help soften the impact of higher borrowing costs. This article highlights three dividend-focused Canadian stocks from a high-yield, quality screen that aims to prioritise well covered, growing and stable payouts.
The three stocks below are just a sample from this idea. The full screen surfaced 21 more companies with equally compelling dividend stories that are not covered here.
If you want to identify, compare and analyse high-yield opportunities that fit your own risk profile, head straight to the Dividend Powerhouses (3%+ Yield) screener.
Canadian Tire Corporation (TSX:CTC.A)
Overview: Canadian Tire Corporation is a Canadian retailer with credit card and real estate arms, where CT REIT provides rental income that supports its dividend.
Operations: The group generates about CA$14.9b from Retail, CA$1.6b from Financial Services, and CA$618 million from CT REIT each year.
Market Cap: CA$10.0b
Canadian Tire Corporation brings together a large retail footprint, a financial arm, and a rent collecting property portfolio. This gives its dividend profile a very different flavour from many pure retailers and highlights a key consideration for income focused investors.
"Strong short-term sales have benefited from patriotic purchasing, favorable weather, and post-pandemic replacement cycles, transitory drivers that may not persist. At the same time, the longer-term shift towards e-commerce and digital-first shopping habits may reduce the relevance of brick-and-mortar traffic and constrain future revenue growth."
How well that less visible pressure on profitability gets managed will likely matter more for future dividend comfort than recent sales headlines.
That dividend comfort question is exactly what the full narrative for Canadian Tire Corporation digs into, spotlighting where Canadian Tire could still surprise if those pressures start to ease.

Freehold Royalties (TSX:FRU)
Overview: Freehold Royalties acquires and manages oil and gas royalty interests that generate production based, cash flow to support its dividend.
Operations: The business earns about CA$322 million from oil and gas exploration and production royalties, split between CA$157 million in Canada and CA$165 million in the US.
Market Cap: CA$2.7b
Freehold Royalties fits the Dividend Powerhouses theme because its royalty income is directly tied to production, giving investors exposure to energy cash flows without the heavy upfront drilling costs that traditional producers carry.
"Freehold leases its mineral rights (Mineral Title) or gross overriding royalty (GORR) to third-party operators and receives a "top-line" share of each barrel of oil or gas produced."
What really matters now is how one less visible shift in that production mix and pricing shapes the cushion behind today’s payout.
That shifting mix is the real story, and the full narrative for Freehold Royalties unpacks how Freehold Royalties’ production trends, pricing swings and payout ambitions could be quietly decoupling.

North West (TSX:NWC)
Overview: The North West Company operates grocery, convenience and discount retail chains that generate steady cash flow used to fund a recurring dividend.
Operations: North West earns about CA$1.48b from Canada and CA$1.14b from international markets, reflecting a balanced geographic revenue mix.
Market Cap: CA$2.6b
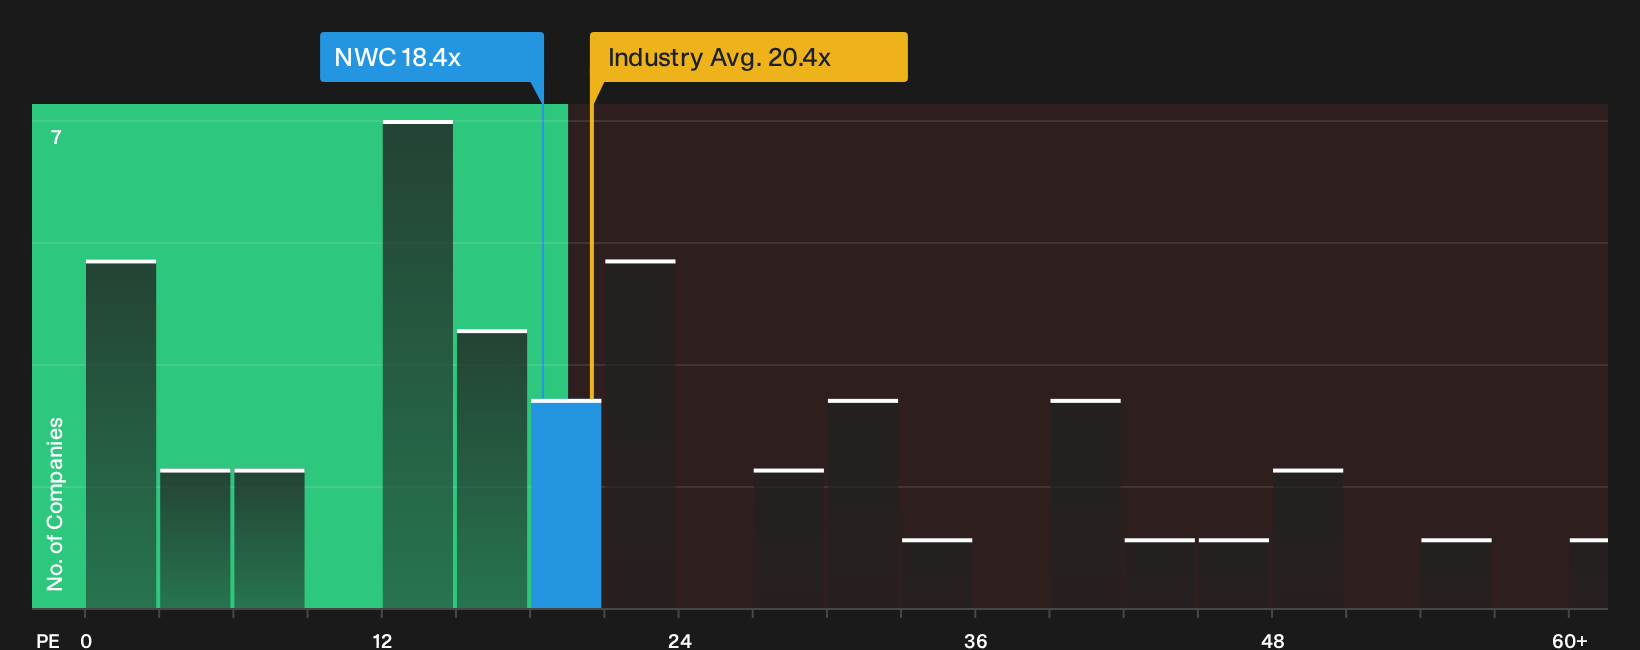
North West offers a 3.04% yield backed by cash-generating store networks, modest earnings growth and a P/E of 18.4x versus 35.6x for peers. Recent dividend growth and buybacks show a clear focus on income and capital returns, yet the payout still hinges on how one unseen cost pressure shapes future retail margins and cash coverage.
That unseen cost pressure is exactly what the analysis report for North West reveals, showing where North West’s margin squeeze could quietly turn into a stronger dividend story.
Seeking Fresh Alternatives Before They Fly
Markets move fast and the strongest stories rarely stay quiet for long. Catch fresh ideas with real breakout potential while they are still under the radar for now. Act now.
- Spot resilient balance sheets before momentum chasers arrive by scanning the curated list of solid balance sheet and fundamentals (7 results). It filters for fundamentals many investors only notice after prices start flying.
- Track sectors building real AI momentum and use the hand picked 92 AI infrastructure stocks to focus on businesses supplying the chips, data centers and tools behind that demand wave.
- Position ahead of the next metal cycle and run the focused 35 elite gold producer stocks to see gold producers that some investors only catch once prices have already broken out.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com