
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Lowe's (LOW) Drone Delivery Pilot
- Lowe's Companies recently launched a drone delivery pilot from its Matthews, N.C. store with Wing and DoorDash, offering select tools, paint supplies and household essentials delivered in as little as 20 minutes for DIY and Pro customers.
- The focus on light, last minute items under roughly 2.5 pounds per flight points to Lowe's testing whether faster convenience can reduce project delays and deepen engagement with higher value home improvement shoppers.
- We will now explore how Lowe's drone delivery pilot, focused on rapid small-item fulfillment, could influence the broader investment narrative.
Lowe's Companies Investment Narrative Recap
For a shareholder in Lowe's Companies, the core belief is that a large home improvement chain with US$90.4b in annual revenue can keep nudging market share higher while protecting margins, even as housing activity feels choppy. The near term swing factor is execution on omnichannel convenience and Pro engagement. The drone pilot looks incremental rather than transformative on its own, so it does not materially shift that big picture yet.
The bigger tension sits in flat 2026 comparable sales guidance, margin pressure and recent earnings volatility. EPS is projected to decline year over year in the upcoming November report while revenue is expected to rise. That mix keeps attention on cost control, integration of FBM and ADG, and progress on debt metrics as key short term risks.
The drone delivery launch sits naturally alongside Lowe's Companies efforts in same day options and digital tools like Lowes.com, the app and the Mylow AI agent. Together, these programs all point at the same operational goal: get more orders into higher throughput, data rich channels that can support productivity initiatives and keep service levels high for DIY and Pro customers.
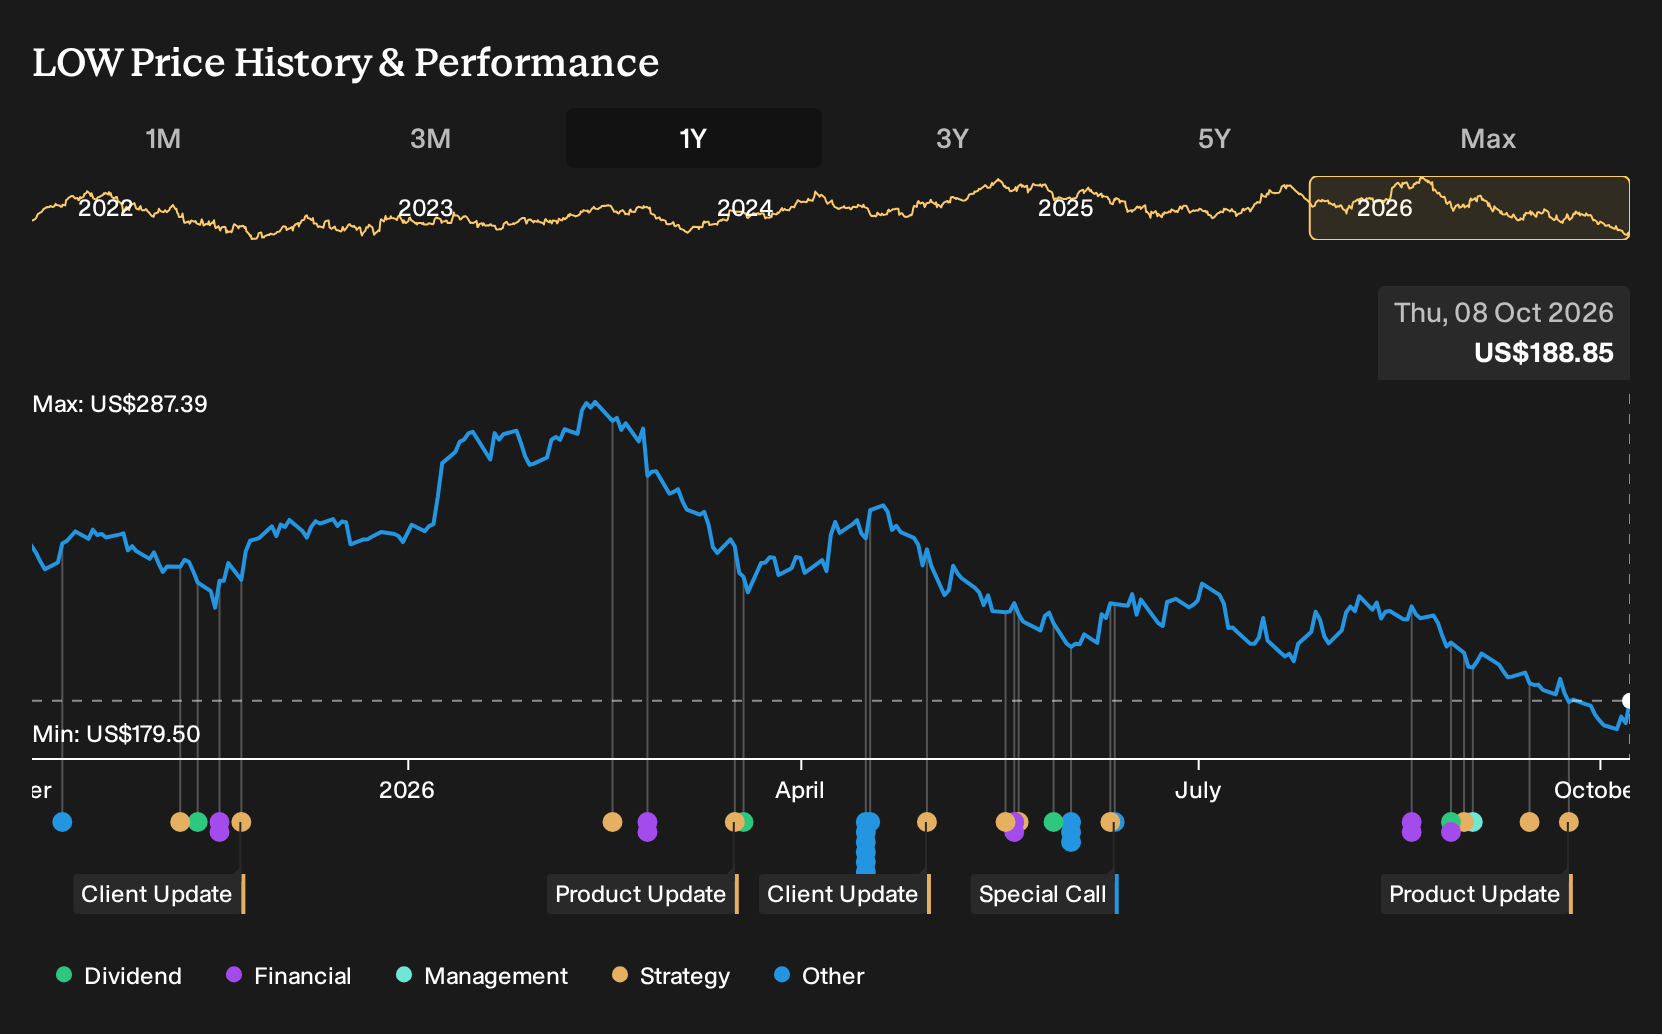
With shares down 12.2% over the past month and analyst expectations calling for a 6.54% EPS decline on 7.46% revenue growth in the next print, investors are already keyed into execution risk. In that context, the drone pilot is a small but visible proof point on logistics and speed. The heavier catalysts for the stock still revolve around how quickly digital growth, construction channel acquisitions and PPI efficiencies translate into steadier earnings and lower leverage.
Lowe's Companies' current analyst narrative points to US$99.5b in revenue and US$7.8b in earnings by 2029, built on expectations for 3.2% yearly revenue expansion and an earnings increase of about US$1.2b from US$6.6b today.
Uncover why Lowe's Companies' fair value indicates a 34% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$226.47 and US$252.30, so retail investors already show a tight but meaningful spread on what Lowe's Companies might be worth. When you set that against flat 2026 comparable sales guidance and earnings estimate pressure, you can see how opinions may diverge sharply. Explore the full range of views before deciding where you sit.
Explore 2 other Lowe's Companies fair value estimates, including one that suggests potential upside of up to 34% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Lowe's Companies research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Lowe's Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lowe's Companies' overall financial health at a glance.
Looking for more investment ideas beyond Lowe's Companies?
If the Lowe's Companies story has sharpened your thinking but you want a wider watchlist, use this moment to scan for other stocks that fit your risk, income or quality preferences using the Simply Wall St Screener.
- For investors hunting for quality at a sensible price, review a curated set of potential value opportunities in the 27 high quality undervalued stocks that may warrant closer attention.
- If capital protection and balance sheet strength matter most to you, focus on businesses screened for resilience and financial robustness in the list of solid balance sheet and fundamentals (25 results).
- Income focused investors can zero in on dependable payers by running through the 8 dividend fortresses to see which companies line up with your yield and stability goals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com