
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Dropbox (DBX) A Bargain As Buybacks And Cash Flow Support Its Valuation?
Dropbox (DBX) has come back into focus after a recent pullback in the share price, prompting investors to reassess what they are paying for a business-focused subscription platform.
Over the past few months, the share price has picked up, with a 16.96% 90 day share price return and a 26.77% year to date share price return. The 1 year total shareholder return of 17.04% points to momentum that has built rather than faded.
Extend that momentum lens beyond Dropbox and size up other subscription and software plays with strong recent moves using our curated list of 27 high quality undervalued stocks.
For Dropbox, that recent climb sits between two explanations. Is the market finally recognising the cash generation and subscription resilience here, or has sentiment simply swung too far ahead of what the fundamentals support?
Most Popular Narrative: 7% Overvalued
Dropbox closed at $34.14 against a narrative fair value of $31.80, which frames the recent share price strength as slightly ahead of the underlying estimates for cash flows and risk.
A combination of high free cash flow, a roughly 15% year over year reduction in diluted share count, a new US$400m revolving credit facility and an additional US$900m buyback authorization positions Dropbox to keep shrinking its share base. This can support growth in free cash flow per share and earnings per share even if revenue growth remains modest.
See why 10 investors see Dropbox as 7% overvalued.
Result: Fair Value of $31.80 (OVERVALUED)
Still, the Dropbox narrative can be knocked off course if AI driven products fail to lift subscriptions enough to offset higher infrastructure and security costs.
Find out about the key risks to this Dropbox narrative.
Another View On Dropbox’s Valuation
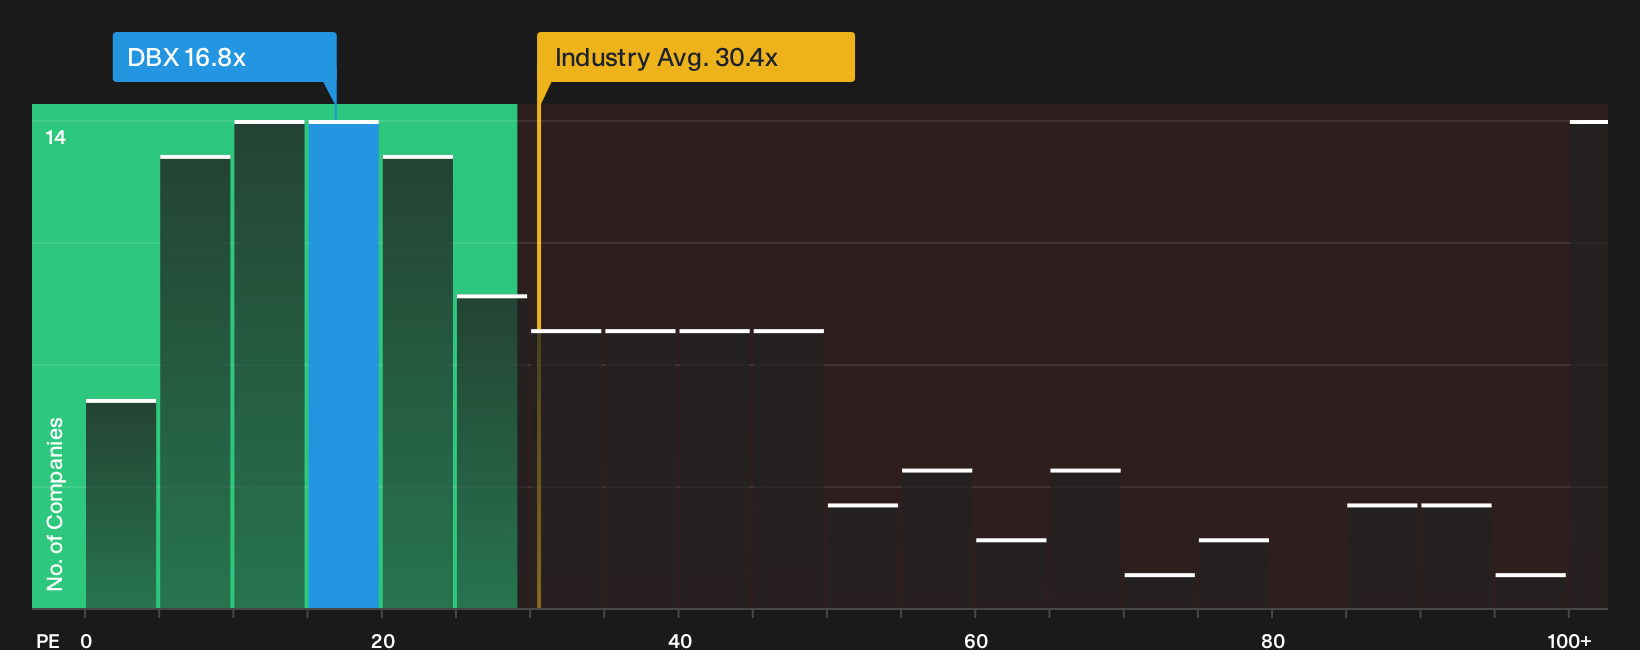
The earlier narrative fair value of $31.80 presented Dropbox as about 7% overvalued. A different perspective tells a very different story. On a P/E of 16.8x, the stock trades well below the US Software industry at 30.4x and peers at 33.8x, and even under its own fair ratio of 21.3x.
That gap suggests the market is pricing in more risk or softer prospects than those comparison points indicate. This could flag either a potential value trap or a possible mispricing that only becomes clearer as future earnings are reported.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of caution and optimism around Dropbox has you on the fence, do not sit with it for too long. Weigh the downside and the upside by digging into the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Dropbox?
If Dropbox has sharpened your thinking, do not stop here. Broader context helps you judge whether this stock really earns a place in your portfolio.
Line up potential high earners by scanning 8 dividend fortresses that can provide income while you weigh growth opportunities like Dropbox.
Spot opportunities with sturdier finances by reviewing the list of solid balance sheet and fundamentals (25 results) so you are not relying on one company to carry your risk profile.
Hunt for future standouts before the crowd by checking the 20 high quality undiscovered gems and give yourself more options than a single ticker ever could.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com