
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Goldman Sachs (GS) Plans More Than $500 Million In Special Equity Awards
- Goldman Sachs Group (NYSE: GS) is preparing special equity awards worth more than US$500 million for senior leadership.
- The awards are described as among the largest executive equity pools in the firm’s history.
- Payouts will depend on a mix of long term performance goals and how Goldman Sachs fares against industry peers.
- This new US$500 million special equity plan for top executives is worth weighing alongside the rest of our analysis. We have also spotted 2 warning signs worth knowing about at Goldman Sachs Group.
For a wider view on how income-focused opportunities compare with Goldman Sachs, it can help to look at 8 dividend fortresses.
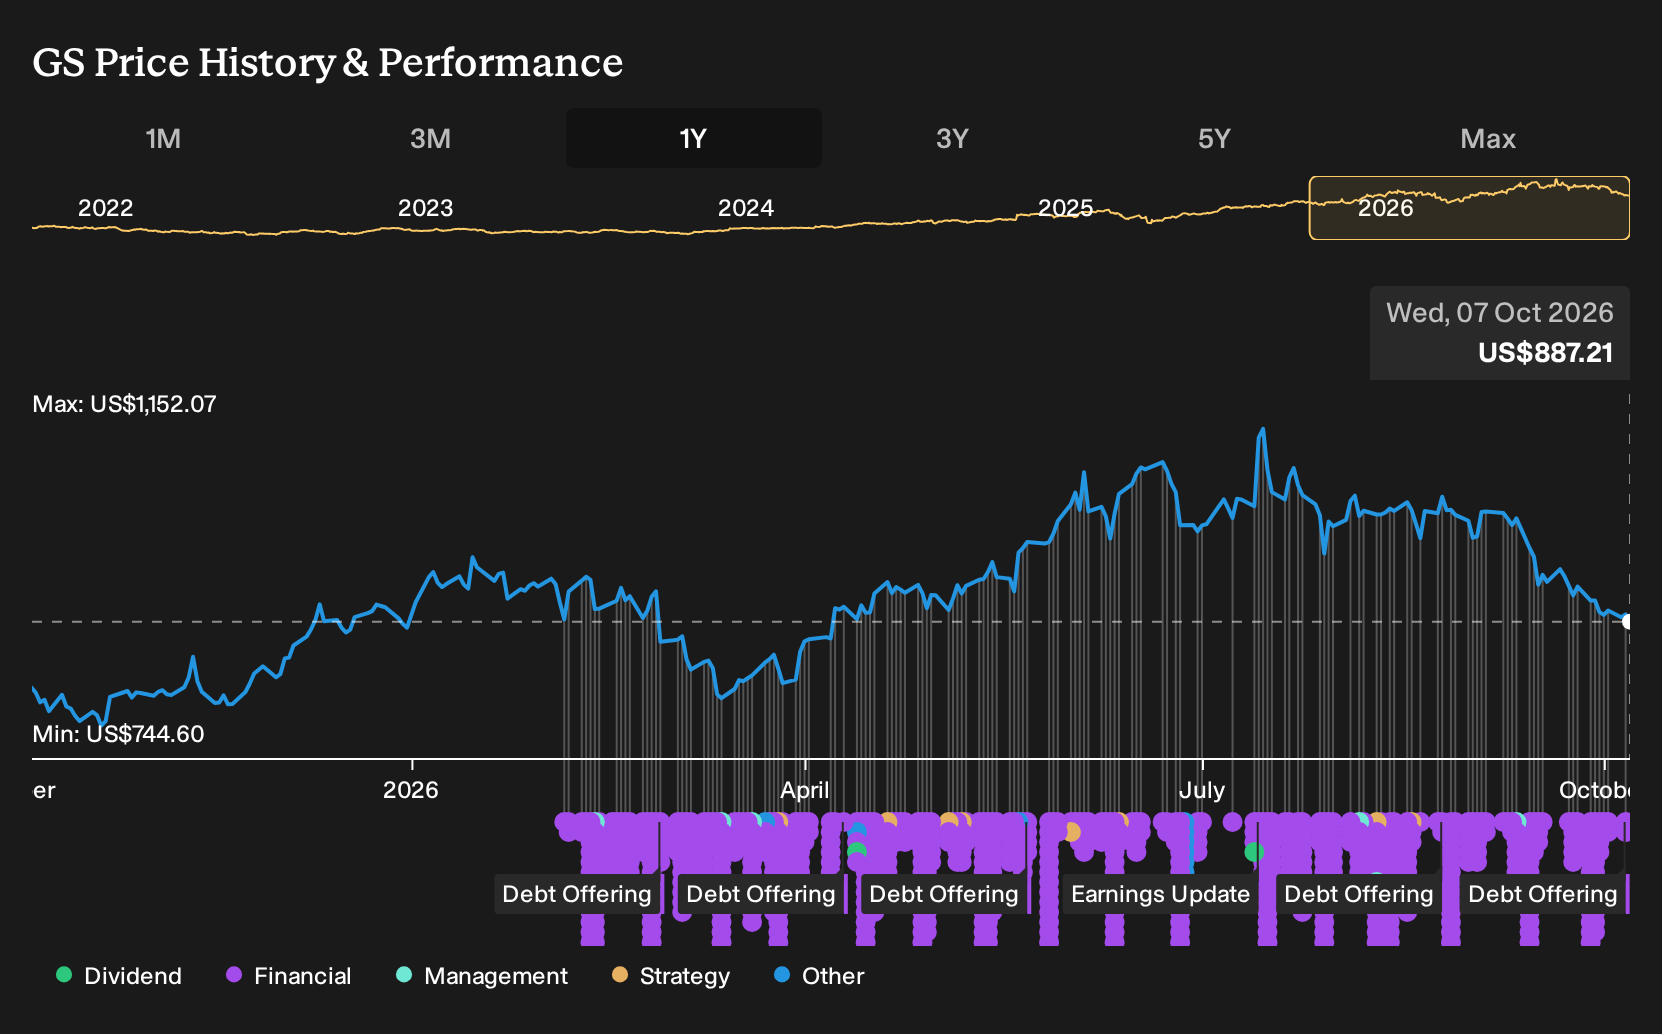
Goldman Sachs Group is a global capital markets heavyweight, providing investment banking, trading, and asset management services across multiple regions. Decisions on a US$500 million equity pool give a window into how leadership incentives are being aligned within a US$268.6b financial platform.
See which insiders are buying and selling Goldman Sachs Group following this latest news.
How a US$500 million equity pool feeds into the Goldman Sachs Group Narrative
The Goldman Sachs Group Narrative hinges on management pushing the mix further toward fee-heavy advisory, financing and asset management while using AI and process reengineering to keep costs in line with that expansion. A one off equity pool of this size lands squarely in that conversation, because it hardwires how those leaders are paid to pursue that shift.
"Firmwide technology and AI investment, reflected in lower headcount even as revenues grow and in management commentary on AI and process reengineering increasing productivity, supports the earlier view that automation and cloud can create operating leverage and potentially improve net margins and earnings power..."
See how the full story points towards a $1,117 fair value for Goldman Sachs Group.
The special awards directly reinforce the catalyst that analysts already highlight, which is leadership focus on fee-based businesses and technology-led efficiency. If those equity grants remain tied to peer-beating returns from advisory, financing and asset and wealth management, they keep the Narrative’s emphasis on compounding fee flows and operating leverage firmly on the table against rivals such as Morgan Stanley and JPMorgan Chase.
The same package also leans into one of the Narrative’s flagged risks, which is non-compensation costs and overall expense pressure if spending does not reset lower. A US$500 million pool for roughly 20 executives can be read as a strong retention signal, yet some shareholders may question it while guidance already points to more than US$500 million of higher near term non-compensation expenses and softer areas like FICC trading.
Whether this news looks attractive or worrying largely depends on whether your Narrative for Goldman Sachs is built around disciplined, efficiency-driven fee growth or around concern that rising costs and execution risks could erode those benefits over time.
Add Goldman Sachs Group to your Watchlist and get alerts as these catalysts play out.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com