
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Asian Growth Stocks With Insider Ownership And 114% Earnings Growth
As the Asian markets navigate through a period of volatility influenced by global economic uncertainties and fluctuating oil prices, investors are increasingly focused on identifying resilient growth opportunities. In this environment, companies with high insider ownership and robust earnings growth stand out as potentially promising investments, offering insights into management confidence and alignment with shareholder interests.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Shanghai Skychem Technology (SHSE:688603) | 31.8% | 67.7% |
| Meitu (SEHK:1357) | 23% | 26.7% |
| L&C BIOLTD (KOSDAQ:A290650) | 20.9% | 163% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gold Circuit Electronics (TWSE:2368) | 29.8% | 46.1% |
| Fulin Precision (SZSE:300432) | 10.8% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Here's a peek at a few of the choices from the screener.
PATEO CONNECT Technology (Shanghai) (SEHK:2889)
Simply Wall St Growth Rating: ★★★★★☆
Overview: PATEO CONNECT Technology (Shanghai) Corporation provides smart cockpit and vehicle connectivity support services in China and Hong Kong, with a market cap of HK$8.92 billion.
Operations: The company generates revenue primarily from Smart Cockpit Solutions amounting to CN¥4.39 billion and Vehicle Connectivity Support Services totaling CN¥72.36 million.
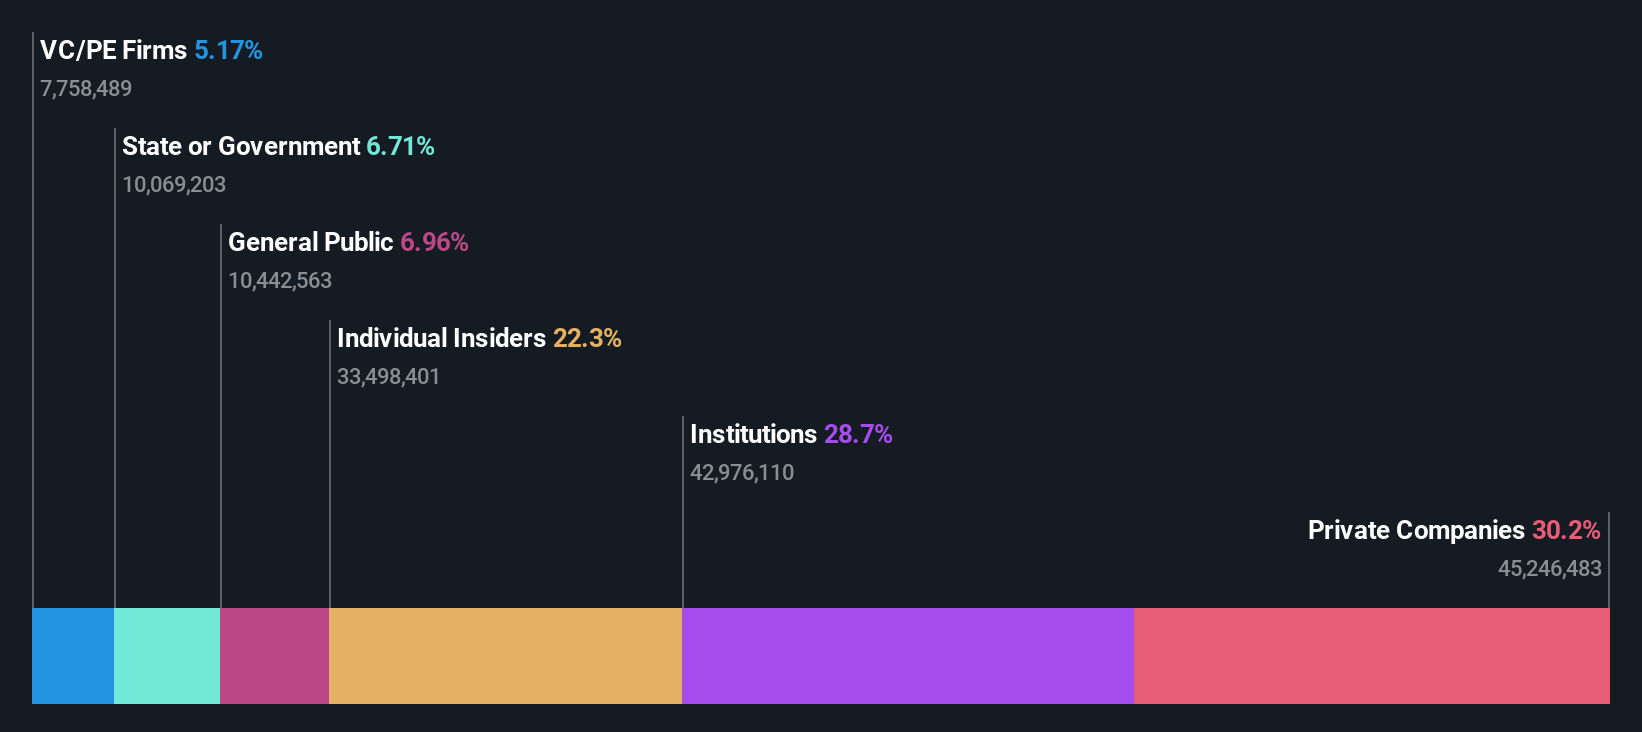
Insider Ownership: 20.9%
Earnings Growth Forecast: 115.0% p.a.
PATEO CONNECT Technology (Shanghai) demonstrates significant growth potential with high insider ownership and substantial insider buying over the past three months. The company's revenue is forecast to grow 28.9% annually, outpacing the Hong Kong market. Recent strategic collaborations, such as with Arm for AI innovation and securing project designations from major automotive groups, bolster its integrated "software + hardware + chip + cloud" strategy. However, PATEO faces challenges like a volatile share price and limited cash runway.
- Get an in-depth perspective on PATEO CONNECT Technology (Shanghai)'s performance by reading our analyst estimates report here.
- The valuation report we've compiled suggests that PATEO CONNECT Technology (Shanghai)'s current price could be inflated.
Shenzhen Dynanonic (SZSE:300769)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Shenzhen Dynanonic Co., Ltd focuses on the research, development, production, and sale of materials for lithium-ion batteries in China with a market cap of CN¥11.77 billion.
Operations: The company generates revenue of CN¥15.23 billion from its nano-lithium iron phosphate segment.
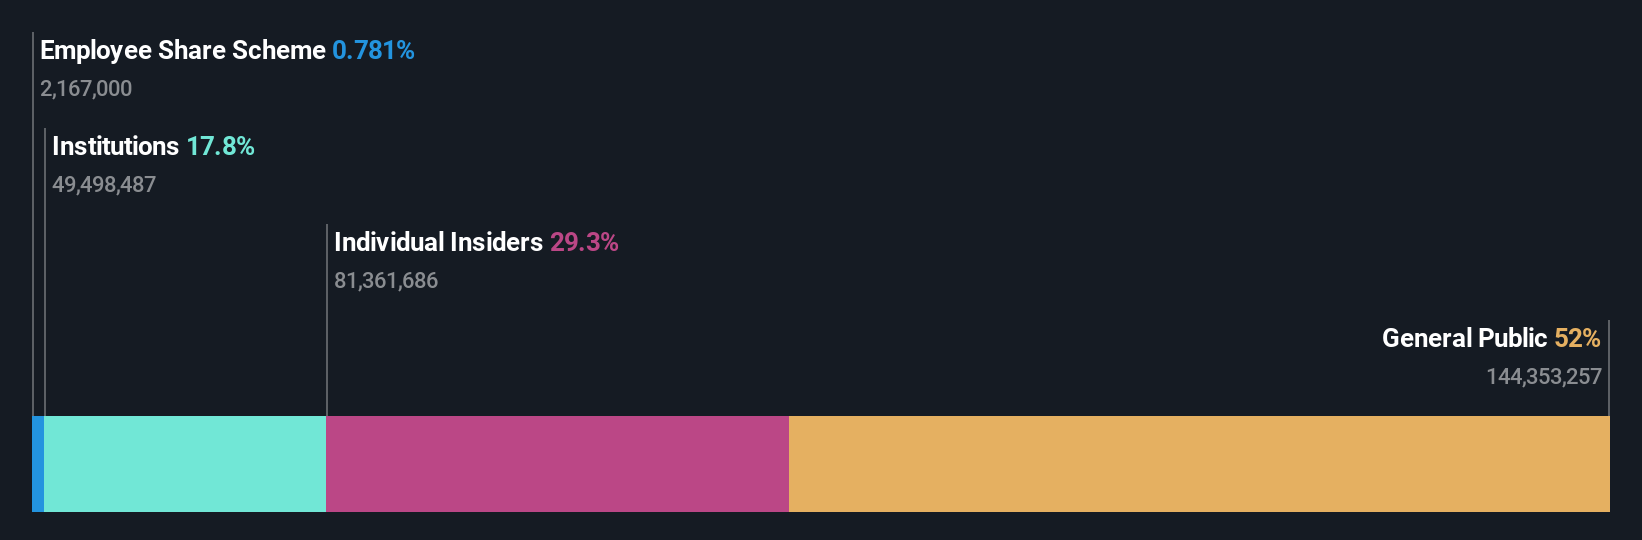
Insider Ownership: 26.5%
Earnings Growth Forecast: 55.7% p.a.
Shenzhen Dynanonic exhibits strong growth potential with high insider ownership, as evidenced by its impressive revenue surge to CNY 10.40 billion and a net income turnaround to CNY 455.45 million for the first half of 2026. Despite trading significantly below estimated fair value, it faces challenges like low forecasted return on equity and insufficient earnings coverage for interest payments. However, its expected annual profit growth of 55.7% surpasses the Chinese market average, indicating robust future prospects.
- Take a closer look at Shenzhen Dynanonic's potential here in our earnings growth report.
- Insights from our recent valuation report point to the potential undervaluation of Shenzhen Dynanonic shares in the market.
Fast Retailing (TSE:9983)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Fast Retailing Co., Ltd. is an apparel designer and retailer operating in Japan and internationally, with a market cap of approximately ¥22.95 trillion.
Operations: The company's revenue segments include UNIQLO International at ¥2.29 trillion, UNIQLO Japan at ¥1.09 trillion, GU at ¥340.08 billion, and Global Brands (Excluding GU) at ¥127.27 billion.
Insider Ownership: 38.8%
Earnings Growth Forecast: 10.9% p.a.
Fast Retailing demonstrates growth potential with high insider ownership, despite recent significant insider selling. The company forecasts revenue of JPY 4,450 billion and profit attributable to owners of the parent at JPY 560 billion for the year ending August 31, 2027. Earnings grew by 30.6% over the past year and are expected to grow faster than the Japanese market average. However, projected annual revenue growth remains below significant levels at 10.6%.
- Navigate through the intricacies of Fast Retailing with our comprehensive analyst estimates report here.
- According our valuation report, there's an indication that Fast Retailing's share price might be on the expensive side.

Make It Happen
- Navigate through the entire inventory of 495 Fast Growing Asian Companies With High Insider Ownership here.
- Curious About Other Options? Uncover 25 companies that survived and thrived after COVID and have the right ingredients to survive Trump's tariffs.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com