
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Biogen (BIIB), What Is Behind The Fresh Attention?
Biogen (BIIB) just released 52 week Phase 2 data from its AMETHYST trial of litifilimab in cutaneous lupus erythematosus, giving investors fresh clinical detail to weigh against recent share price gains.
For context, Biogen’s share price has climbed 22.84% year to date and the 1 year total shareholder return is 46.00%, while the 3 year and 5 year total shareholder returns show declines of 16.31% and 23.43% respectively. This suggests that recent momentum has picked up after a weaker longer run.
Scan beyond Biogen and look for other healthcare players with similar momentum using our curated list of 33 healthcare AI stocks as a starting universe for deeper research.
Biogen now trades below both analyst targets and some intrinsic value estimates, even after the litifilimab driven rally. Is that genuine mispricing, or is it the market’s way of flagging real risk in the story ahead?
Most Popular Narrative: 8% Undervalued
Biogen’s most followed valuation narrative pegs fair value at $238.18, modestly above the last close of $218.43. This puts the litifilimab news flow inside a much broader earnings and portfolio story.
The main factor is that Biogen successfully executes on its multi-wave growth model by converting late-stage programs in lupus, antibody mediated rejection, Dravet syndrome and gene therapy into commercial products, while maintaining cost discipline under its Fit for Growth framework.
The current valuation implies that Biogen stock is already pricing in a fair outcome in which the growth portfolio and immunology expansion offset ongoing multiple sclerosis erosion, without requiring a step change beyond the business performance described so far.
See why 61 investors see Biogen as 8% undervalued.
Result: Fair Value of $238.18 (UNDERVALUED)
Still, Biogen’s story can break if multiple sclerosis erosion bites harder than expected, or if newer launches like LEQEMBI and SKYCLARYS underwhelm in the market.
Find out about the key risks to this Biogen narrative.
Another View: Biogen Through The P/E Lens
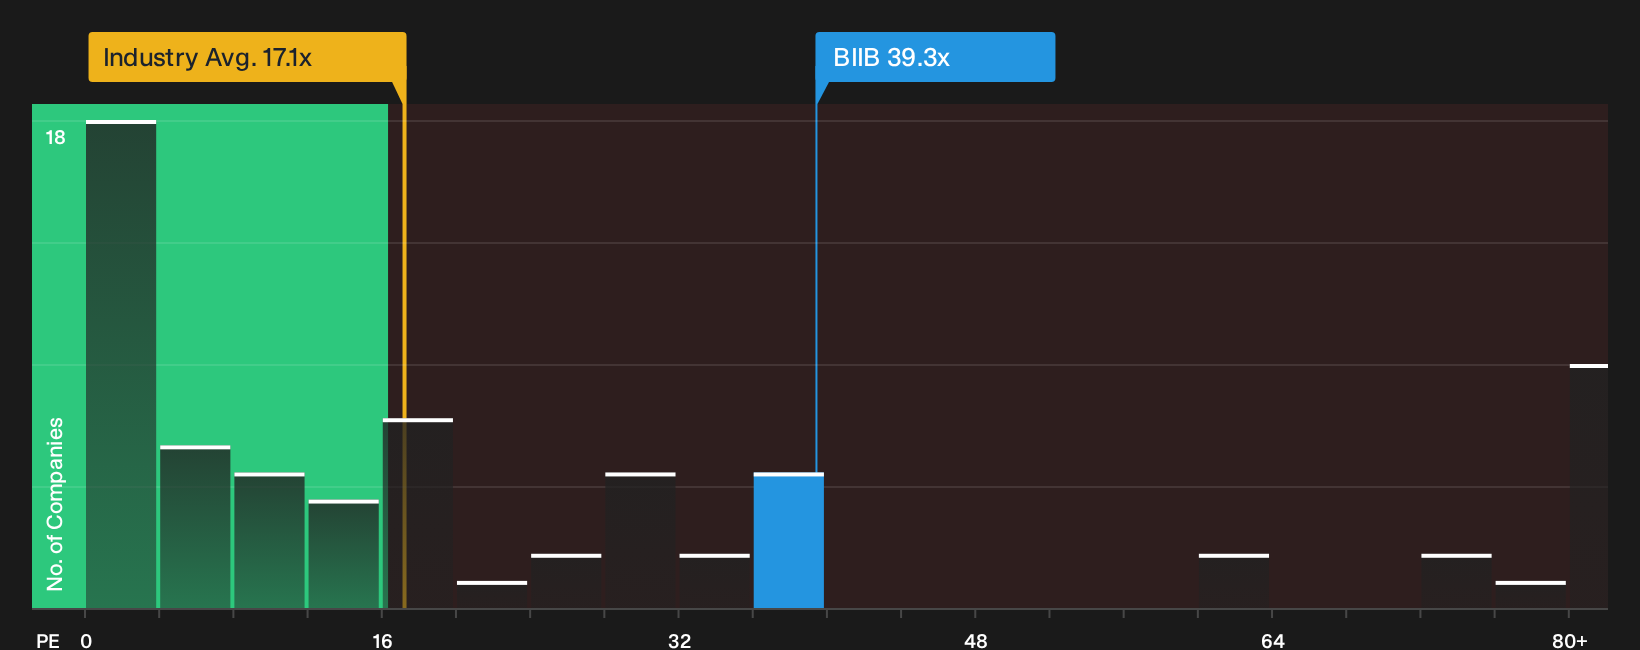
Biogen might look cheap against fair value estimates, yet the simple earnings multiple points in the opposite direction. The stock trades on a P/E of 39.3x, compared with 17.1x for the US Biotechs industry, 22x for peers, and a fair ratio of 29.9x that our work suggests the market could move toward over time.
If the share price eventually gravitates closer to that fair ratio, the gap between 39.3x and 29.9x becomes valuation risk rather than opportunity. The key question for investors is whether future earnings growth is strong enough to justify staying at a premium multiple, or whether the market could start pushing that P/E back toward the peer group.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted on whether Biogen still looks interesting after this run. Act while the details are fresh, and weigh both the upside and the red flags with 2 key rewards and 2 important warning signs.
Looking for more Biogen sized ideas?
If Biogen has you thinking harder about where to put fresh capital next, put that curiosity to work with a focused search for your next candidate.
- Target potential mispricings by scanning the 26 high quality undervalued stocks that pair quality fundamentals with prices that may not fully reflect them yet.
- Strengthen your income stream by reviewing the 8 dividend fortresses that combine higher yields with resilience checks on payouts.
- Sleep easier at night by filtering for the 31 resilient stocks with low risk scores that score well on financial health and volatility controls.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com