
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Happinet (TSE:7552) Could Be 41% Below Fair Value On Raised Guidance
Raised guidance puts Happinet in focus
Happinet (TSE:7552) raised its earnings guidance for the six months to September 30, 2026, after stronger than expected lottery, trading card, and capsule toy sales in its Toys and Amusement businesses.
Happinet’s guidance upgrade lands after a powerful run in the share price, with a 30-day share price return of 38.93% and a 76.73% share price return year to date. The 5-year total shareholder return of 728.28% points to momentum that has been building over a much longer stretch.
Scan beyond Happinet and see how other entertainment and consumer-focused stocks line up in our hand picked 75 high quality undiscovered gems list.
Happinet shares have already surged on stronger guidance and hit products in toys and amusement. The key tension now is straightforward: Is most of the rerating already spent, or does the current price still leave clear upside on valuation?
Price-to-earnings of 23.7x for Happinet: Is it justified?
On simple headline metrics, Happinet is not cheap. The stock trades on a P/E of 23.7x, which sits well above peers even after the recent share price surge from stronger Toys and Amusement demand.
The P/E ratio compares the current share price to earnings per share and is a quick way of seeing how much investors are paying for each unit of profit. For an entertainment trading group like Happinet, that figure often reflects how confident the market feels about the durability of lottery, trading card, capsule toy and software demand.
Right now the valuation gap is wide. Happinet carries a P/E of 23.7x compared with a peer average of 9.3x, and the broader JP Retail Distributors group on 14.9x. The stock therefore trades on a materially richer multiple than both its direct comparison set and the sector, which signals investors are willing to pay a premium for its earnings profile.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 23.7x (OVERVALUED).
DCF fair value suggests room between price and cash flow value
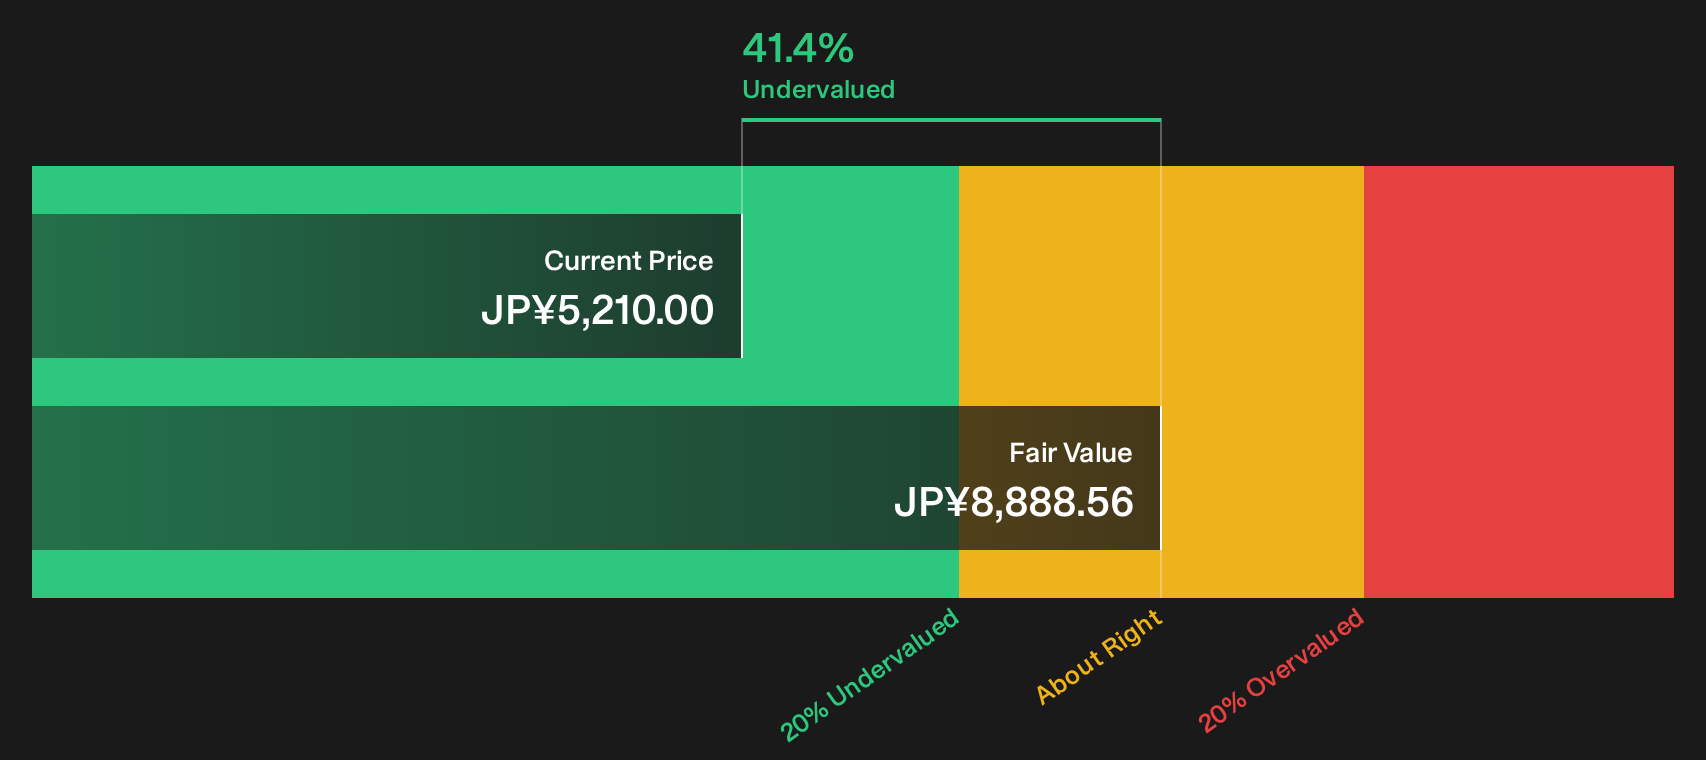
Alongside the rich P/E, the SWS DCF model points in a different direction. At a last close of ¥5,210, Happinet is flagged as trading 41.4% below an estimated future cash flow value of ¥8,888.56.
The DCF approach projects expected cash flows from the business and discounts them back to today using a required rate of return. That process focuses on the stream of cash the Toys, Video Games, Visual and Music, and Amusement operations are expected to generate over time, rather than just current earnings.
For Happinet, this framework highlights a gap between price and that modelled cash flow value, even with recent share price strength and a current net profit of ¥9,523m on revenue of ¥448,406m. The signal is that, based on these cash flow assumptions, the stock screens as materially below the level implied by the DCF output.
Look into how the SWS DCF model arrives at its fair value.
Result: DCF fair value of ¥8,888.56 (UNDERVALUED).
Still, Happinet’s reliance on Japan for all revenue and on discretionary categories such as toys and amusement means that any demand slowdown or shift in hit-driven cycles could quickly challenge today’s valuation premium.
Find out about the key risks to this Happinet narrative.
Another view on Happinet’s valuation
The SWS DCF model tells a different story to the high P/E. At a share price of ¥5,210, Happinet screens as trading 41.4% below an estimated cash flow value of ¥8,888.56, which flags a possible discount. So which signal do you trust more: earnings multiple or cash flow math?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Happinet for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted on what all this means for Happinet after such a strong run and split valuation signals? Act fast, pull up the full breakdown, and weigh the 2 key rewards and 2 important warning signs.
Ready to find more ideas beyond Happinet?
If Happinet has sharpened your focus on valuation gaps and quality, do not stop here. Broaden your watchlist with a few targeted stock searches.
- Zero in on potential mispricings by scanning a focused set of companies that screen as 14 high quality undervalued stocks.
- Lock in income ideas by reviewing a curated group of 32 dividend fortresses that combine yield with fundamental strength.
- Dial down portfolio stress by hunting for 22 resilient stocks with low risk scores that aim to balance resilience with return potential.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com