
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Missed AMC Global Media's Run? What Holders Had To Believe
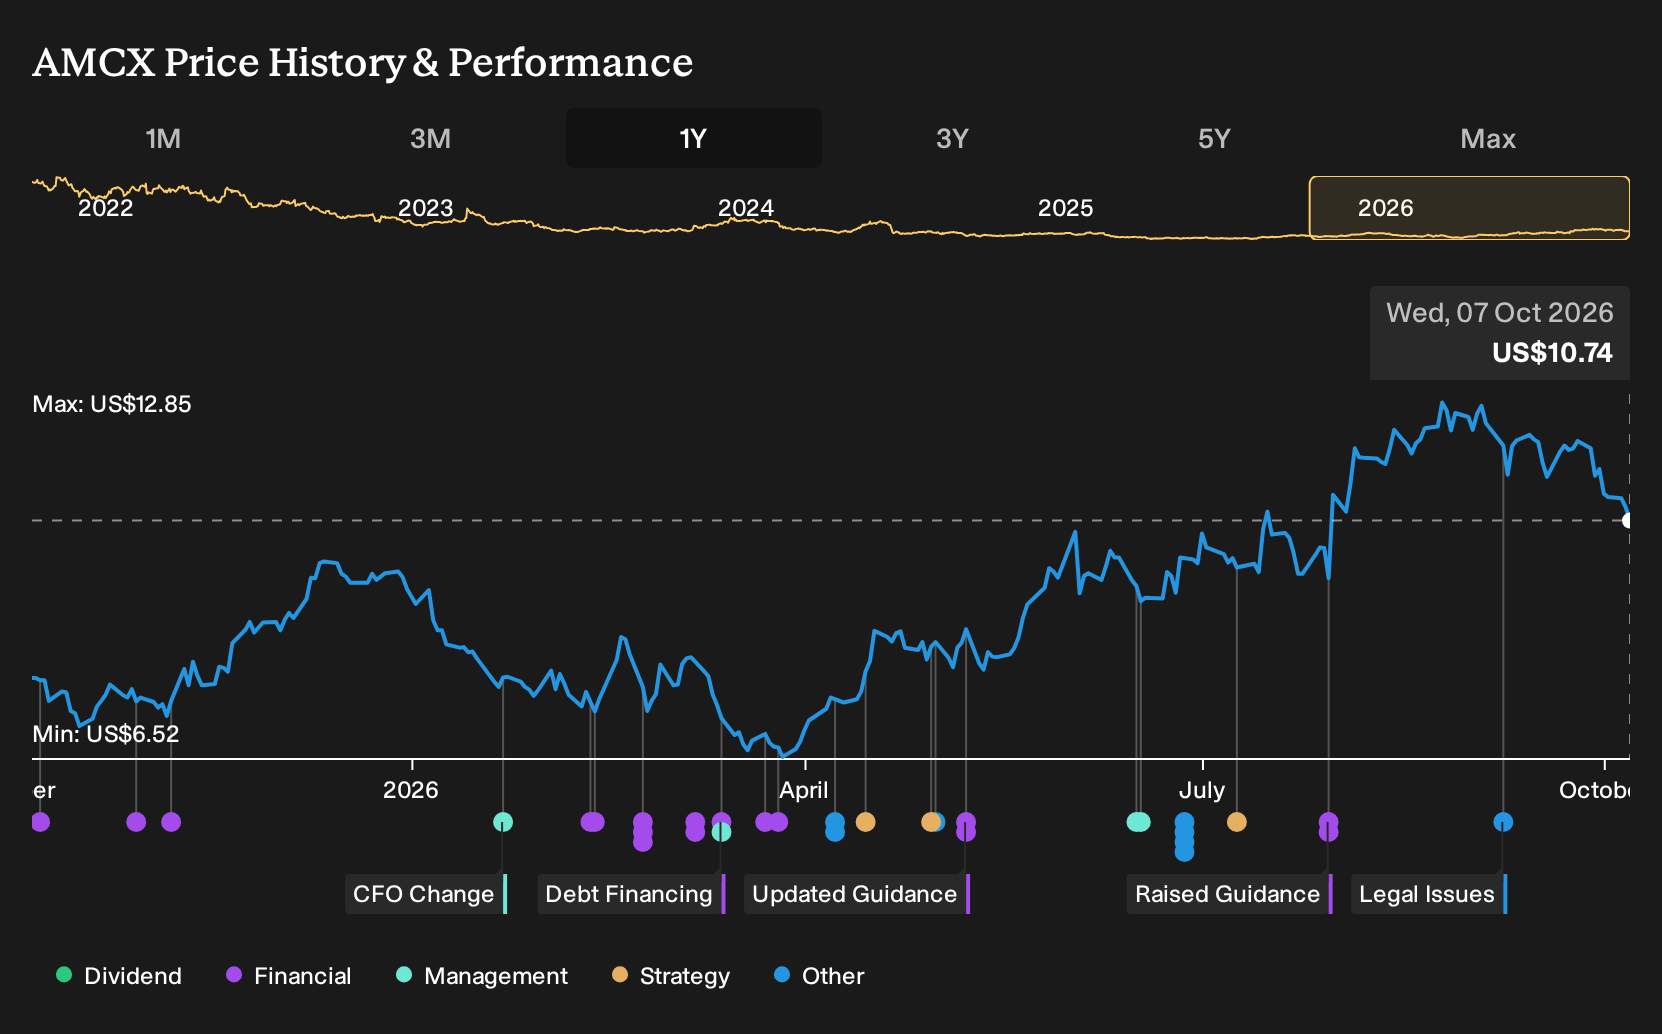
AMC Global Media spent the year juggling growing streaming ambitions with tougher quarterly figures, including Q2 2026 revenue of US$547.495 million and a net loss of US$21.943 million. Holding AMC Global Media over the past year would have returned 36.1%, including dividends. If you had been weighing a position back on 7 October 2025, what would you have needed to believe about targeted streaming, FAST channels, and aging franchises to press the buy button?
If the move has made AMC Global Media harder to judge, start where the gap is still open and scan 29 high quality undervalued stocks.
The Argument You Would Have Been Weighing On AMC Global Media
The shares cost US$7.93 at the start of the period, which left you choosing between two very different stories about AMC Global Media.
On the bullish side, the optimistic narrative pointed to a Fair Value of US$10, a price implied by assumptions built on targeted streaming, FAST expansion, and generative AI helping margins improve even as revenue drifted lower.
The more cautious view anchored on a Fair Value of US$6.5 and focused on shrinking linear TV income, modest 2% streaming subscriber growth, and reliance on aging franchises as key earnings risks.
What The Results Changed For The AMC Global Media Thesis
Q2 2026 results gave AMC Global Media investors a hard data point. Revenue slipped from US$600.024 million in Q2 2025 to US$547.495 million, and a profit of US$50.289 million turned into a net loss of US$21.943 million. With net margin moving from 8.4% to a loss of 4.0%, the profitability leg of the optimistic case stayed unproven, and the cautious argument on earnings risk gained support.
The lesson for any media stock is simple: when the bullish story leans on margin improvement, keep checking whether reported net margin actually turns up while revenue pressures play out.
What AMC Global Media's Price Now Asks You To Believe
AMC Global Media now trades at US$10.74. The selected Narrative places its Fair Value below that level, reflecting a view that the current quote already bakes in a generous read on streaming progress and licensing cash.
Netflix money, buybacks, and index inclusion all help the story. A buyer today effectively assumes recurring streaming and licensing income can outpace cord-cutting and aging IP, so the question is how the Narrative's concerns about scale, content costs, and competition weigh on that belief.
"Shrinking pay-TV subscribers and overreliance on aging franchises threaten revenue, as streaming growth and digital ads cannot fully offset traditional declines. Limited scale and rising content costs, combined with intense competition from larger platforms, continue to pressure margins and hinder long-term growth."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Looking One Step Beyond AMC
AMC Global Media still leans on streaming, pricing power and content monetisation working together. You can also consider a platform built around those same levers.
This other service focuses on turning existing audiences into steadier cash generation. It has shifted emphasis from chasing sign ups to deepening monetisation.
Management there pushes pricing moves, advertising tiers and buybacks instead of headline user counts. The overall model depends on how durable that cash engine becomes.
If that monetisation focus delivers, it could reshape what a mature streaming business looks like. If it disappoints, paying premium terms for perceived quality alone becomes harder to justify.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 18% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com