
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Planned Split Altering The Investment Case For Genuine Parts Stock?
- Genuine Parts plans to separate its automotive and industrial distribution operations into two independent, publicly traded companies by early 2027, with more detail on earnings profiles and capital needs expected at upcoming investor events.
- The split highlights how different the economics of NAPA focused auto parts distribution and the Motion industrial platform have become, which could reshape how investors think about Genuine Parts' cost structure, investment priorities, and long term profit drivers in each segment.
- This article examines how Genuine Parts' investment narrative is influenced by the planned split of its automotive and industrial units.
Scan how other distributors and parts suppliers are positioned for similar breakups or spin offs by working through the hand picked list of solid balance sheet and fundamentals (25 results).
Genuine Parts Investment Narrative Recap
To own Genuine Parts, you need to believe the core distribution engine in automotive and industrial parts can turn its current revenue base into healthier margins over time. The thesis leans on restructuring, supply chain work and the coming split into two listed entities. In the near term, the most important catalyst is still execution on cost savings and operational upgrades rather than the separation itself.
The biggest risk today is that inflation in health care, freight and rent, plus any further cost shocks, keeps lifting SG&A faster than sales. With net margins sitting around 0.1% after a large one off loss, there is very little cushion if the restructuring, new NAPA distribution centers or the separation timeline run into delays or complexity.
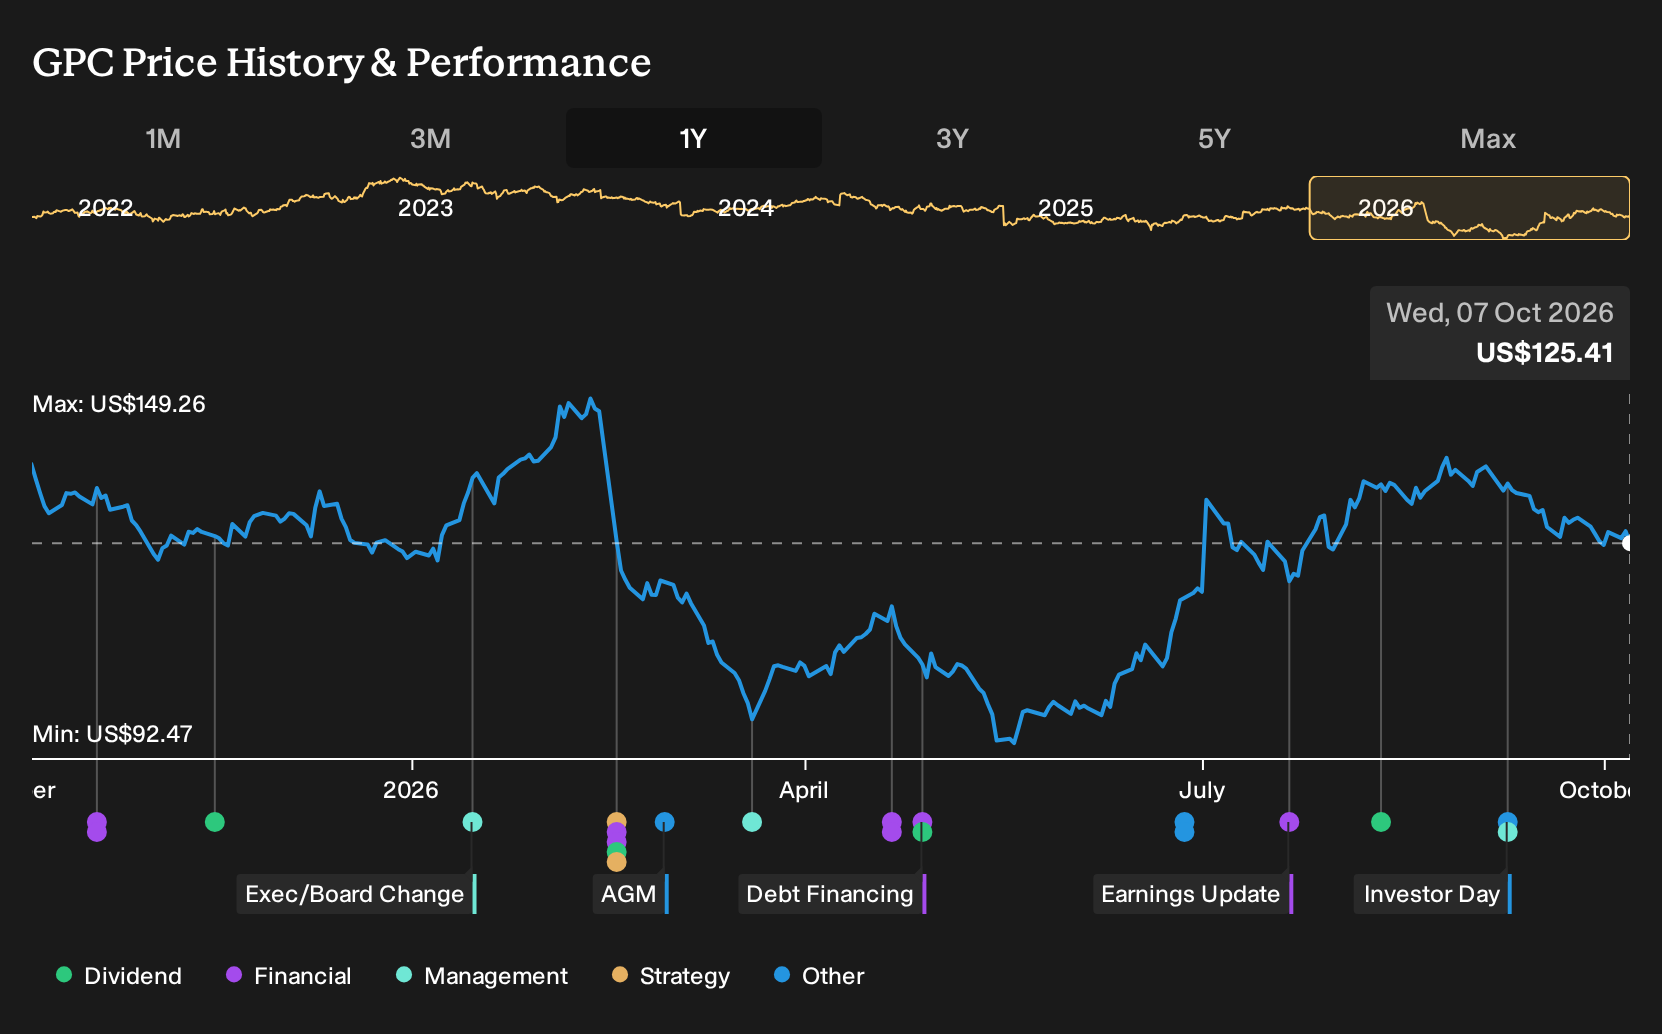
The planned separation of Genuine Parts into Global Automotive and Global Industrial by early 2027 is the announcement that ties most directly to the current story. Investors get a clearer view of two distinct operating profiles, including capital needs, margin structures and how each platform uses technology, M&A and inventory management to support earnings.
Upcoming investor days, where management intends to outline standalone earnings profiles and cost allocations, effectively become the key event to watch. The separation, combined with the multiyear restructuring program and supply chain modernization, also concentrates execution risk. Any stumble here could matter more because the margin base is thin and the dividend is not well covered by earnings.
What The Current Genuine Parts Forecasts Assume
Genuine Parts' current analyst narrative leans heavily on a sizeable reset in profitability rather than a dramatic acceleration in sales. Consensus numbers assume revenue grows by 4.1% per year over the next few years while net margin lifts from roughly 0.1% today to 4.9% by 2029. On those figures, earnings would step up from about US$32.8 million today to US$1.4b around 2029, which is an earnings increase of roughly US$1.37b off a very low base.
Genuine Parts' narrative projects US$28.3b revenue and US$1.4b earnings by 2029. This requires 4.1% yearly revenue growth and an earnings increase of roughly US$1.37b from about US$32.8 million today.
Uncover why Genuine Parts' fair value indicates a 12% potential upside to its current price, a discount that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Some of the most optimistic analysts frame the Genuine Parts split as a pure revenue and earnings catalyst. They were already expecting about US$28.4b of sales and US$1.6b of earnings by 2029, compared with consensus forecasts of US$28.3b and US$1.4b. That wide spread shows how sharply opinions differ and invites you to reassess both narratives after this news.
Explore 3 other Genuine Parts fair value estimates, including one that suggests there could be as much as 92% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Genuine Parts research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Genuine Parts. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Genuine Parts' overall financial health at a glance.
Looking For More Investment Ideas Beyond Genuine Parts?
If the Genuine Parts story has you rethinking how you spread risk and opportunity across your portfolio, it can help to line it up against other businesses with clear balance sheets, income profiles, and capital needs. The Simply Wall St Screener lets you do that in a structured way so you are not relying on headlines or hunches.
- For investors who want potential mispricings backed by fundamentals, start with a curated set of quality companies trading at what may be appealing levels through the 29 high quality undervalued stocks.
- If resilience matters more than excitement for your next idea, focus on businesses that score well on financial strength using the 31 resilient stocks with low risk scores.
- Those looking for ideas that the wider market may not be paying close attention to can scan a focused pool of lesser known opportunities via the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com