
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Strive (ASST) Getting Too Pricey Relative To Book Value?
Strive has delivered a sharp year to date rebound, yet its uneven performance over the past year leaves a clear question for you as a shareholder. Is the current US$28.19 share price still grounded in the company’s book value, or has the market moved ahead of what the balance sheet can justify?
- The stock is up 63.0% year to date, which puts real pressure on the question of whether the rally is still anchored to Strive’s underlying net assets.
- The business model depends heavily on how efficiently capital on the balance sheet is turned into earnings and cash flow, which can meaningfully shape how much weight you give to book value when judging today’s price.
- Your read on Strive is one view; the desks covering it have another. See what analysts think Strive's shares could be worth.
The stock’s next move may depend on whether Strive’s current market value lines up with what its book value suggests the business is worth.
If you want more context around whether Strive’s book value supports today’s price, it can help to compare it with other companies screened for solid balance sheet and fundamentals stocks screener (25 results).
Does Strive Look Pricey on Book Value?
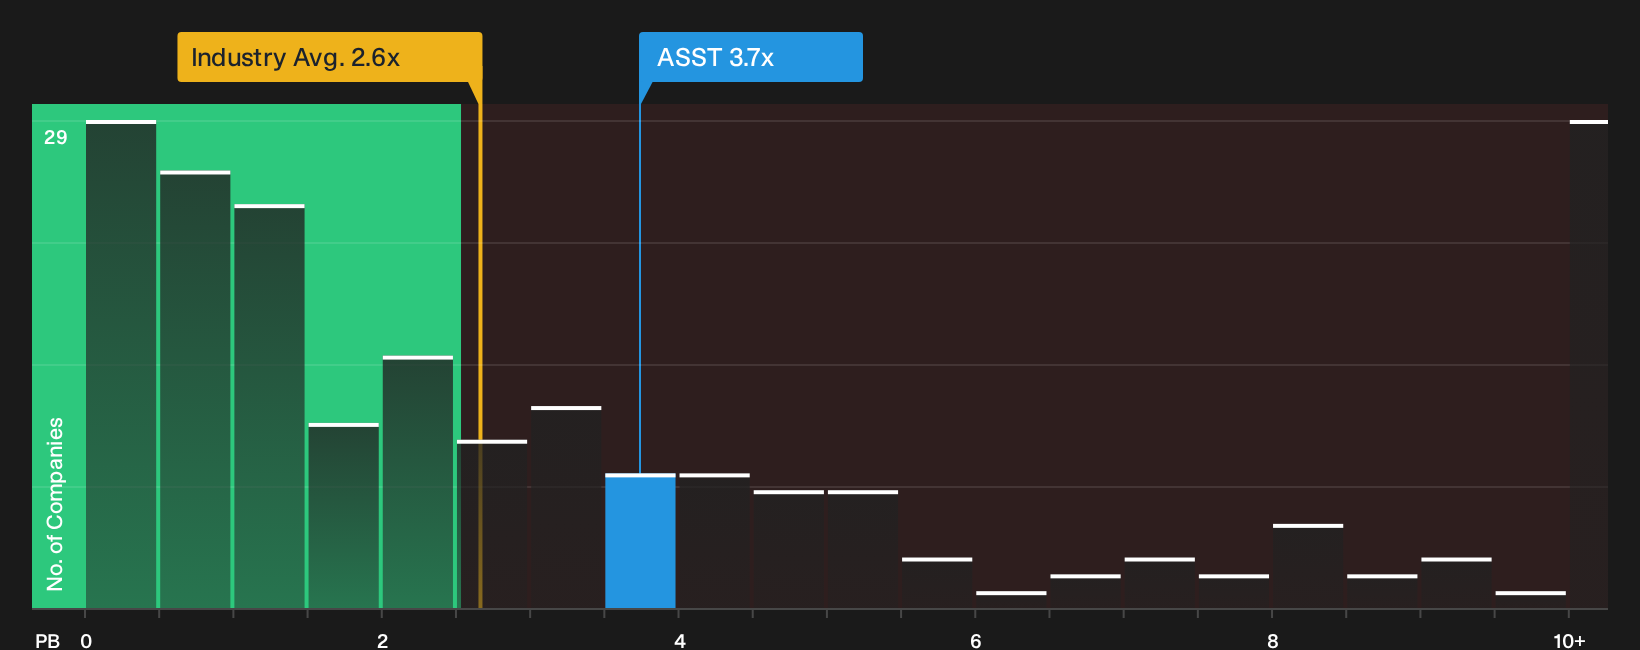
P/B works well for Strive because the business still leans heavily on its balance sheet and net assets. On this measure, the stock trades at about 3.7x book value, which is higher than the Medical Equipment industry average of roughly 2.6x. That premium suggests investors are paying more per dollar of net assets than they typically do for similar healthcare hardware businesses.
Peers as a group trade on an even richer multiple of around 7.6x book, so Strive does not look stretched against that subset but still screens overvalued against the wider sector. For you as a shareholder, the key question is whether Strive’s asset base and future profitability justify paying above the broader industry norm on book value alone, or whether that gap signals that expectations have already run ahead of the balance sheet. Explore the numbers behind Strive's P/B valuation.
The Strive Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/B debate on Strive leaves off by spelling out which combinations of future growth, profitability and earnings power would need to hold for the shares to be worth materially more or less than the current price. Each scenario ties a fair value estimate to a particular mix of potential catalysts and key risks for Strive, which lets you track over time which storyline comes closest to how the business actually develops on the ground.
A clear, written Narrative on Strive puts hard numbers around where its growth, margins and execution would need to head from here for today’s P/B multiple to look sensible over time. That kind of blueprint makes the assumptions behind your own view explicit, so you can test them as new results and trading updates arrive.
Share your own Narrative for Strive and set out the assumptions behind your valuation.
Before you act on Strive’s valuation, there is one more lever to examine
Numbers only tell part of the story for Strive, because the people setting priorities and the way their pay is structured can tilt outcomes in your favour or against you. See who runs Strive and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com