
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Undervalued Stocks Trading At Least 28% Below Fair Value
AI linked goods are driving global trade growth and keeping cargo planes full out of Asia, even as tariffs and conflicts bite. Cash rich businesses that benefit from this resilient demand yet trade below what their future cash flows imply can create a rare setup for patient investors. This article highlights three such undervalued cash flow stories from our screener and explains why each stock may warrant a closer look at this time.
The three stocks covered below are only a small sample, as the full screen surfaced 462 more businesses with cash flow profiles and valuation gaps that may be just as compelling for patient investors willing to do the extra work.
To size up that wider opportunity set efficiently, head straight into the Undervalued Stocks Based On Cash Flows screener to identify, compare, and analyze the highest conviction cash flow ideas for your watchlist.
Berkshire Hathaway (BRK.A)
Berkshire Hathaway ties neatly into this cash flow driven list through its insurance and reinsurance float, which helps fund a sprawling mix of freight rail, energy, manufacturing, retail and services, alongside a very large investment portfolio.
Berkshire Hathaway generates sizeable revenue across manufacturing at about US$83.0b, McLane at roughly US$50.3b, Pilot Travel Centers at US$47.8b, GEICO at US$45.1b, service and retailing at US$44.7b, Berkshire Hathaway Energy at US$26.9b, BNSF at US$24.6b, and its other insurance units above US$44.0b combined, giving the group a broad base to support its roughly US$1.1t market cap.
"The baton has officially been passed. Following the May 2026 Berkshire Hathaway Annual Meeting, the first with Greg Abel at the helm as CEO and Warren Buffett watching proudly from the front row, the conglomerate's underlying thesis remains completely intact."
What really matters for investors now is how one quiet shift inside the cash engine eventually filters through to margins and long term compounding.
That quiet shift sits at the heart of the full narrative for Berkshire Hathaway, where Berkshire Hathaway’s evolving cash engine, capital allocation and risk trade offs come into sharp focus.

Ansell (ASX:ANN)
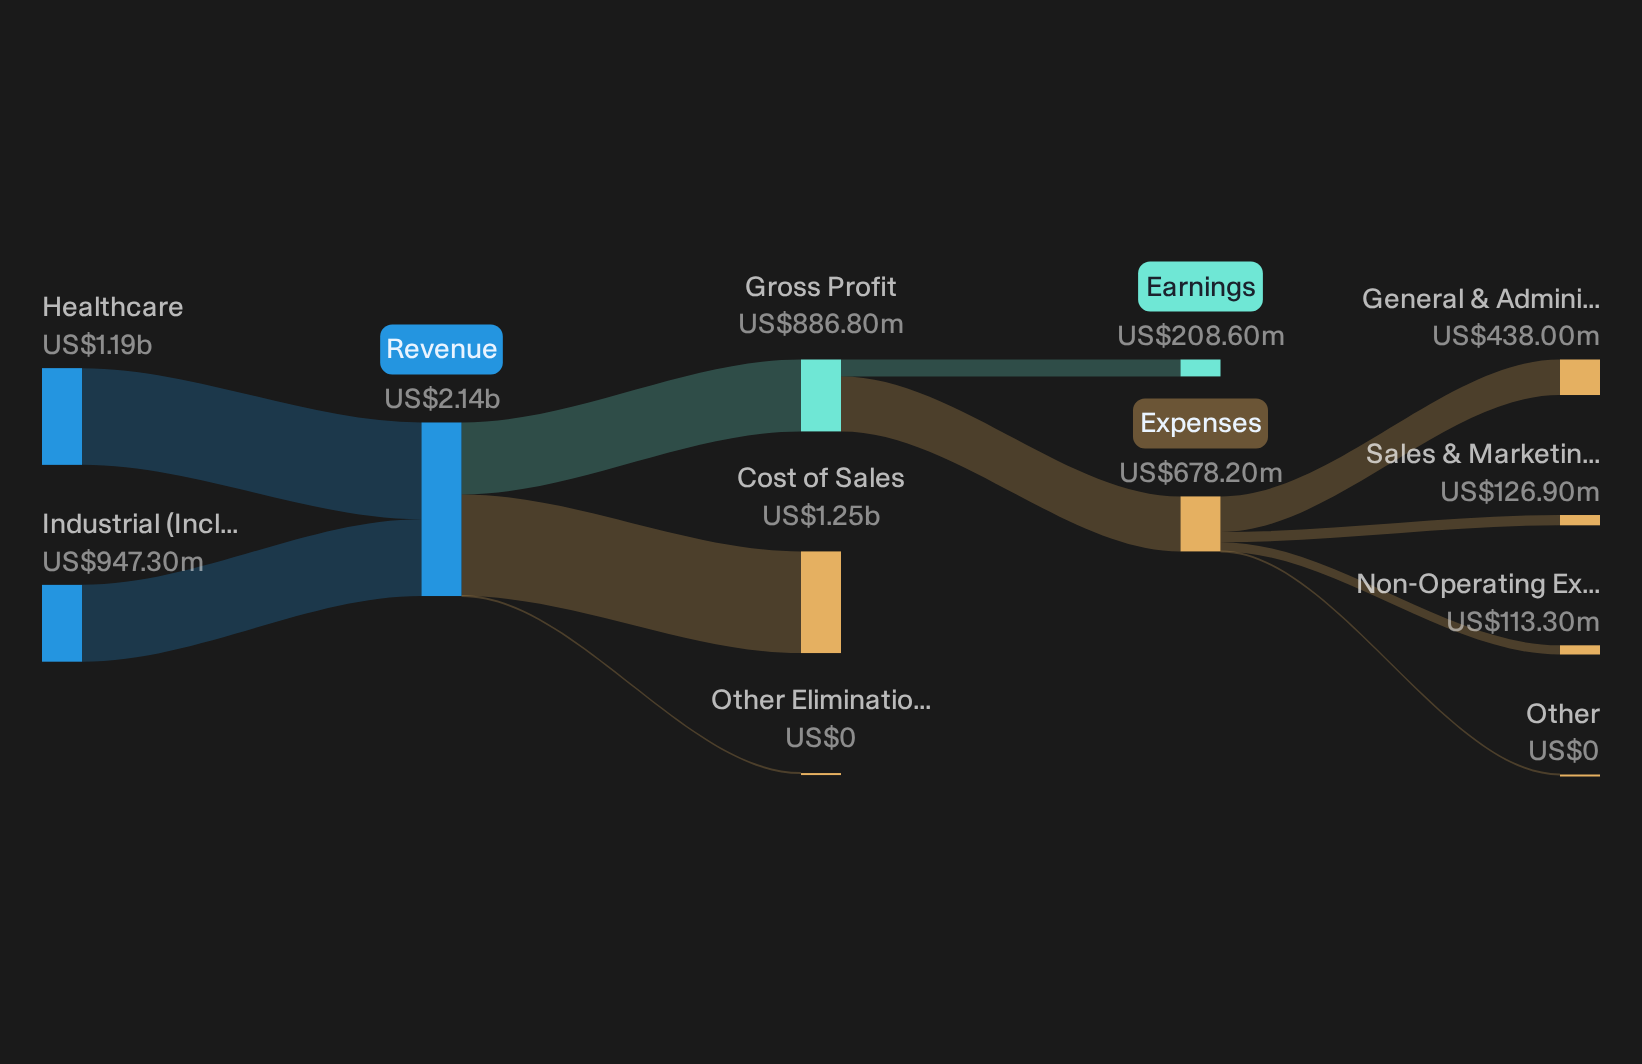
Ansell supplies hand and body protection gear to hospitals, labs, factories and logistics hubs worldwide, with the Healthcare glove line providing the clearest fit for this cash flow screen as it generates recurring sales that can be assessed against the firm’s A$6.3b market value.
"Ansell is well placed to capture increased structural demand in PPE, driven by tightening workplace-safety regulation, rising healthcare and hygiene standards, and accelerating industrialisation in emerging markets."
What really shapes the payoff for long term investors is how one quiet cost and efficiency shift feeds through to margins and reinvestment capacity.
Those shifts are exactly what the full narrative for Ansell unpacks in detail, highlighting where Ansell’s PPE demand, pricing power and reinvestment plans could be pulling apart.
Kalmar Oyj (HLSE:KALMAR)
Kalmar Oyj supplies heavy material handling equipment and recurring lifecycle services for ports and logistics hubs worldwide, with about €1.2b from Equipment and €619 million from Services supporting its cash flow profile against a roughly €2.4b market value.
For investors focused on cash flow backed value, Kalmar Oyj brings a mix of heavy equipment sales and sticky lifecycle services that ties directly into the screener’s focus on discounted future cash generation, while its spending plans raise an important question on how that value is realised.
"The long term push toward electrification, including the new lithium ion battery platform, requires continuing investment and supply chain reconfiguration. This could outpace the earnings benefits from the Driving Excellence program and compress net margins if savings do not fully cover higher R&D and sourcing costs."
What matters next is how one unresolved pressure shapes the balance between healthy service cash flows and the profitability investors are counting on.
That tension is exactly what the full narrative for Kalmar Oyj unpacks, revealing how Kalmar Oyj’s cash rich services may be masking upside if electrification investment lands cleanly.

Seeking Fresh Alternatives Before Others?
Fresh opportunities do not wait. Breakout themes gain momentum, under the radar for now, then fly once the crowd catches on. Scan these ideas while it matters and act now.
- Target reliable income by reviewing a curated pool of businesses in the 8 dividend fortresses before yields change and the best opportunities are crowded out.
- Focus on future-critical infrastructure by assessing companies in the 43 power grid technology and infrastructure stocks while valuations still reflect today’s grid and not potential future upgrades.
- Evaluate the next wave of automation by reviewing select opportunities inside the 88 robotics and automation stocks as robotics adoption continues to develop.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com