
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is AptarGroup (ATR) Undervalued As Its Pharma Push Draws Fresh Attention?
AptarGroup (ATR) is back in focus after fresh attention on its role supplying drug delivery and consumer dispensing solutions across pharma, beauty and closures, prompting investors to reassess how the business earns its revenue.
Recent trading has been softer, with a 1 month share price return of down 5.5% and a year to date share price return of down 1.7%, while the 1 year total shareholder return is down 7.1%. That pattern indicates weaker near term momentum for AptarGroup as investors reassess its growth potential and the perceived risk related to its pharma and beauty exposure.
Capitalize on the renewed focus on AptarGroup by lining it up against a hand picked list of solid balance sheet and fundamentals (25 results) to see how its profile compares.Bulls see AptarGroup’s pharma and beauty mix and its recent annual revenue and profit growth as underappreciated. Bears point to the weaker share price trend. The valuation work now has to show which side has the stronger case.
Most Popular Narrative: 29% Undervalued
At a last close of $120.43 against a narrative fair value of $170.14, the current pricing suggests investors are still conservative on AptarGroup’s long term earnings power.
Ongoing work to move from component supplier to a more integrated drug delivery and services partner, including formulation, analytical and regulatory support, clinical filling and digital patient tools, increases customer dependence on AptarGroup and can support higher value revenue and more resilient net margins.
See why 7 investors see AptarGroup as 29% undervalued.
Result: Fair Value of $170.14 (UNDERVALUED)
Still, AptarGroup’s story can fray if emergency medicine destocking weighs longer than expected, or if Beauty and Closures margins remain under pressure.
Find out about the key risks to this AptarGroup narrative.
Another View: AptarGroup Through The P/E Lens
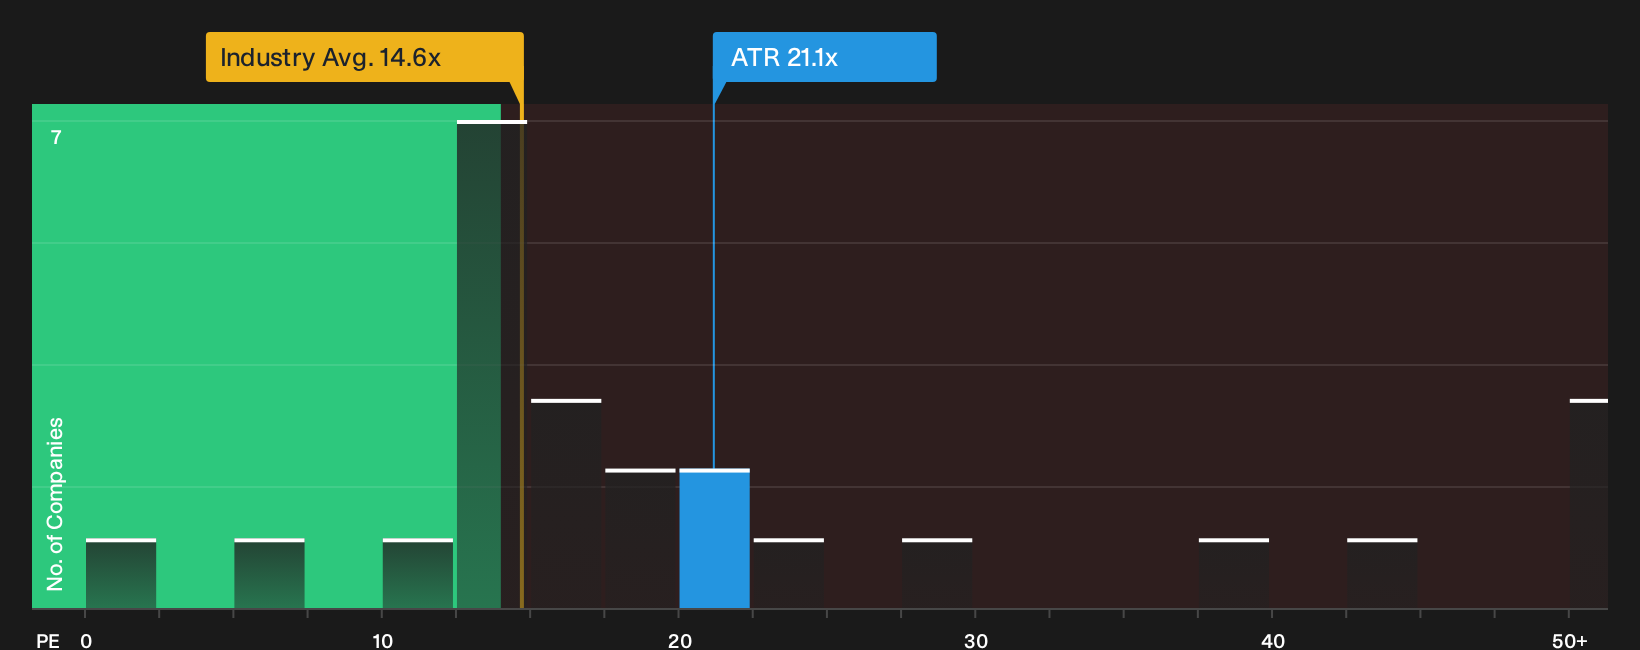
That 29% narrative discount on AptarGroup contrasts with what the P/E ratio is saying. At about 21.1x earnings versus a fair ratio of 17.6x, and against the global packaging group on 14.5x and peers on 16.2x, the stock carries a richer tag. Is the Pharma story strong enough to justify paying up?
To pressure test that premium and see what the numbers imply if the market moves toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on AptarGroup can easily pull you in both directions, so move quickly, review the underlying data and weigh both the 4 key rewards and 2 important warning signs.
Hunting For More Ideas Beyond AptarGroup?
Do not stop with AptarGroup. Use the screener to quickly surface fresh opportunities, compare quality signals side by side and keep your watchlist working harder for you.
- Target stronger balance sheets by scanning a list of solid balance sheet and fundamentals (25 results) that already filters for financial resilience and sturdier fundamentals.
- Spot potential mispricings by reviewing a focused 29 high quality undervalued stocks that blends quality markers with pricing signals.
- Prioritise income potential by tracking a curated 8 dividend fortresses that concentrates on higher yielding stocks with more robust profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com