
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Nordson (NDSN) Could Be 6% Below Fair Value On Higher 2026 Guidance
Nordson (NDSN) moved into the spotlight after management raised its fiscal 2026 sales guidance and completed an acquisition aimed at expanding the precision agriculture portfolio.
Against that backdrop, Nordson’s share price has climbed 14.43% over the past 90 days and 35.95% year to date, while the 1 year total shareholder return of 41.59% and 3 year total shareholder return of 49.35% point to momentum that long term holders have already experienced.
Scan for other industrials showing similar guidance momentum and acquisition driven growth by using our curated list of solid balance sheet and fundamentals (25 results) as the starting universe.
Bulls view Nordson’s higher guidance and recent acquisition as support for the elevated share price. Bears worry the optimism for 2026 is already reflected in the valuation. The next step is to see which side gains stronger support as the analysis develops.
Most Popular Narrative: 6% Undervalued
Nordson's most followed narrative framework points to a fair value of $349.71 versus the last close at $327.69, which implies modest upside if the long range assumptions on growth, margins, and discount rate hold.
Demand for advanced technology solutions is accelerating, especially in semiconductor packaging and electronics assembly, as customers ramp capacity for AI, cloud, and advanced consumer devices. Nordson's exposure to the back end of these markets and its ongoing new product launches are expected to drive sustained revenue growth and market share gains.
See why 14 investors see Nordson as 6% undervalued.
Result: Fair Value of $349.71 (UNDERVALUED)
Still, the Nordson story depends heavily on semiconductor demand staying firm, while any stumble on acquisition integration could quickly challenge the current valuation narrative.
Find out about the key risks to this Nordson narrative.
Another View: Nordson Through The P/E Lens
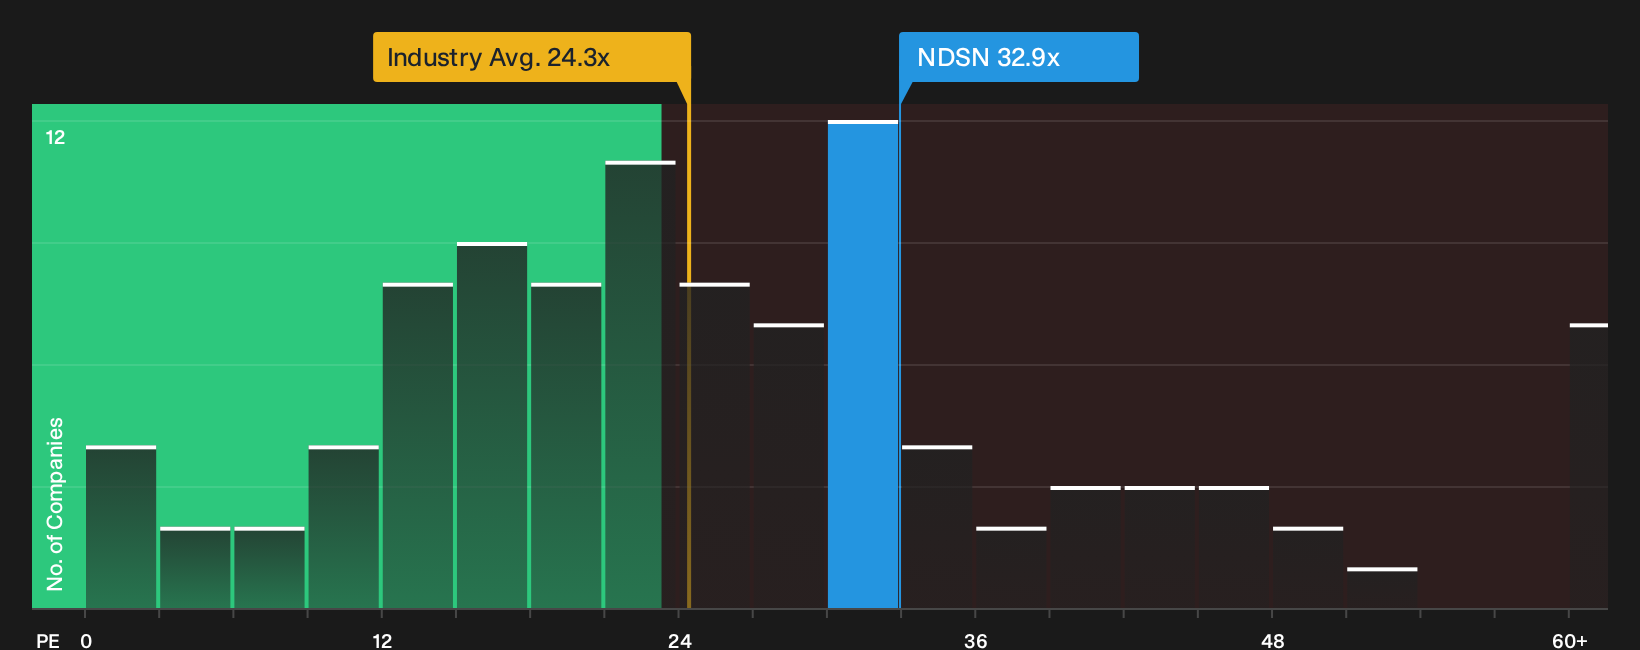
Nordson looks quite different when you focus on simple pricing. The stock trades on a P/E of 32.9x, which is higher than the US Machinery group at 25x and above its own fair ratio of 22.4x. That gap points to richer expectations and less room for disappointment. Does that premium feel justified to you?
Investors who want to see how this pricing compares with detailed earnings assumptions can review our valuation breakdown. It sets that higher P/E against cash generation and the quality of growth, which may help investors decide how comfortable they are with the current setup. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the mix of optimism and concern around Nordson's outlook? Act quickly, review the data yourself, then weigh up the 2 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Nordson?
If Nordson has you thinking harder about valuation and quality, do not stop here. Push further, compare more ideas, and let the best opportunities compete for your capital.
- Target potential mispricing by scanning companies that combine quality fundamentals with attractive pricing using our focused 29 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses with robust payouts and higher yields through the curated 8 dividend fortresses.
- Dial back risk by concentrating on resilient businesses with healthier financial profiles through our carefully filtered 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com