
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Waters (WAT) Ties Up With CellCarta, Is The Stock Already Fully Valued?
Waters investors eye CellCarta diagnostics alliance
Waters (WAT) is back in focus after CellCarta announced a partnership that links Waters instrumentation, reagents, and assay development to companion diagnostics and next generation flow cytometry programs for global drug sponsors.
Recent trading backs up that interest, with Waters sharing a 15.6% 90 day share price return and a 6.5% 30 day share price return, while total shareholder return over 1 year of 33.1% and 3 years of 63.8% points to momentum that many investors will see as building rather than fading.
Scan beyond Waters and see how other lab and diagnostics suppliers are positioned by sorting through our hand picked list of solid balance sheet and fundamentals (25 results).
After a 1 year total return of 33.1% and a recent move toward the analyst price target, the question now is whether Waters still offers an attractive risk reward or if expectations already capture the upside.
Most Popular Narrative: 2% Undervalued
On the most followed view, Waters carries a fair value estimate of $446.74 against a last close of $435.99. This points to only a modest valuation gap and puts execution front and center in the story.
The combination with BD Biosciences and Diagnostic Solutions is moving from concept to execution, as the acquired businesses have shifted from a prior year decline of roughly 10% to mid single digit growth. Waters has already reached a US$200m cost synergy run rate in nine months, which supports the case for structurally higher margins and earnings versus the pre deal base.
See why 14 investors see Waters as 2% undervalued.
Result: Fair Value of $446.74 (ABOUT RIGHT)
Still, the Waters narrative can crack if BD integration stumbles, or if weakness in China persists and drags on the acquired diagnostics revenue base.
Find out about the key risks to this Waters narrative.
Another View: Waters and the P/S Gap
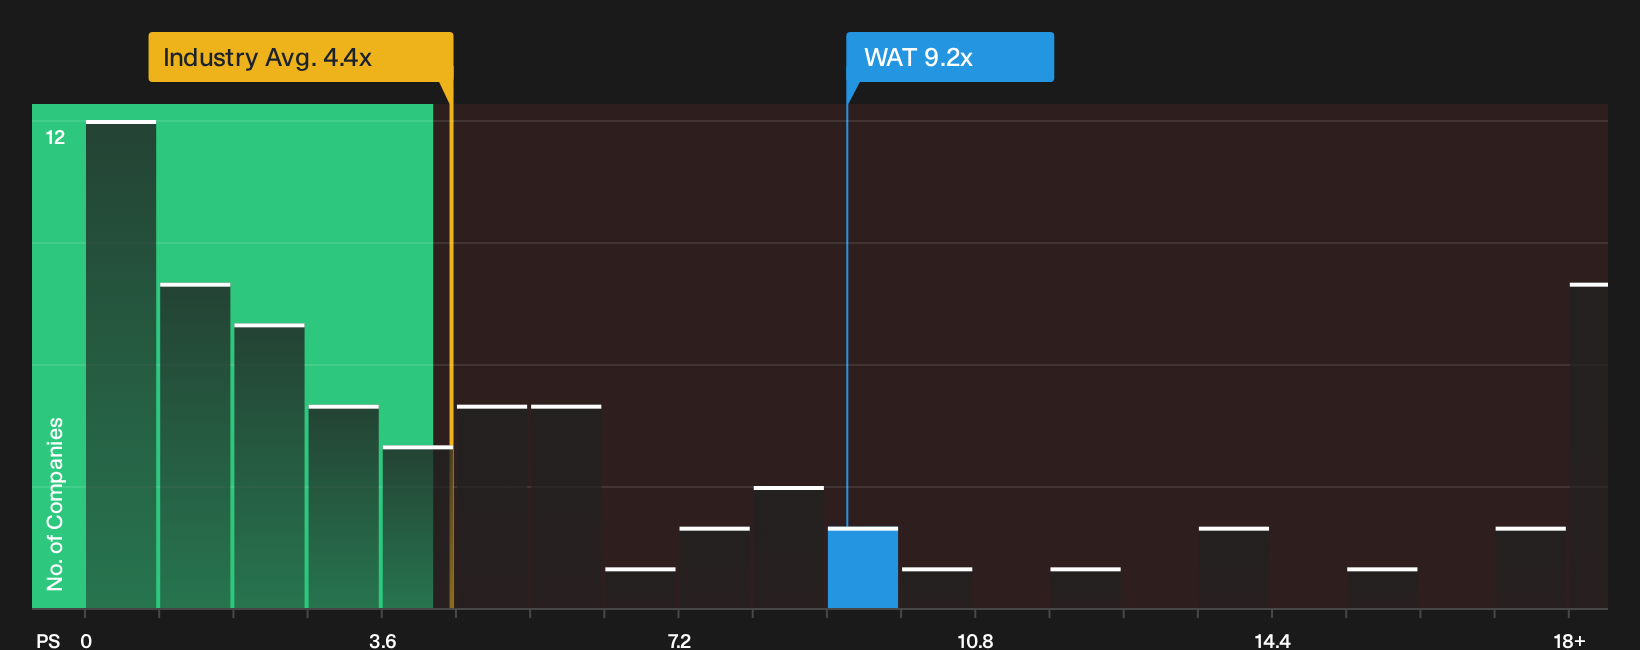
On a simple sales multiple, Waters looks rich. The stock trades on a P/S of 9.2x, compared with a fair ratio estimate of 7.9x, the US Life Sciences industry near 4.7x, and peers around 6.3x, which points to limited room for disappointment if anything goes wrong.
That kind of premium can reflect confidence in the earnings story, but it also concentrates valuation risk if integration hiccups or one off items return to the headlines. How comfortable are you paying up at this level of expected profit growth?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Waters valuation and risk profile can be energising or unnerving, so move quickly, review the numbers yourself and weigh both sides through the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Waters?
If Waters has your attention, broaden your watchlist using the Simply Wall St screener to spot fresh opportunities before they are crowded trades.
- Target potential mispricing by reviewing companies flagged in the 29 high quality undervalued stocks that pair quality fundamentals with prices that differ from fair value estimates.
- Prioritise resilience by scanning the 31 resilient stocks with low risk scores focused on businesses with steadier balance sheets and lower overall risk profiles.
- Get ahead of the crowd by studying the 20 high quality undiscovered gems where strong fundamentals have not yet attracted broad market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com