
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Coherent Stock Gains Attention As AI Demand Lifts Optical Connectivity Growth
- Coherent has recently been in focus as demand tied to AI infrastructure, optical connectivity and VCSEL-based components has supported its operations and underpinned ongoing capacity expansion efforts.
- The company’s push into integrated optical subsystems, its expansion of manufacturing for advanced photonics and its role in the growing VCSEL market highlight how AI and high-performance datacenters are shaping Coherent’s business mix.
- We will now examine how this AI driven optical connectivity demand shapes Coherent's broader investment narrative and potential risk profile.
Coherent Investment Narrative Recap
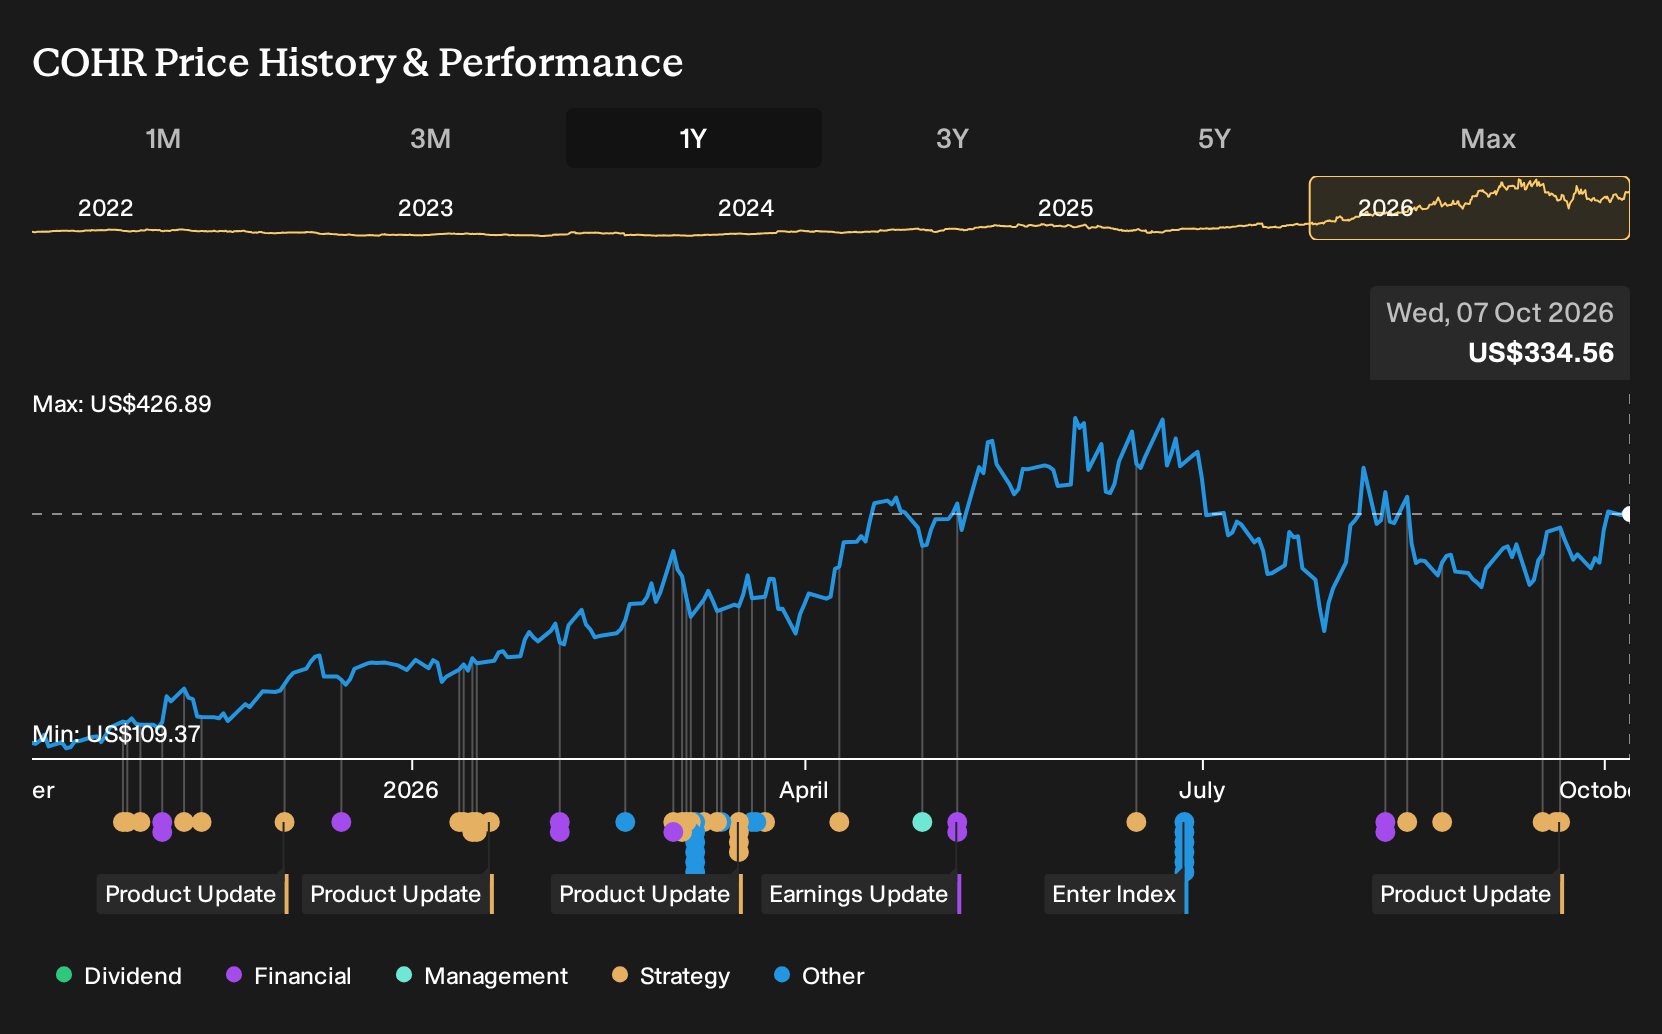
To own Coherent, you really need to believe that AI datacenter buildouts and high speed optical connectivity can keep supporting its Datacenter & Communications segment and justify heavy manufacturing investment. The recent pullback, after a period where the stock climbed roughly 190% over twelve months, does not change that core thesis. The near term swing factor is execution on new capacity and complex subsystem ramps. The biggest risk remains pricing and margin pressure if low cost competitors and large customers push harder on costs right as Coherent is spending heavily.
Recent volatility in Coherent during a weak broader session, with the stock among the S&P 500’s larger decliners while Treasury yields stayed elevated, mostly reflects risk appetite and rate sensitivity rather than a clear shift in fundamentals. The more relevant development for an AI centric thesis is the focus on integrated subsystems like PhotonLink that aim to move the group up the value stack. That effort could help offset potential commoditization pressure in stand alone optical components, although it raises execution and ramp risks if customer adoption is slower than expected.
The most interesting recent data point for the story is Coherent’s positioning in VCSELs as demand in AI data centers and automotive sensing grows. The global VCSEL market is projected to reach about US$2.0b by 2032, with an 8.8% compound growth rate, and Coherent is listed alongside peers such as Lumentum, ams OSRAM, TRUMPF and Broadcom. For you as an investor, that scale of addressable market helps frame why Coherent is committing significant capital to VCSEL capacity and related photonics platforms, on top of its indium phosphide investments in Texas.
At the same time, that same VCSEL backdrop underlines key risks. Customer concentration around large consumer electronics and hyperscale buyers can translate into uneven order patterns and sharp shifts in utilization if a program is delayed. Competition from Asian producers in optical components also threatens pricing over time. The share price already embeds strong expectations, reflected in a P/E of 85.1x against a US Electronic industry average of 29.9x and a peer average P/E of 44.5x. This leaves less room for operational missteps on these AI and VCSEL driven catalysts.
Coherent's narrative projects US$19.2b revenue and US$3.5b earnings by 2029. This assumes 39.2% yearly revenue growth and an earnings increase of about US$2.7b from US$769.9m today.
Uncover why Coherent's fair value indicates a 24% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Coherent focuses heavily on overinvestment risk. AI datacenter buildouts are front and center today. The most cautious analysts worry that newly doubled capacity could coincide with softer hyperscaler capex later. Their pre news models still penciled in about US$18.5b revenue and US$3.6b earnings by 2029, yet with a lower 27.5x P/E. This highlights how sharply opinions can differ and why it can be useful to explore several viewpoints before deciding how this latest volatility might reshape the story.
Explore 5 other Coherent fair value estimates, including one that suggests as much as 67% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Coherent research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Coherent. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coherent's overall financial health at a glance.
Looking For More Ideas Beyond Coherent?
If the Coherent story has sharpened your interest in AI, photonics or just concentrated growth themes, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles.
- For investors who want potential upside without paying up for every dollar of earnings, scan through our 29 high quality undervalued stocks that combine quality fundamentals with discounted valuations.
- If sleep at night resilience matters more than rapid swings, start with a 31 resilient stocks with low risk scores that screens for stronger balance sheets and lower overall risk scores.
- Those hunting for income first and price gains second can review a 8 dividend fortresses that focus on higher yielding payouts backed by underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com