
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Forge Trust Sale Could Be A Big Test For Charles Schwab Stock (SCHW)
- Charles Schwab has agreed to sell Forge Trust Co. and its parent Forge Services Inc. to Alto, while rolling out Charley, a new generative AI assistant that supports client service, task completion, and access to account and market information.
- The sale of Forge Trust simplifies Schwab's private market operations at the same time as Charley and other AI tools aim to keep client engagement high without relying solely on headcount and traditional service channels.
- We will now assess how Charles Schwab's Forge Trust exit and AI driven Charley rollout could shape the broader investment narrative.
Charles Schwab Investment Narrative Recap
To own Charles Schwab, you need to believe its scale in brokerage, advice, and banking can keep translating client activity into earnings, even as low cost rivals and fee pressure bite. The most important near term swing factor is whether revenue growth can stay ahead of rising technology and AI spending so that operating leverage holds up.
The Forge Trust sale and Charley rollout do not radically change that equation. They mostly tidy the private markets footprint and tweak the expense mix. The bigger risk still sits in costs running hotter than planned, or any client protection failure that dents trust and slows new assets and lending penetration.
Charley is the announcement that really matters for this story. Daily trading activity, options usage among younger investors, and demand for digital tools already play a significant role in Schwab’s revenue mix. A generative AI assistant that helps with tasks, portfolio insights, and market data fits directly into that push to keep clients transacting and consolidating assets on the platform.
The key question is execution. Charley and the existing AI portfolio insights tools need to improve service quality and keep cost per account in check, rather than simply adding complexity. If Schwab can broaden Charley’s capabilities while controlling fraud, legal, and regulatory risks, the AI build out could support both revenue durability and margin resilience.
Charles Schwab's analyst narrative points to revenues of US$34.9b and earnings of US$14.2b by 2029. This lines up with a projected 10.2% yearly revenue growth rate and implies an earnings increase of about US$4.5b from US$9.7b today.
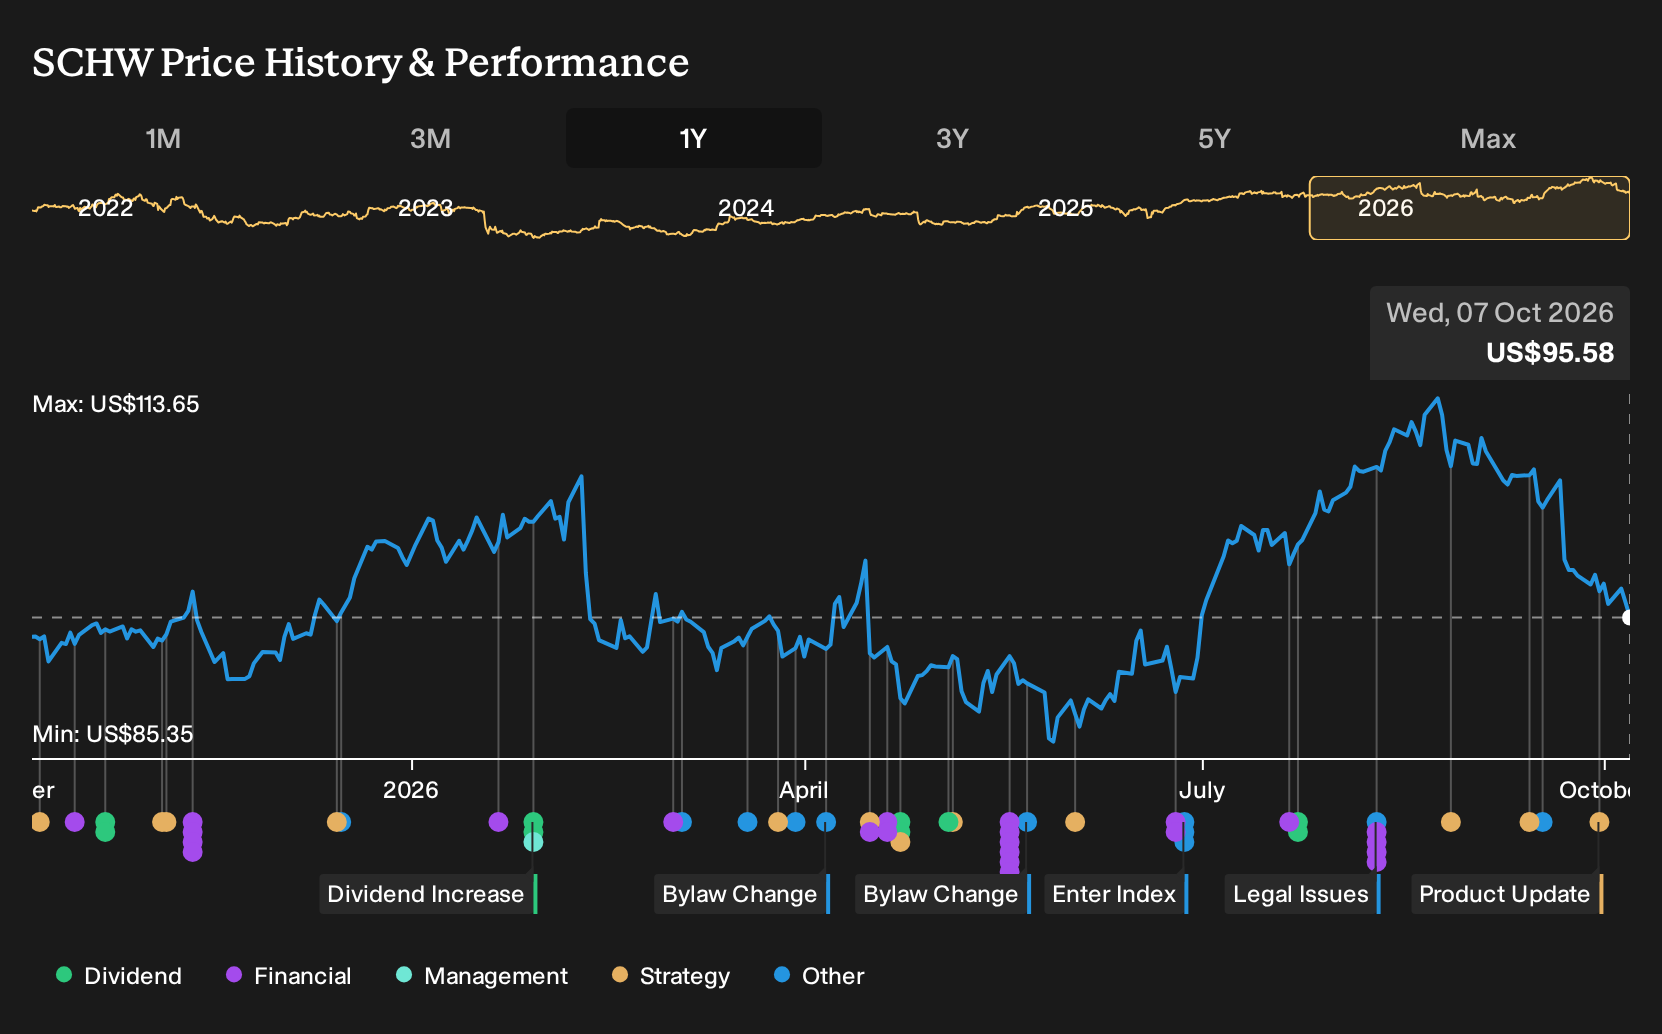
Discover why Charles Schwab's fair value indicates a 31% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
Some of the most optimistic analysts frame Charley as a possible accelerant for Charles Schwab, not just a cost tool. Before this launch, the bullish narrative already assumed revenue could reach about US$37.3b and earnings about US$14.7b by 2029. You now get to decide whether this fresh AI push justifies revisiting those stronger views.
Explore 3 other Charles Schwab fair value estimates, including one that suggests as much as 32% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis when making decisions.
- A great starting point for your Charles Schwab research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Charles Schwab. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Charles Schwab's overall financial health at a glance.
Looking for more investment ideas beyond Charles Schwab?
Once you have a handle on Charles Schwab, it can be useful to compare its profile with other companies that share similar qualities or offer something different for your portfolio. The Simply Wall St Screener lets you filter by balance sheet strength, valuation, income focus, and more so you can quickly narrow a long list of tickers down to a few worth deeper research.
- If capital preservation is a priority, start with companies that score well on resilience and stability through our 31 resilient stocks with low risk scores.
- For investors hunting for strong fundamentals that the market may be overlooking, scan the 20 high quality undiscovered gems and see which businesses merit a closer look.
- If you care about solid finances backing every dollar you invest, filter for firms with robust balance sheets and consistent track records using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com