
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
TORM (CPSE:TRMD A) Following Its Share Sale Looks About Right
What the latest TORM equity moves mean for shareholders
TORM (CPSE:TRMD A) is back in focus after a follow on equity offering tied to a secondary sale of 6,329,874 Class A shares, raising about US$253.5 million for an existing shareholder.
The deal, priced at US$40.05 per share with a US$0.205 discount, did not involve TORM issuing new stock or receiving cash. That keeps the shipping group’s balance sheet and cash position unchanged.
Recent trading shows strong momentum in TORM, with a 1-day share price return of 1.99% and a 30-day share price return of 18.70%, building on a 112.94% year to date share price return and a 5-year total shareholder return of more than 10x. The secondary offering and recent RSU-related capital increase are reshaping the shareholder base without changing the company’s cash position.
Capture this kind of momentum shift in other shipping and energy stocks by screening for 182 high quality undervalued stocks that may be setting up for their next move.TORM has just absorbed a large secondary sale without touching its own cash or issuing fresh shares. Is this a window to step in now, or a moment to sit tight and wait for a cooler entry?
Most Popular Narrative: 1% Undervalued
The most followed narrative puts TORM’s fair value at DKK269.31, only slightly above the last close of DKK266.60. This frames today’s equity shuffle as a pricing fine tune rather than a deep discount.
Disciplined capital allocation, including accretive vessel acquisitions, lease repurchases and a conservative balance sheet with long debt maturities, provides flexibility to capture potential future rate upside, which should support dividends and long term earnings potential.
See why 8 investors see TORM as 1% undervalued.
Result: Fair Value of DKK269.31 (ABOUT RIGHT)
Still, the TORM narrative can break if geopolitical disruptions ease and trade routes shorten, or if new tanker supply outpaces demand and pressures freight economics.
Find out about the key risks to this TORM narrative.
Another View: What TORM’s Cash Flows Say
On earnings multiples, TORM looks inexpensive, with a P/E of 6.6x versus 13.7x for the European Oil and Gas group and 17.8x across peers. Our DCF model tells a different story. It points to a future cash flow value of DKK206, which sits well below the current DKK266.60 share price. Which lens do you trust more when growth forecasts are this cautious?
Look into how the SWS DCF model arrives at its fair value.
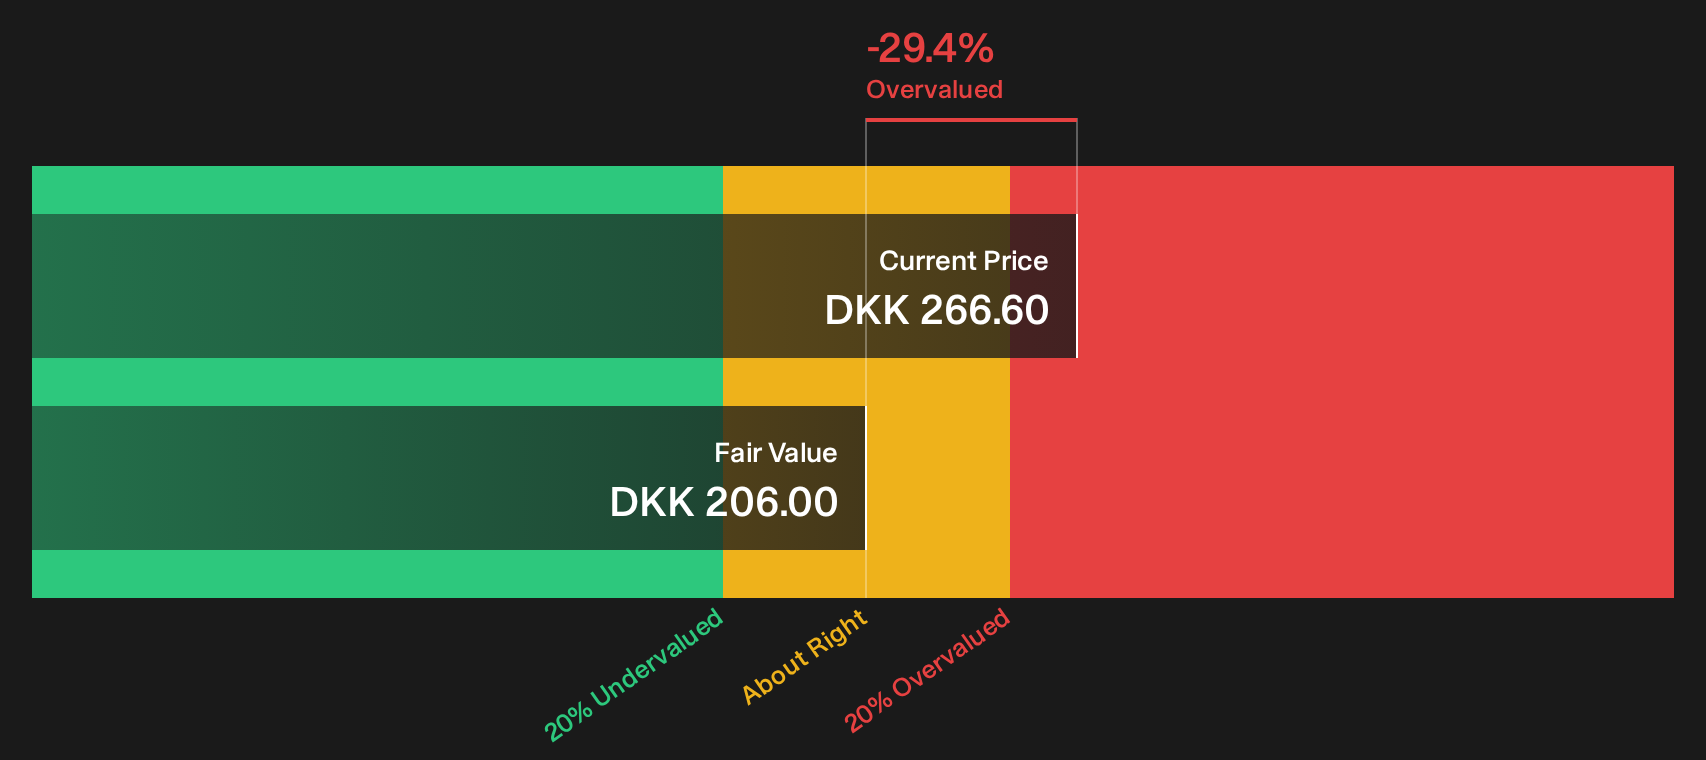
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TORM for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 182 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around TORM is finely balanced, with both risks and rewards on the table. Move quickly to review the data and shape your own stance with 2 key rewards and 4 important warning signs.
Looking for more ideas beyond TORM?
If you only stop at TORM, you risk missing other opportunities that fit your style. Put a short list together now and keep your options open.
- Target higher upside potential by scanning for 121 elite penny stocks with strong financials that already show solid financial underpinnings instead of pure story stocks.
- Prioritise resilience by filtering for a list of solid balance sheet and fundamentals (206 results) so you focus on businesses with the financial strength to handle tougher conditions.
- Stay ahead of the crowd by reviewing a 619 high quality undiscovered gems before these quieter opportunities attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com