
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Assurant (AIZ) Gains Embedded Insurance Ground As Valuation Questions Build
Assurant (AIZ) is drawing fresh attention after its Connected Living unit expanded embedded insurance distribution partnerships, and the second quarter of 2026 showed higher adjusted EBITDA and EPS tied to these recurring, service-based protection offerings.
That earnings backdrop comes after a mixed stretch for Assurant’s share price. The stock is down 6.65% over 30 days and 4.47% over 90 days, even though the year to date share price return is 12.20% and the 1 year total shareholder return is 23.42%. Longer term holders have seen total shareholder returns of 90.23% over 3 years and 81.07% over 5 years, suggesting momentum has cooled recently even as the longer run record remains strong.
Scan other insurance and protection specialists showing similar recurring earnings traits by screening for 31 resilient stocks with low risk scores alongside Assurant’s embedded insurance story.
Assurant’s stock has cooled in recent months even as analysts and some intrinsic value models sit well above the current US$266.73 share price. Where does fair value really land across that spread?
Most Popular Narrative: 19% Undervalued
Assurant’s most followed valuation story anchors on a fair value of $330 against the last close at $266.73, which frames today’s pullback as a discount rather than a peak. That view leans heavily on how deeply embedded its device and housing programs have become inside large partners.
Assurant is capitalizing on the proliferation of connected devices and increasing device protection needs, supported by over 4,000,000 additional protected devices over the last year and more than 7,000,000 devices serviced in a single recent quarter. This can continue to feed fee income growth and support adjusted EBITDA.
See why 8 investors see Assurant as 19% undervalued.
Result: Fair Value of $330 (UNDERVALUED)
Still, parts of the Assurant story could break if lender placed insurance faces tougher regulatory pressure, or if the recent drop in institutional ownership persists.
Find out about the key risks to this Assurant narrative.
Another View On Assurant’s Valuation
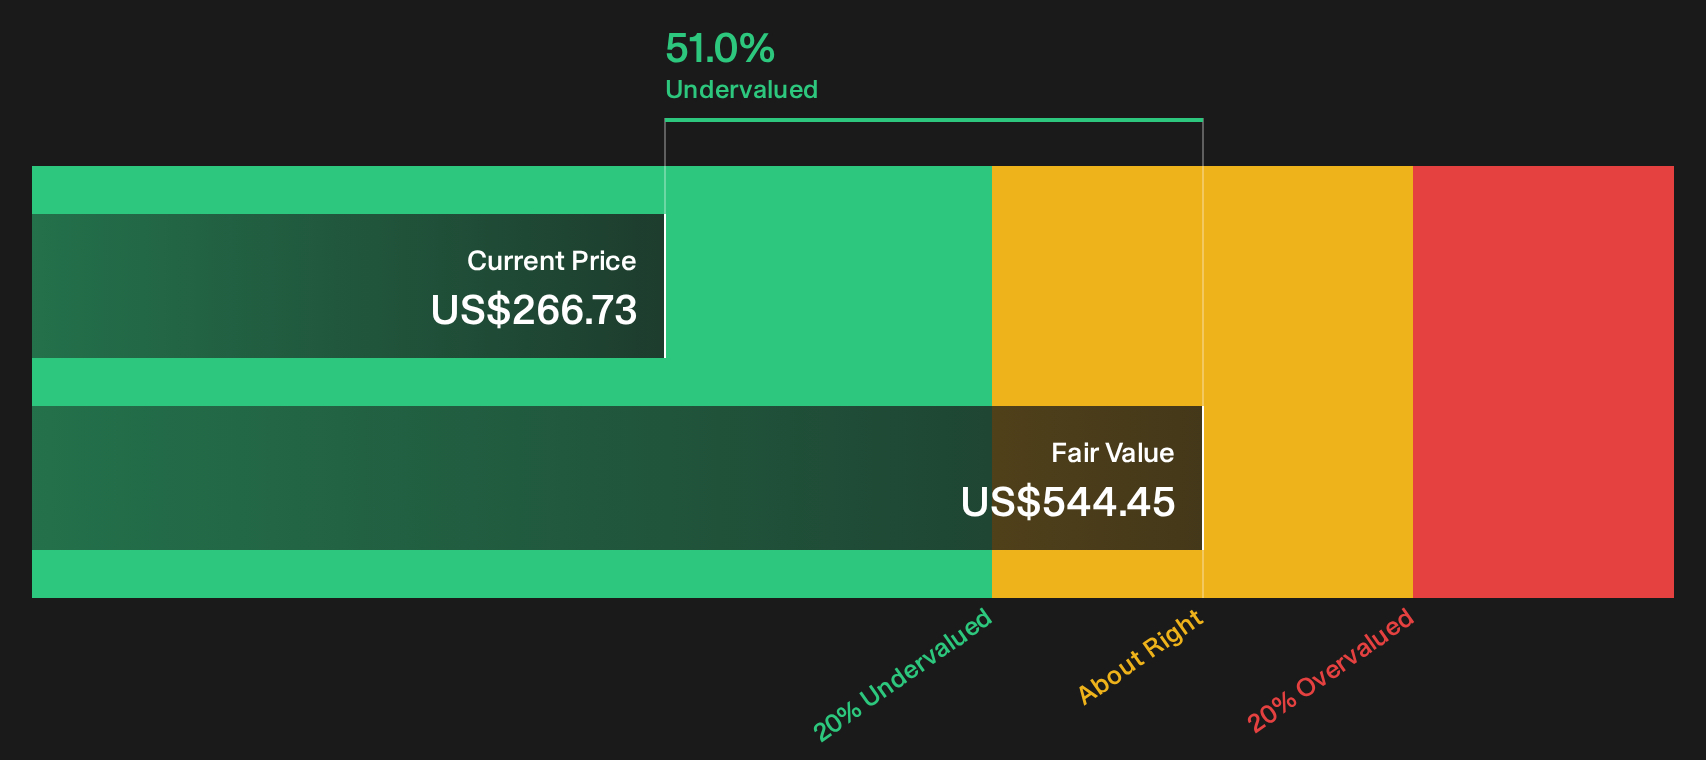
There is a very different message coming from the SWS DCF model. On that view, Assurant’s future cash flows point to a fair value of about $544.45 per share, compared with the current $266.73 price, which flags the stock as heavily undervalued. If earnings are only growing in the mid single digits, how comfortable are you leaning on such a wide DCF gap?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals or early opportunity, either way the gap between Assurant’s different fair value stories is wide enough that it deserves your own closer look. To weigh both the upside arguments and the issues investors are worried about, review the 4 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Assurant?
If Assurant’s valuation gap has you thinking bigger, consider broadening your watchlist with other opportunities before the market moves without you.
- Target more potential upside candidates by scanning companies that appear mispriced on fundamentals through the 29 high quality undervalued stocks.
- Strengthen the defensive side of your holdings by reviewing businesses with stronger finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for earlier stage potential by checking out the 12 elite penny stocks with strong financials before attention and liquidity crowd in.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com