
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Wise Group (WSE) Launches Travel eSIM And QR Payments, But Is The Valuation Already Priced In?
Wise Group (WSE) just rolled out customizable eSIM data plans bundled with cross border QR payments, aiming to remove the usual panic around landing in a new country without data or local payment options.
Wise Group’s recent product push lands after a mixed run in the market, with the share price at $11.81, a 7-day share price return of 3.69%, but a 30-day share price return that declined 7.59%. The 1-year total shareholder return fell 13.8%, even as the 3-year total shareholder return gained 34.97%, suggesting short term momentum has softened compared with a stronger multi year record.
Scan the travel fintech space beyond Wise Group by reviewing a curated set of 20 high quality undiscovered gems that are quietly building cross border payments and digital finance tools for global users.
Bulls point to Wise Group’s eSIM and QR rollout as a fresh growth lever, while bears see a stock with softened momentum. Which side does the current valuation actually lean toward?
Most Popular Narrative: 30% Undervalued
Wise Group’s most followed valuation story points to a fair value of $16.94 against the last close of $11.81. The gap between price and narrative estimate is wide and may be worth testing against your own expectations.
Growing use of Wise Accounts, Wise cards and Wise Assets by 19 million active customers, together with a larger share of non cross border revenue, increases the scope for broader fee based income and can support net revenue and earnings.
See why 3 investors see Wise Group as 30% undervalued.
Result: Fair Value of $16.94 (UNDERVALUED)
Still, if Wise Group’s deliberate fee cuts outpace efficiency gains, or regulators restrict interest income on customer balances, that 30% undervaluation story can quickly unravel.
Find out about the key risks to this Wise Group narrative.
Another View On Wise Group’s Valuation
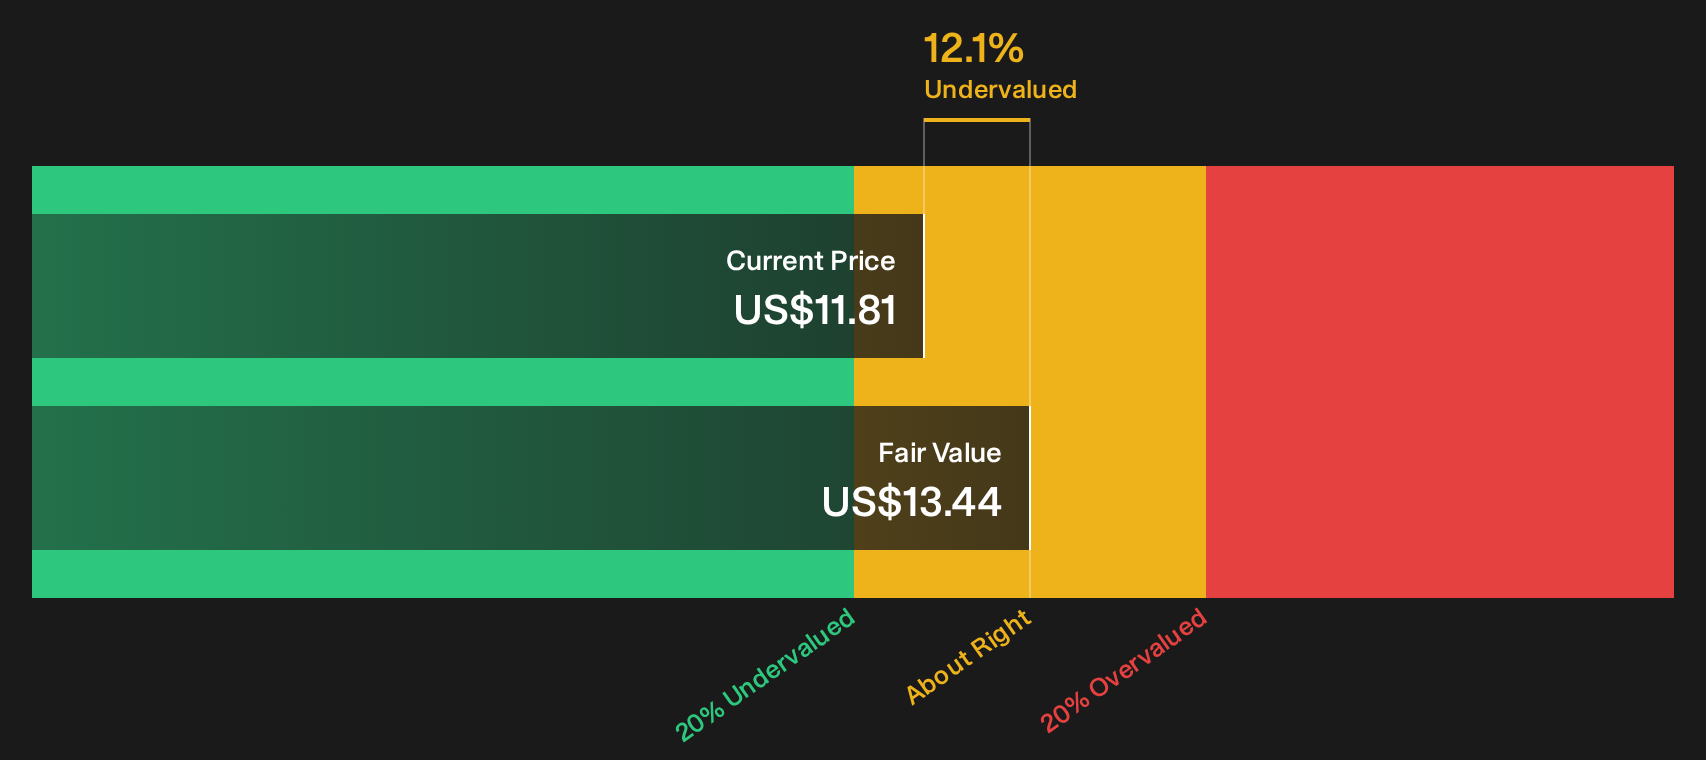
Wise Group screens as good value on one measure, with the share price trading 12.1% below an internal fair value estimate of $13.44 from our DCF model. Yet the same stock looks expensive on a P/E of 24.3x versus a fair ratio of 14.9x. This raises a simple question: which signal do you trust more when real money is on the line?
For readers who want to see how this cash flow based approach is built step by step, Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the Wise Group story so far seems divided between opportunity and hesitation, consider acting promptly, reviewing the numbers yourself, and closely examining the 3 key rewards
Searching Beyond Wise Group For Your Next Move?
Do not stop your research with Wise Group alone. Broaden your watchlist and give yourself better odds of spotting opportunities before the crowd moves.
- Target resilient potential upside by scanning a 29 high quality undervalued stocks that filters for strong fundamentals paired with prices that sit below internal estimates of worth.
- Prioritize capital protection first and hunt through a 31 resilient stocks with low risk scores curated for businesses with sturdier balance sheets and lower assessed risk profiles.
- Spot under the radar potential by reviewing a 12 elite penny stocks with strong financials that highlights cheaper shares with stronger financial characteristics than the typical speculative trade.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com