
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
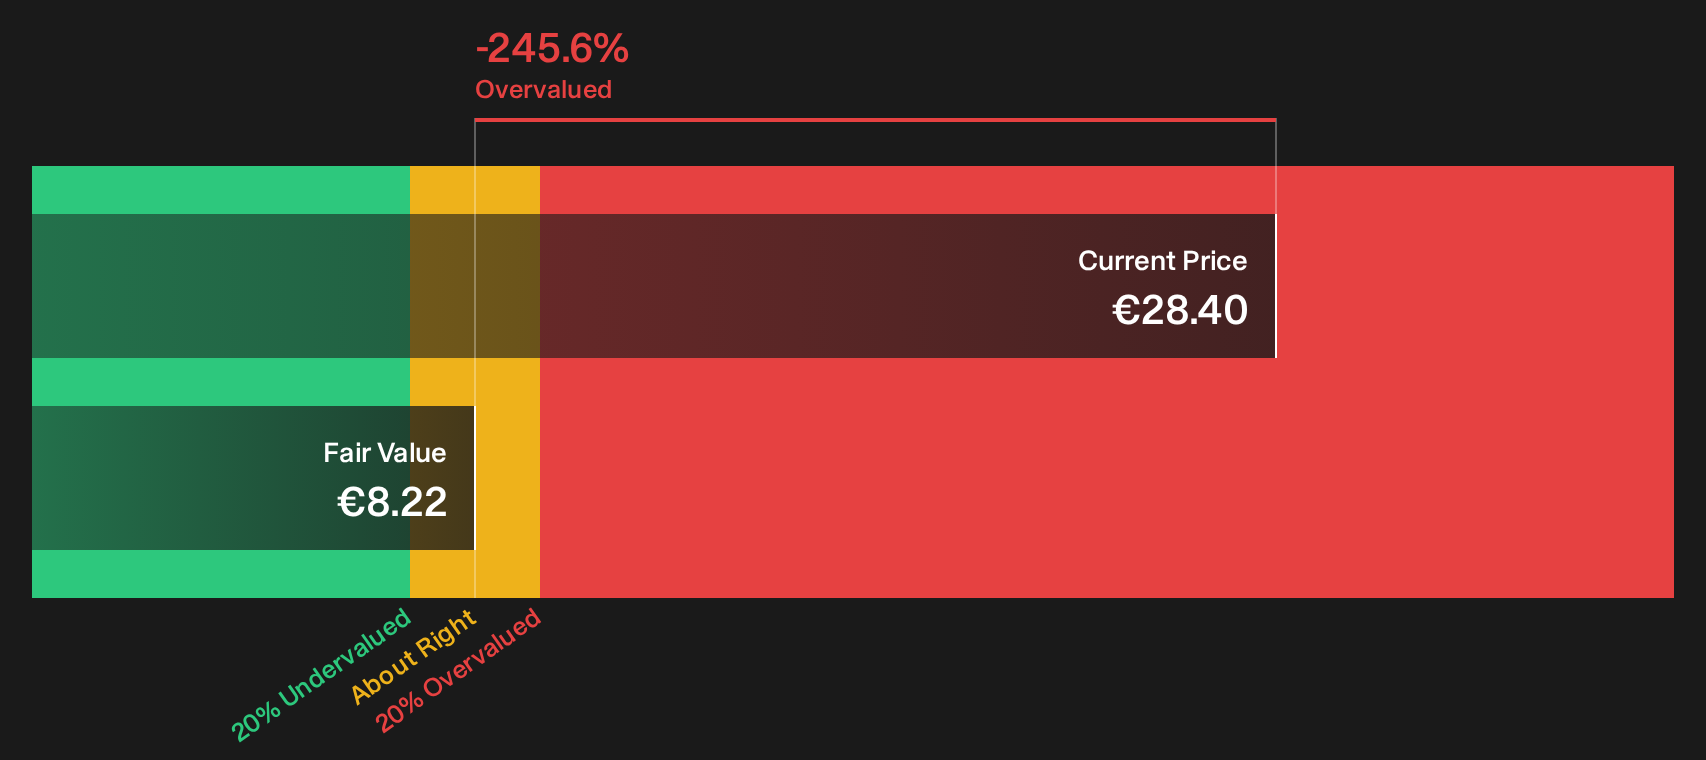
Biotest (XTRA:BIO3) Could Be 71% Above Fair Value At €28.40
Biotest (XTRA:BIO3) shares closed at €28.40 on the most recent trading day, a move that drew attention after a period of flat performance over the past month.
For context, Biotest’s share price return is up 4.41% year to date. The 1 year total shareholder return of 4.94% contrasts with a 3 year total shareholder return that has declined 18.97%, suggesting recent momentum has firmed after a weaker spell.
Scan beyond Biotest and line up other healthcare players that match this mix of modest recent gains and past drawdowns with the hand picked 225 resilient stocks with low risk scores list.
Biotest has inched higher this year but still carries a mixed return record and a recent net loss. Does that balance of rebound and risk still favour buyers at today’s €28.40 once the valuation is unpacked?
Preferred Price-to-Sales of 1.8x: Is it justified?
On valuation, Biotest screens as inexpensive on one metric while looking stretched on another. The P/S multiple stands at 1.8x, yet the SWS DCF model fair value estimate sits at €8.22 against the current €28.40 share price.
The price to sales ratio compares the market value of the equity to annual revenue. For a pharmaceutical and biotech group like Biotest, where earnings are currently negative and profit based metrics are harder to use, this sales based gauge often becomes the quick shorthand for how much investors are paying for each euro of turnover.
On that shorthand, the stock looks cheap. A P/S of 1.8x is described as good value against both the broader European biotechs industry average of 8.9x and a peer group average of 23.8x. The discounts are wide and suggest the market is pricing Biotest more cautiously than many similar healthcare listings despite its €635.2m in revenue, recent loss of €24.5m and improving loss trend over five years.
The DCF picture is very different. The SWS DCF model fair value of €8.22 implies the current €28.40 quote is trading well above this estimate and points to a rich price once future cash flow assumptions are applied instead of simple sales multiples. That tension between a low P/S tag and a higher price than the DCF output highlights how much hinges on Biotest’s ability to move from loss making to consistent profitability over time.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Sales of 1.8x (OVERVALUED)
Still, Biotest faces the risk that continued net losses and its role as a subsidiary of Grifols Biotest Holdings could limit upside if expectations shift.
Find out about the key risks to this Biotest narrative.
Another View on Biotest’s Value
The sales based lens paints Biotest as cheap, yet the SWS DCF model points the other way. That approach values the shares at €8.22, well below the current €28.40 level, which implies the stock screens as expensive once future cash flows are front and center.
For anyone weighing which signal to trust more, the real question is how comfortable you are with the assumptions that sit inside that cash flow forecast and how much room for error you want at this price.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Biotest for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 182 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
That mix of cautious signals around Biotest can feel unclear, so move quickly from reading to testing the numbers yourself and stress test the downside case. You can start by sizing up the 2 important warning signs.
Looking for more Biotest sized investment ideas?
If Biotest has you weighing risk and reward, do not stop here. Broaden your watchlist with focused sets of companies that match clear financial traits.
- Target quality at a discount by checking companies that combine strong fundamentals with appealing valuations through the 182 high quality undervalued stocks.
- Strengthen your downside protection by scanning the list of solid balance sheet and fundamentals (206 results) and focus on businesses with more robust financial footing.
- Spot potential early movers by reviewing the 121 elite penny stocks with strong financials where smaller companies pair lower share prices with meaningful financial filters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com