
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Accor (ENXTPA:AC), What Is Behind The Fresh Attention?
Leadership changes and what they might mean for Accor
Accor (ENXTPA:AC) is back in focus after appointing Vipin Khattar as Chief Commercial Officer for South Asia and Kara Randall as Chief Development Officer for luxury brands in North America.
These moves concentrate experienced leadership on two regions that matter for Accor's Premium, Midscale and Economy segments, as well as its Luxury & Lifestyle segments. This gives investors fresh context for thinking about the group’s global hotel and services platform.
Accor’s €44.79 share price sits below where it traded earlier in the year, with the 30 day share price return down 4.7% and the 90 day share price return down 8.6%, even though the 1 year total shareholder return is 12.2% and the 5 year total shareholder return is 61.7%. This suggests that recent momentum has cooled, while longer term holders have still seen meaningful gains.
Spot fresh leadership shifts at Accor, then scan a curated set of hospitality and travel businesses that may be priced for a rerating with the 183 high quality undervalued stocks.Short term sentiment around Accor has cooled even as leadership leans into new growth regions. The question now is whether today’s valuation still pays investors enough for taking that ride.
Most Popular Narrative: 19% Undervalued
Accor’s most followed narrative pegs fair value at €55.29, above the recent €44.79 close, which frames today’s pullback as a valuation gap rather than a settled verdict on the business.
Accor's rapidly expanding pipeline, driven by strong signings in the U.S., Asia, and growth in Luxury & Lifestyle brands, positions the company to benefit from increased global travel demand, urbanization, and the growing global middle class, which should support sustained revenue and net unit growth acceleration in coming years.
See why 8 investors see Accor as 19% undervalued.
Result: Fair Value of €55.29 (UNDERVALUED)
Still, the Accor story can change quickly if foreign exchange swings, or a slower patch in core European markets, start to bite into reported earnings.
Find out about the key risks to this Accor narrative.
Another view on Accor’s valuation
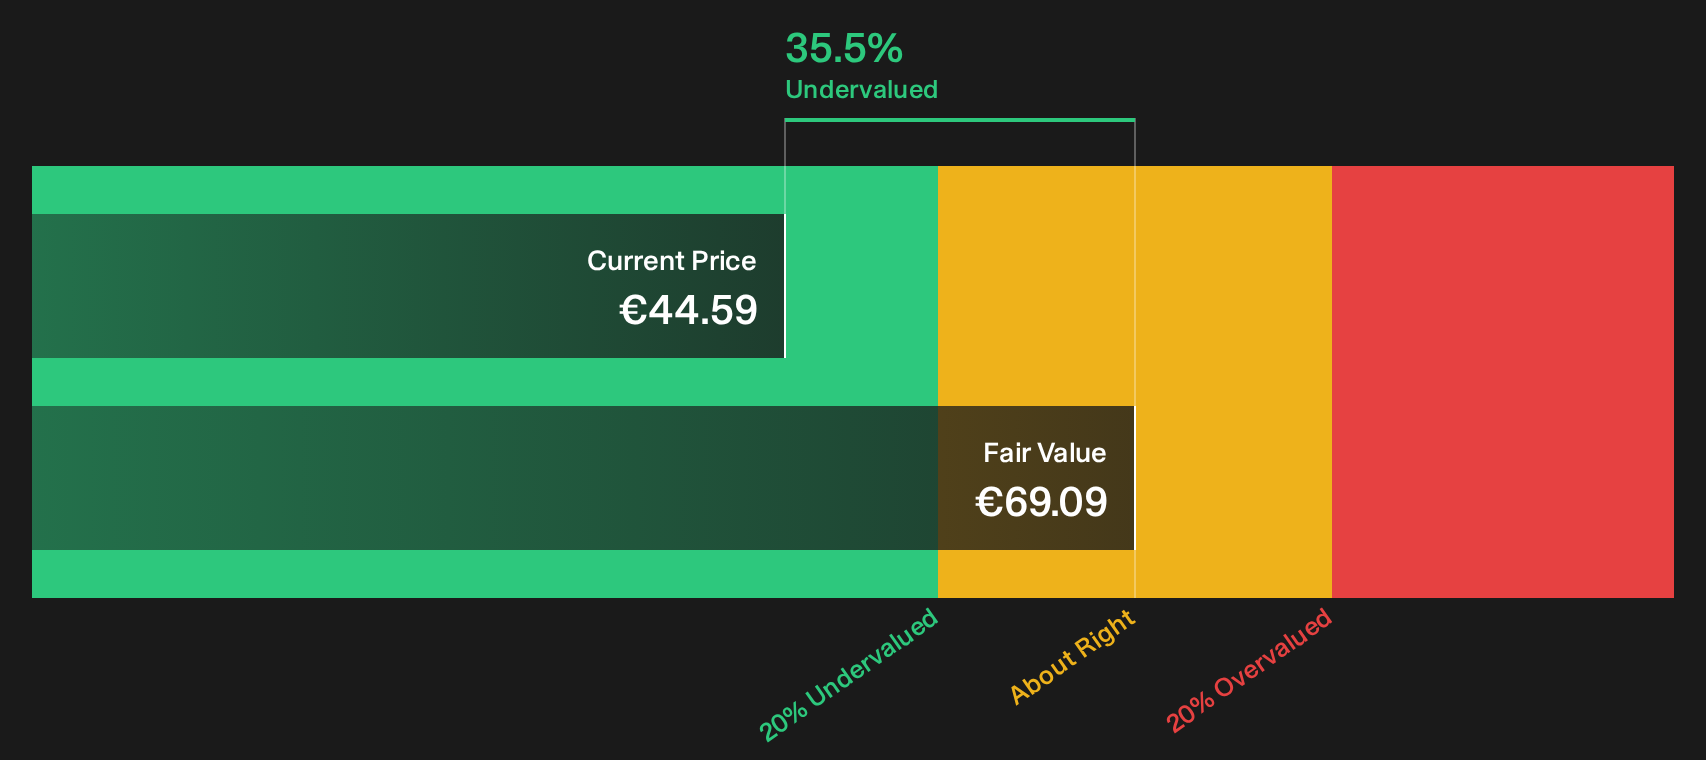
Accor screens as 35.5% below the Simply Wall St fair value estimate of future cash flows, which points to undervaluation on the SWS DCF model. That sits awkwardly beside a rich 45.1x P/E, well above both peers and the sector. Which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this mix of leadership change and valuation tension around Accor feels finely balanced, treat it as your cue to move fast. Stress test the full picture for yourself with 3 key rewards and 4 important warning signs
Looking for more investment ideas beyond Accor?
Do not stop your work with Accor. Use this moment to widen your watchlist and pressure test where your next euro of risk really belongs.
- Target resilient payouts by reviewing companies that make the cut in our income focused screen through the 223 dividend fortresses.
- Hunt for quality at a discount by checking the current opportunities flagged in the 183 high quality undervalued stocks.
- Prioritise capital protection first by scanning companies highlighted in the 225 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com