
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Arista Networks (ANET) Could Be 11% Undervalued As It Expands Into AI Racks
Arista Networks’ AI Rack Announcement
Arista Networks (ANET) has put its open Ethernet rack-scale portfolio for AI workloads at center stage, partnering with AMD, Arm, Broadcom, Meta, Microsoft, Qualcomm, and others to target dense accelerator deployments.
This launch introduces liquid-cooled, Ethernet-based racks that support up to 144 accelerators per rack and extend to larger clusters through cross-rack topologies. For investors watching AI infrastructure spending, the announcement refines the discussion around how Arista Networks might participate in data center buildouts that favor open standards over proprietary systems.
For context, Arista Networks’ share price has gained 61.55% year to date, its 90-day share price return of 16.86% points to building momentum, and the 5-year total shareholder return of about 8x shows how long term holders have been rewarded.
Spot emerging peers riding the same AI data center buildout as Arista Networks by scanning our hand-picked 91 AI infrastructure stocks.After a 62% year to date climb and a roughly 12% gap to the US$242 analyst target, Arista Networks now sits where enthusiasm and caution collide. Is the market discount a warning signal or an opening?
Most Popular Narrative: 10.5% Undervalued
Arista Networks’ most followed valuation narrative points to a fair value of about $241.04, above the last close of $215.83, which frames the current price as a discount that hinges on AI networking and campus execution.
The renewed investment cycle in cloud and AI infrastructure now includes Arista Networks’ higher 2026 revenue outlook of about US$12.6b and specific goals for at least US$3.5b of AI fabrics revenue. Together with a maintained 62% to 64% gross margin range and a higher 48% to 49% operating margin target, this could support stronger earnings power.
See why 311 investors see Arista Networks as 10% undervalued.
Result: Fair Value of $241.04 (UNDERVALUED)
Still, the Arista Networks story can break if hyperscale clients slow AI data center buildouts or if new AI focused chip commitments outstrip actual demand.
Find out about the key risks to this Arista Networks narrative.
Another View on Arista Networks’ Valuation
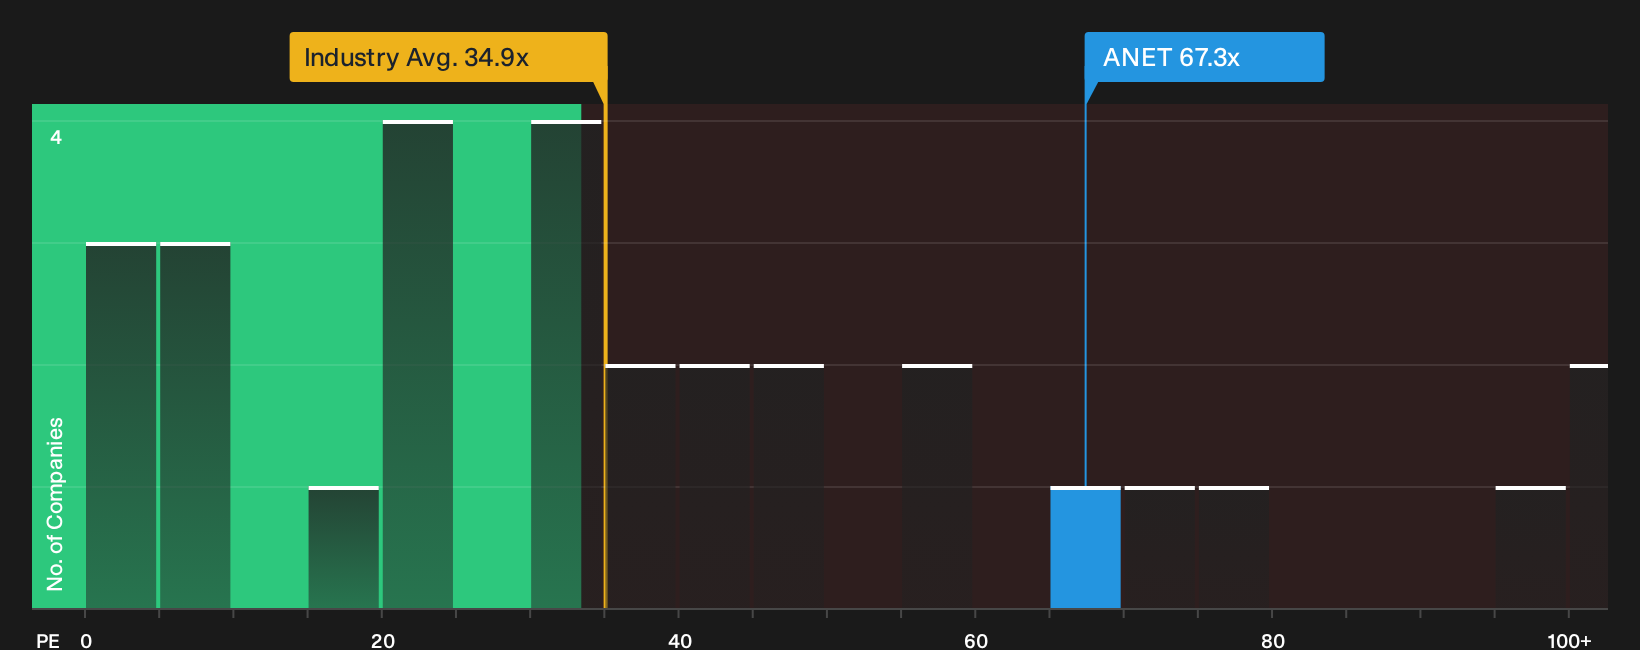
The earlier fair value narrative leans on long term earnings forecasts. A simpler check looks at today’s P/E. Arista Networks trades at 67.3x earnings while the fair ratio is 41.4x, peers average 51.6x, and the US Communications industry sits near 34.9x. That premium points to valuation risk if expectations cool rather than clear upside if growth assumptions hold.
For a closer look at how that premium could compress or persist over time, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Arista Networks’ valuation and business momentum can leave you torn, so move fast, review the underlying data, and weigh both the 2 key rewards and 1 important warning sign.
Looking for more Arista Networks sized ideas?
If you stop with Arista Networks, you risk missing other opportunities that fit your style, risk tolerance, and income needs across sectors and market caps.
- Target bold upside potential by scanning the 12 elite penny stocks with strong financials that already pair tiny market caps with stronger financial profiles than many expect.
- Zero in on price discipline and quality by reviewing a curated 29 high quality undervalued stocks that filters for robust cash flows and healthier balance sheets.
- Build a steadier income stream by assessing our 8 dividend fortresses that focuses on higher yields backed by more resilient businesses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com