
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is PICC Property And Casualty (SEHK:2328) Undervalued Following Its Interim Dividend And Chair Appointment?
PICC Property and Casualty (SEHK:2328) just received shareholder approval for an interim dividend of RMB 0.34 per share, and shareholders also backed Mr. Tan Jiong as incoming Chairperson, subject to regulatory clearance.
Recent trading hints at mixed sentiment around PICC Property and Casualty. The 1 day share price return of 2.51% to HK$15.94 comes after the interim dividend approval and leadership change, while the 30 day share price return is down 5.68% and the 1 year total shareholder return is down 6.56%, even though the 5 year total shareholder return of 193.46% reflects strong longer term performance.
Scan how PICC Property and Casualty compares with other insurers returning cash to shareholders by reviewing our hand picked list of 223 dividend fortresses in the current market.
PICC Property and Casualty has just rewarded holders with fresh cash and a leadership reset, yet the share price is still lagging its multi year gains. Is most of the upside already cashed in, or does value remain on the table?
Most Popular Narrative: 18% Undervalued
PICC Property and Casualty’s most followed narrative pegs fair value at HK$19.54, compared with the last close of HK$15.94. This points to a substantial valuation gap that investors may wish to test against the underlying business drivers.
The company plans to implement a first-class strategy by focusing on outstanding functions, efficient operations, and distinct core businesses. This strategy is expected to bolster its revenue growth, improve net margins, and enhance competitive positioning.
See why 4 investors see PICC Property and Casualty as 18% undervalued.
Result: Fair Value of HK$19.54 (UNDERVALUED)
Still, the narrative around PICC Property and Casualty can be shaken if catastrophe claims stay elevated or if heavier tech spending continues to pressure profitability.
Find out about the key risks to this PICC Property and Casualty narrative.
Another View on PICC Property and Casualty’s Valuation
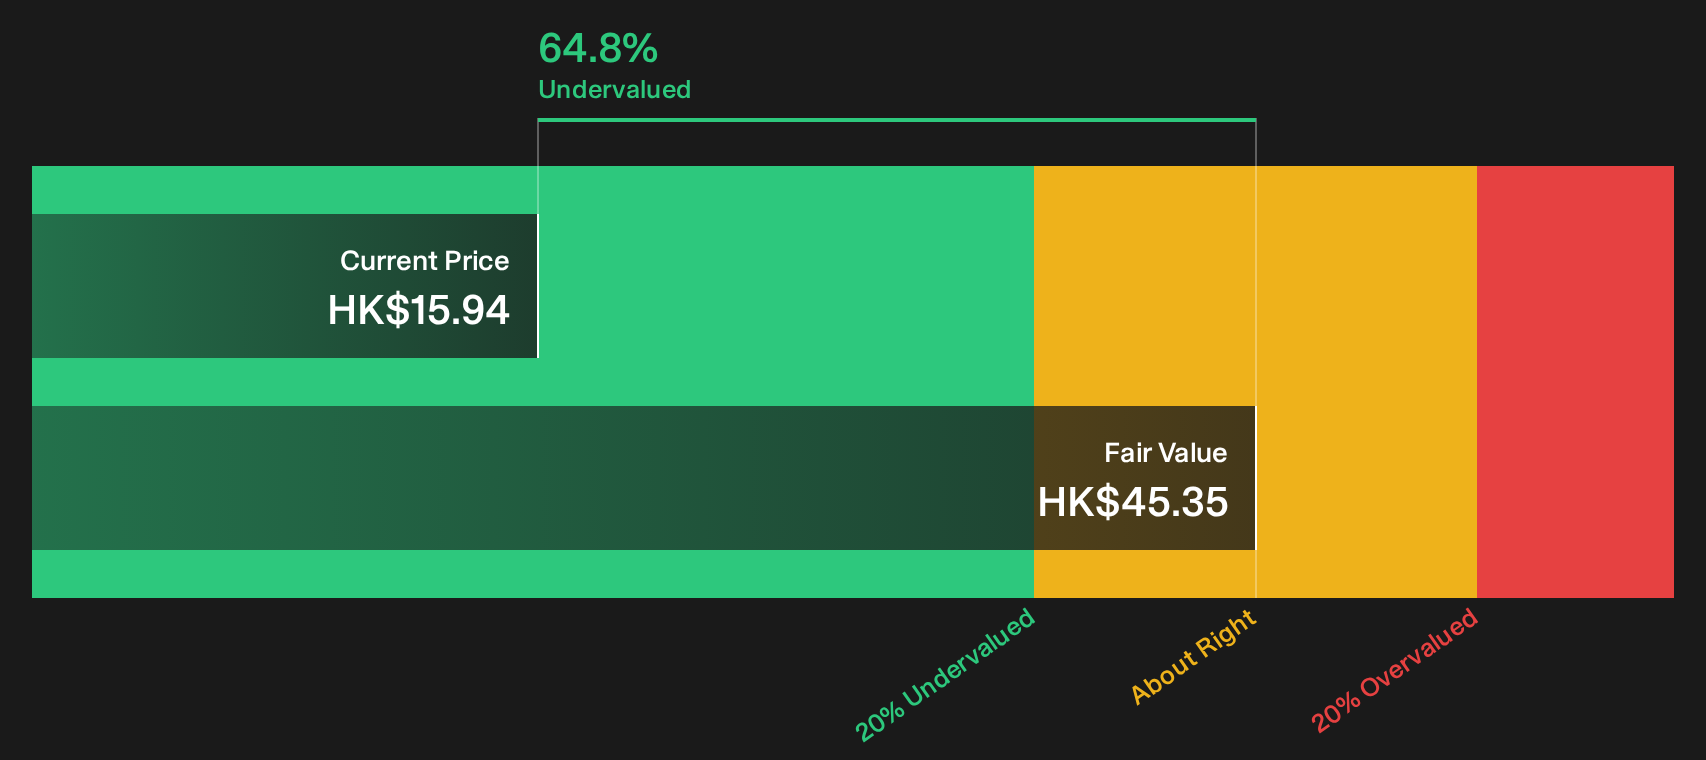
While the popular narrative leans on analyst targets and a fair value of HK$19.54, the SWS DCF model presents a far stronger picture. On that framework, PICC Property and Casualty at HK$15.94 screens as heavily undervalued against an estimated future cash flow value of HK$45.35. That is a sizable gap. Which story do you place more weight on: market price or cash flow calculations?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on PICC Property and Casualty can be confusing, so move quickly, review the numbers yourself, and then weigh up the 3 key rewards and 1 important warning sign
Looking for more ideas beyond PICC Property and Casualty?
If PICC Property and Casualty has sharpened your focus, do not stop there. Use the Simply Wall St Screener to uncover fresh, data driven opportunities today.
- Target potential mispricings by scanning our 183 high quality undervalued stocks and see which businesses line up with your preferred balance of quality and price.
- Secure more dependable balance sheets by filtering through a list of solid balance sheet and fundamentals (207 results) that can help you stress test your portfolio against tougher conditions.
- Get ahead of the crowd by reviewing 619 high quality undiscovered gems before they attract wider attention and capital.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com